
I am a creature of habit in my personal and professional life, and in the context of the content that I post online, there is a ritual that I follow with my data updates. I start the year with my general data update online, and follow up with a series of posts where I examine the implications of this data for investing and corporate finance. Since 2008, I have also done annual update papers on equity risk premiums in March of each year, with the link to the 2026 update here, and country risk in July of each year, where I look at the topics in more details, trying as best as I can to integrate the data, research and my own thinking. This year’s country risk update paper is now available, and as in prior years, I will spend this post looking what causes risk to vary across countries, how to measure those risk variations and the implications for businesses and investors.
Country Risk: Relevance
In my years as a business school student, country risk was given short shrift and I don’t remember spending much time talking or thinking about it. Part of the reason was that business school education was dollar-centric and built on the presumption that most graduates would go to work in New York, London or Tokyo, and have little need to confront country risk on a day-to-day basis. For those who raised country risk as an issue, the response was that you could, as a company or investor with global exposure, diversify it away. Both presumptions were wrong even then, and have become even more flawed over time as we have sold both companies and investors on the benefits of globalization.
For businesses, the exposure to country risk comes from both the revenue side, as larger portions of every company’s revenues come from foreign markets, and the cost side, as production gets outsourced to locales overseas. That exposure tends to increase as companies scale up, and is higher in some sectors than others; technology companies, for instance, get far more of their revenues from other non-domestic markets than manufacturing or service businesses. Outside of utilities (power, water), it is rare for a company to be entirely domestic-focused on both its revenue and cost sides. For investors, the initial draw of investing in foreign markets might have been diversification but the greater pull has come from greed, i.e., the belief that you can higher returns in the rest of the world. That process was accelerated by the creation of investment vehicles (index and mutual funds) that made investing overseas easier, the lowering of transactions costs across markets and a greater standardization of financial statements and disclosure across the globe. The home bias in portfolios, i.e., the skewing of portfolios towards domestic market investments, has not disappeared but it is lower than it was at the turn of the last century.
The notion that country risk is diversifiable, i.e., that if you are operating or investing across the world, the risks will average out across countries, has been undercut by the increased correlation across global equity markets, and especially so during market crises (which is when you care the most). At the risk of being hyperbolic, there is no place to hide from country risk, for either businesses or investors, and ignoring or dismissing country risk is not an option. I discovered this truth in the 1990s, when I found myself in need of a mechanism to incorporate country risk into my corporate financial analysis and valuations, and the process that you see described in this post was born from that need. I would hasten to add that the process that I describe has very little intellectual firepower behind it, puts pragmatism ahead of theory and most importantly is a work-in-process.
Country Risk: Drivers
I don’t think that there would be much disagreement, if I assert that it is riskier to invest in some parts of the world than others, but there is likely to be plenty of disagreement on why there are risk differences and which parts of the world are riskiest. In the broadest sense, I argue that variation in business risk across countries can be traced to four factors - the political structure of the country (democracy vs authoritarian), the prevalence of corruption in the country (operating as a hidden tax and distorting business outcomes), the extent of violence in the country (from internal and external forces) and the strength of the legal system in enforcing property rights and contractual obligations.
On the political risk front, I looked at the EIU’s Democracy Index, a composite score measuring both political freedom and protections of civil liberties, with the caveat that any index that tries to measure these will make subjective judgements that not everyone will agree with. In their most recent update, here is what the EIU scores looked like around the world:
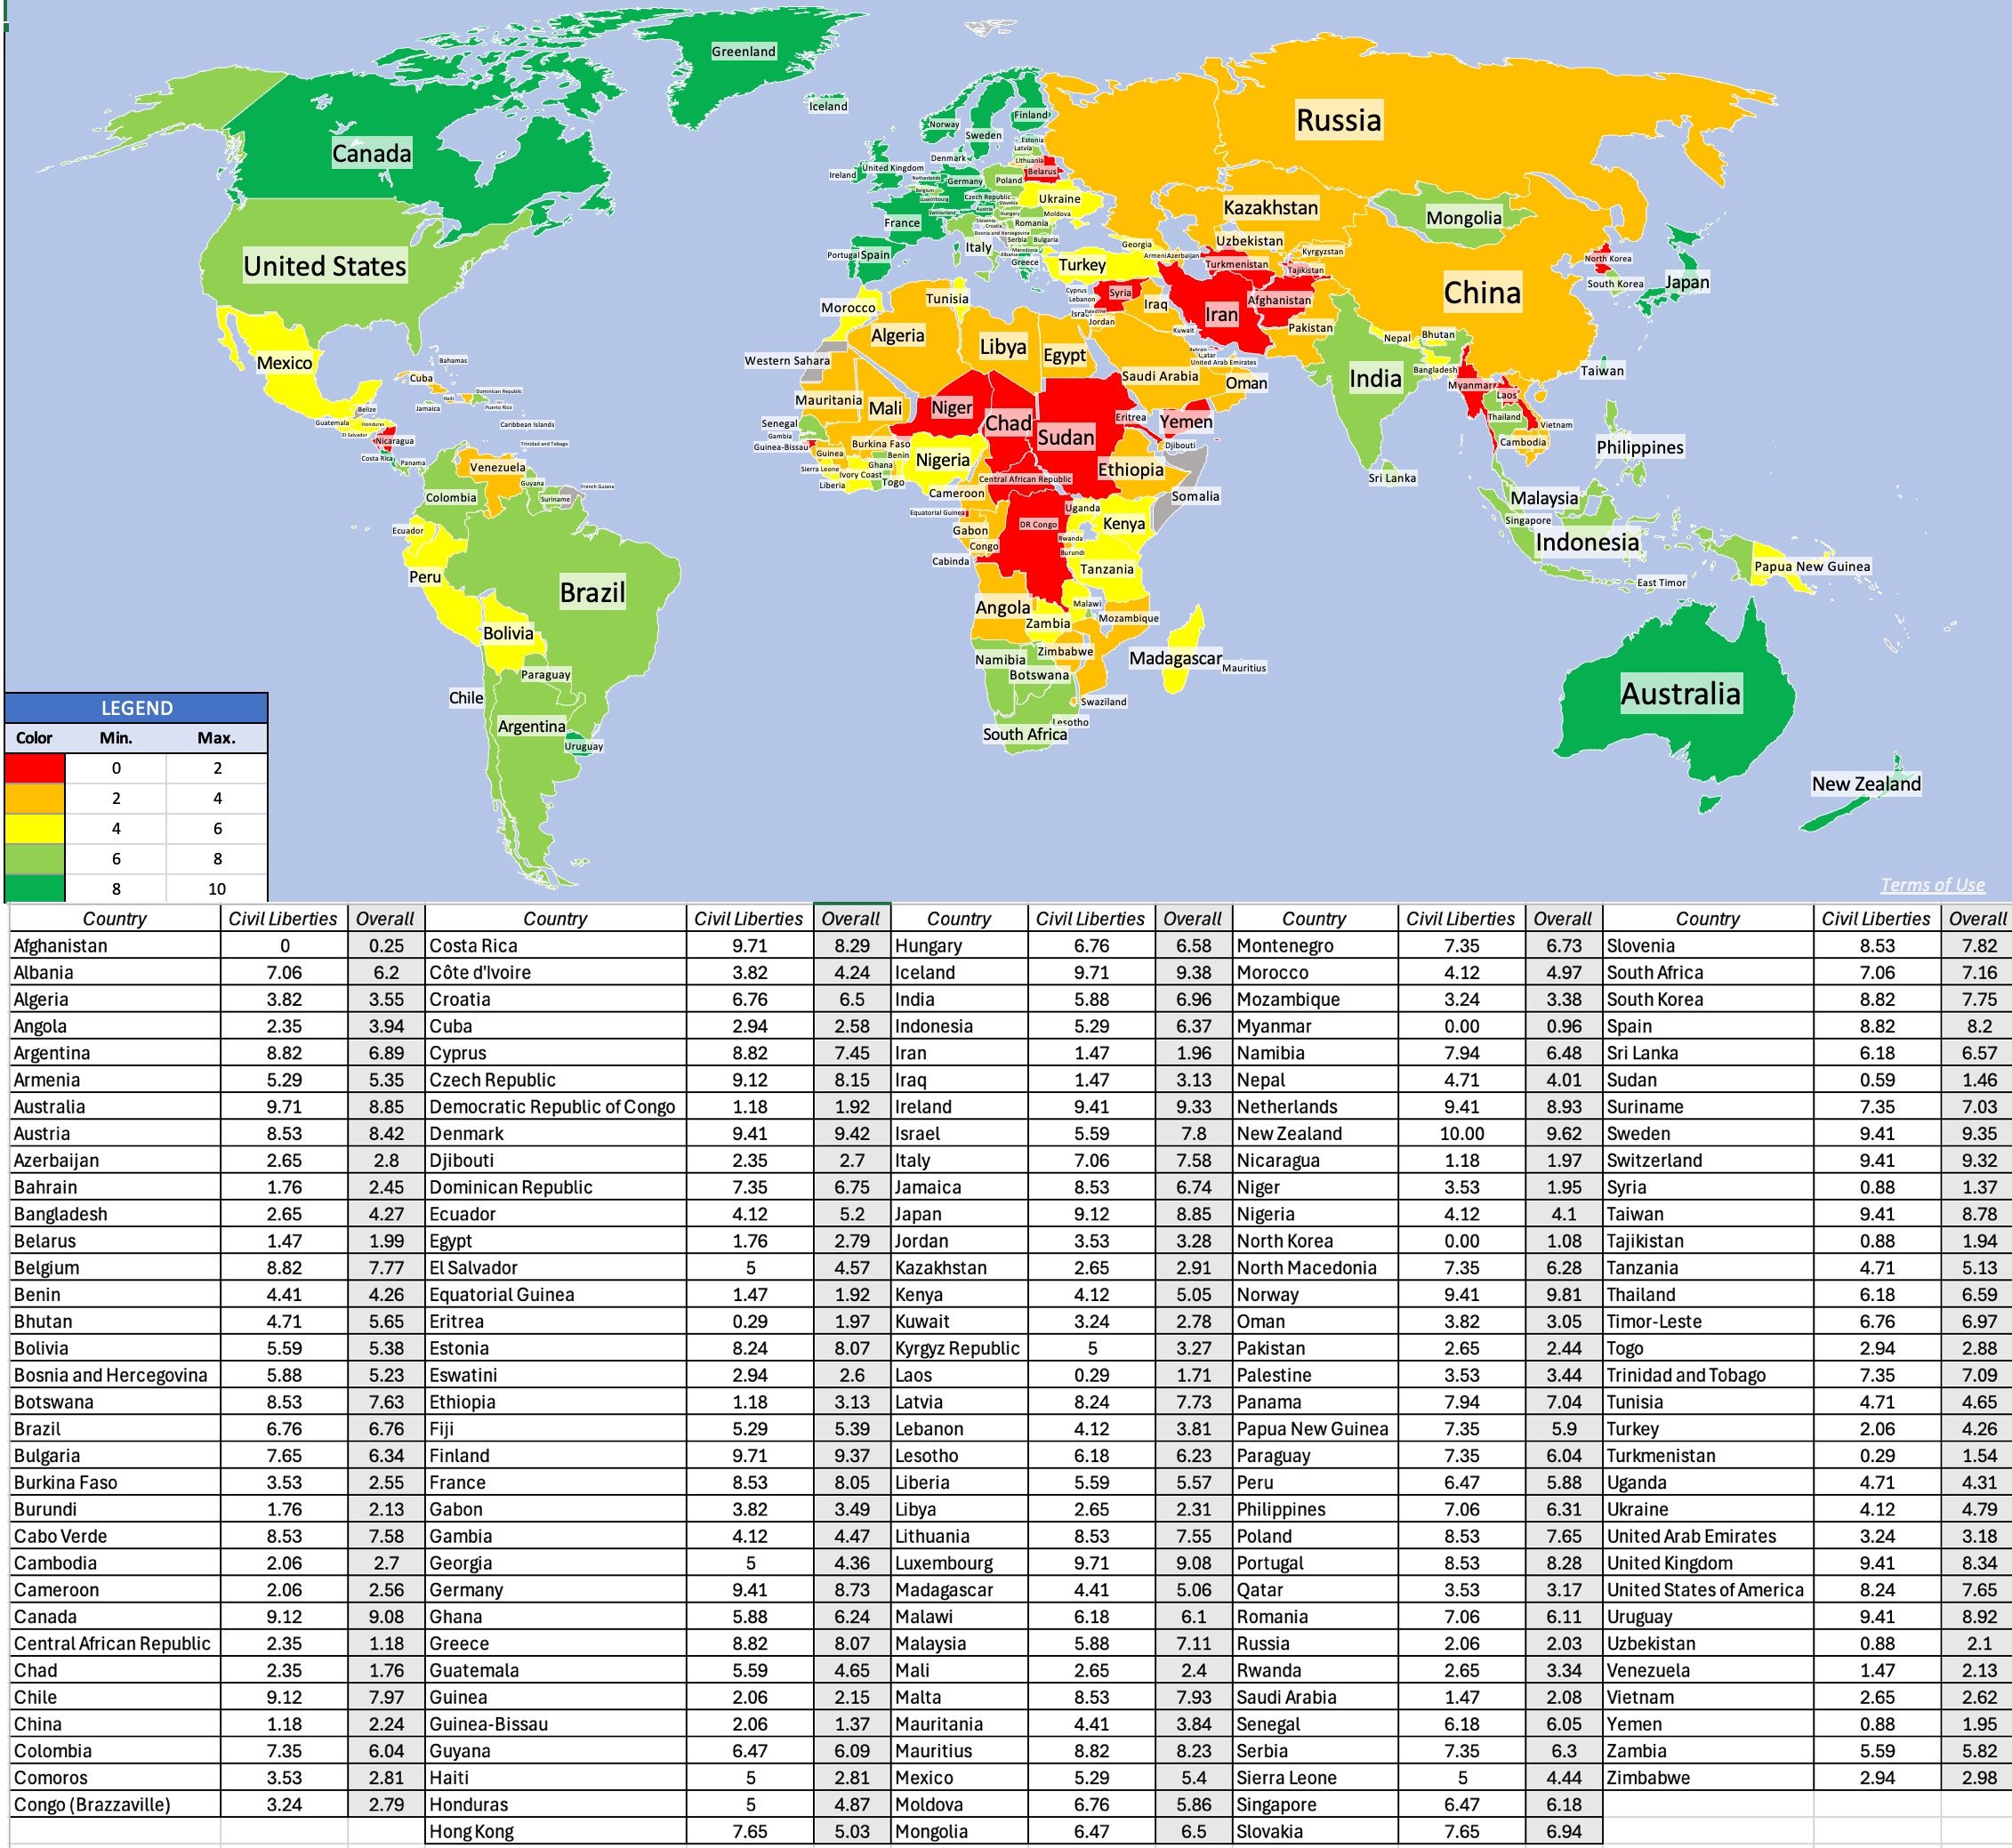
Source: Economist
Low (High) score: Least (Most) freedom
Based on these scores, the tilt towards authoritarianism has increased over the last decade, with only 7.3% of the world’s population living in democracies at the end of 2025. Note, though, that there is still an open question of whether businesses and economies do better under democratic than authoritarian regimes, and the answer in the research is at best a “maybe”. From a risk perspective, democratic regimes create more continuous risk for businesses, with elections bringing regulatory and rule changes to economies, than authoritarian regimes, where governments can promise more continuity in policy, but when change does come to the latter, it is more likely to be large and wrenching.
Corruption is a fact of life in much of the world, and businesses often have no choice but to pay the price to survive and grow. Transparency International, a global coalition against corruption, tries to capture the extent of corruption, comes up with corruption scores for countries, with lower scores indicating less corruption, and the most recent edition contains the following:
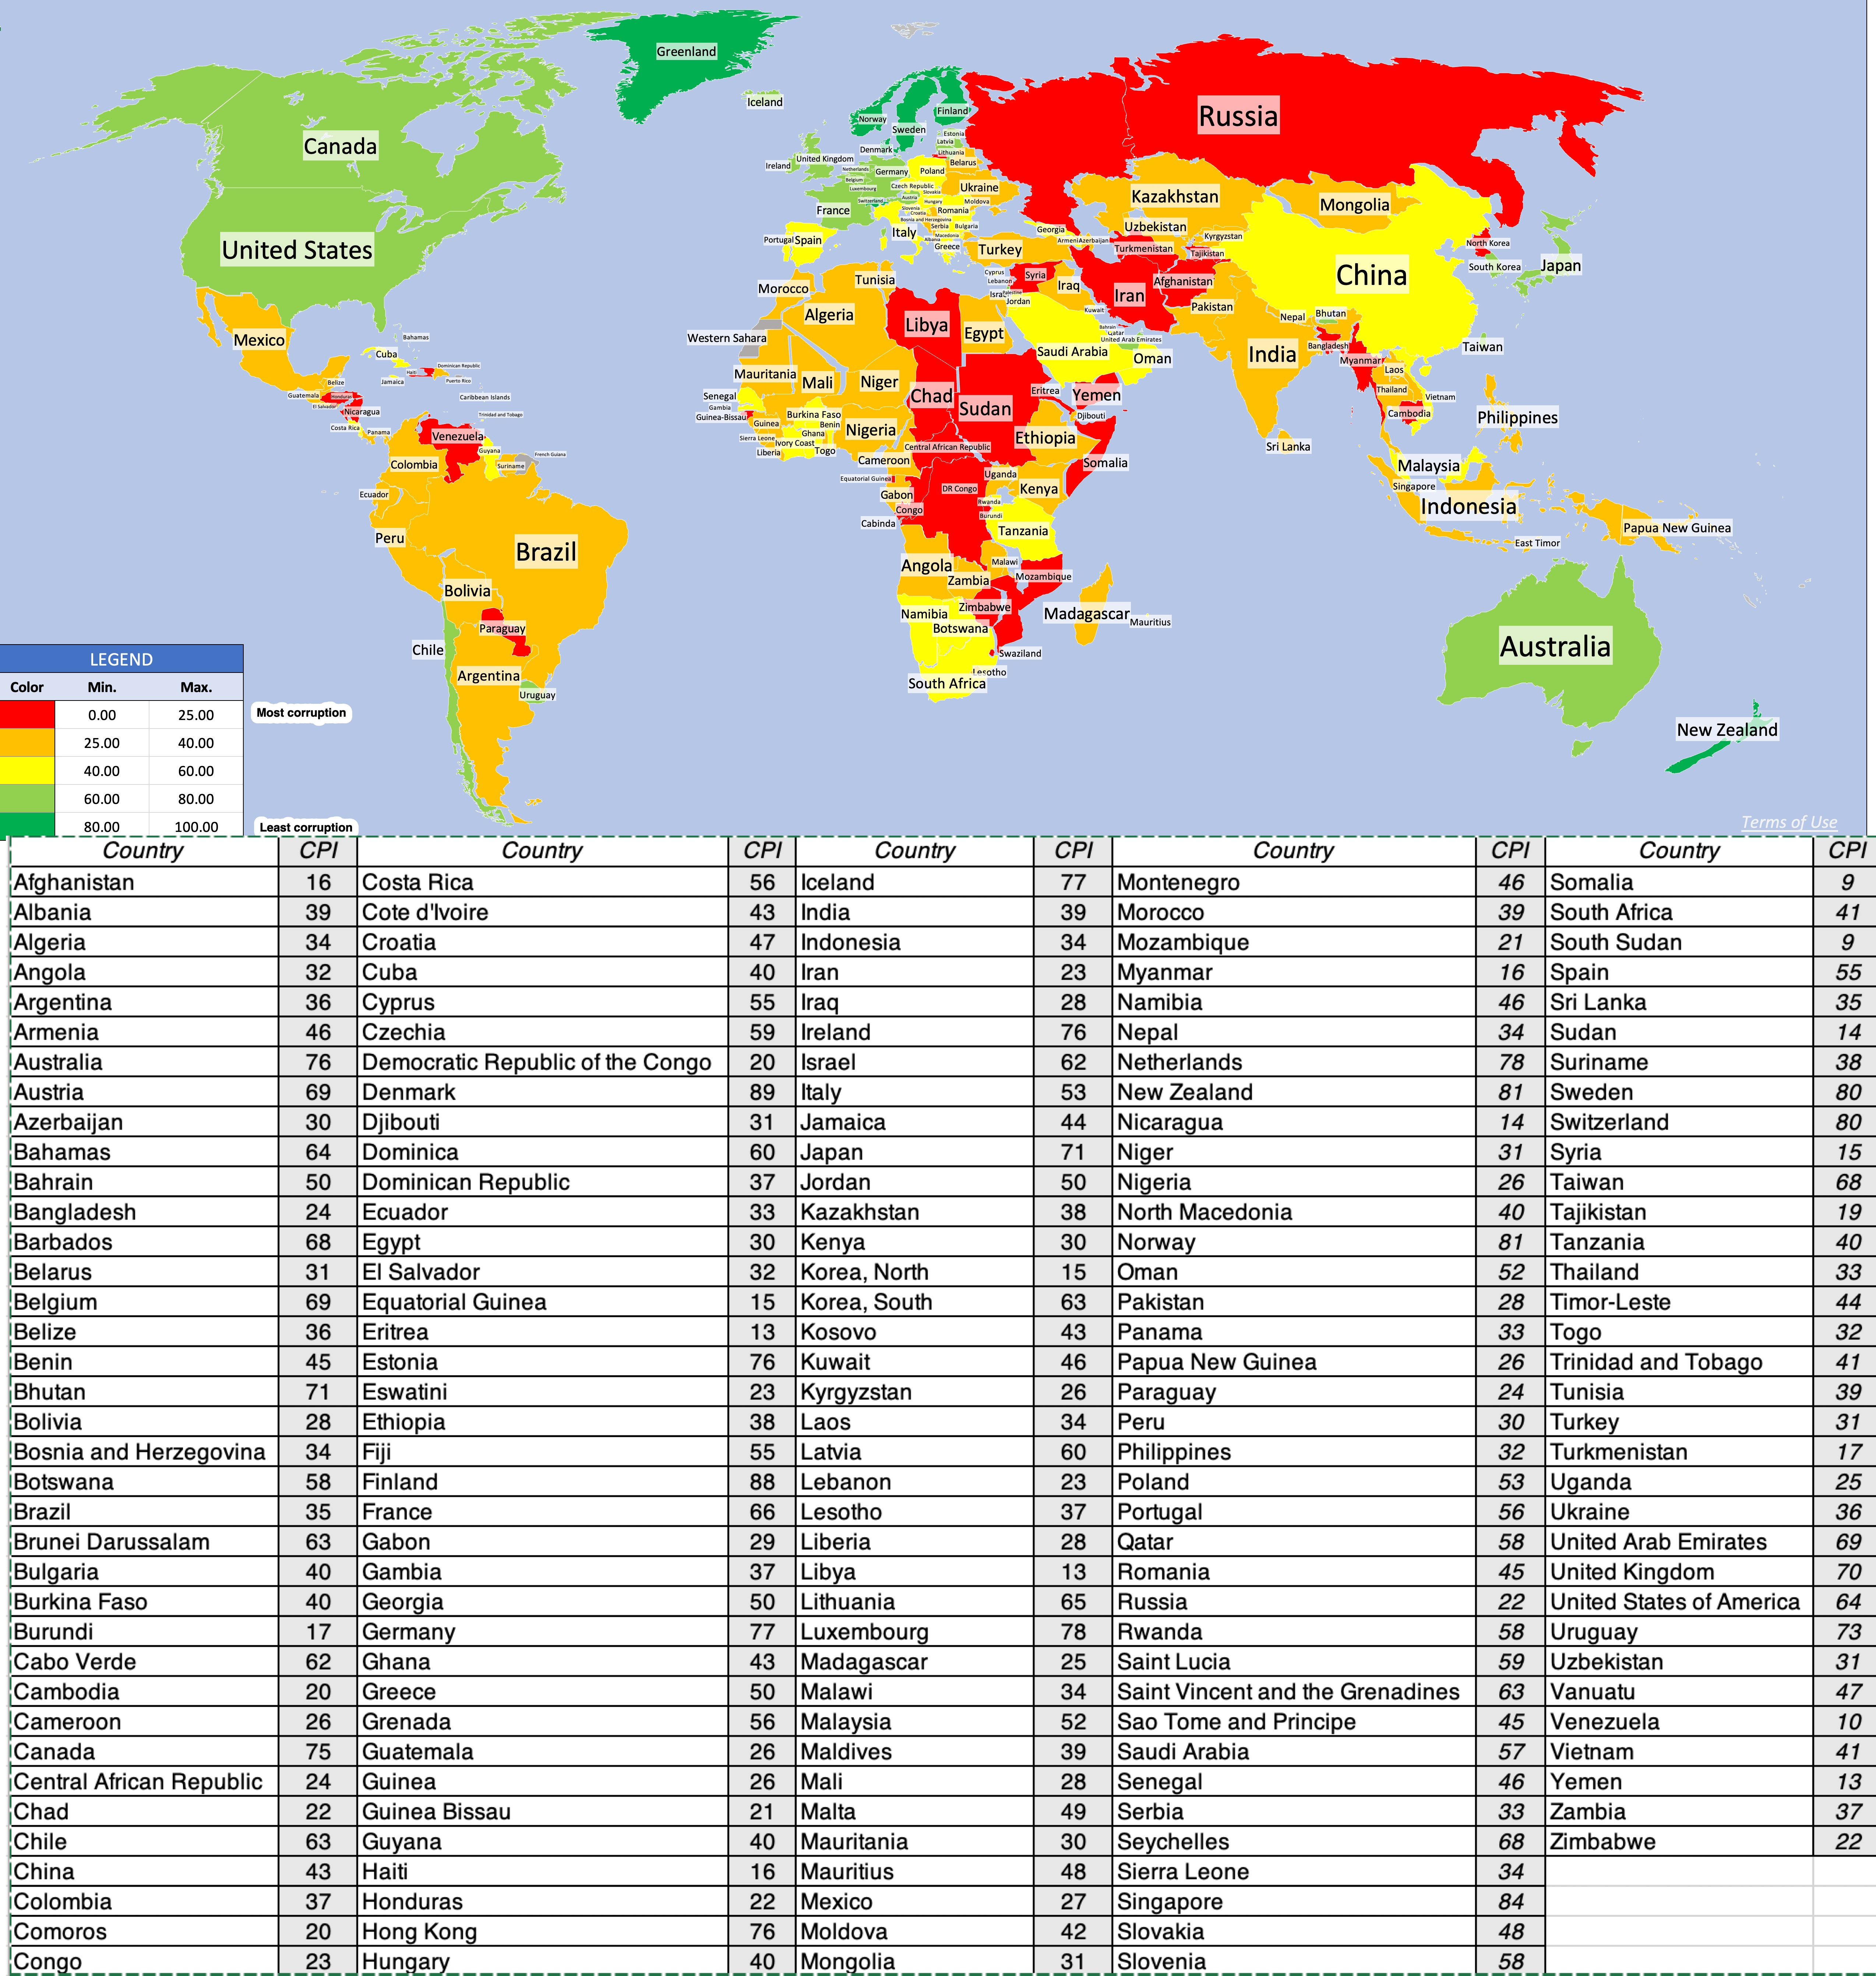
Source: Transparency International
Low (High) score: Most (Least) corruption
Northern Europe has the lowest corruption scores, followed by Canada, United States and Australia, but large portions of Africa have high exposure to corruption, with Latin America and much of Asia falling in the middle.
Living in the midst of violence takes a toll, and that toll is extracted from businesses that try to operate in its presence. Vision of Humanity computes peace scores for countries, measuring exposure to both violence within the country as well as from wars and terrorism. The most recent peace scores are reported below:
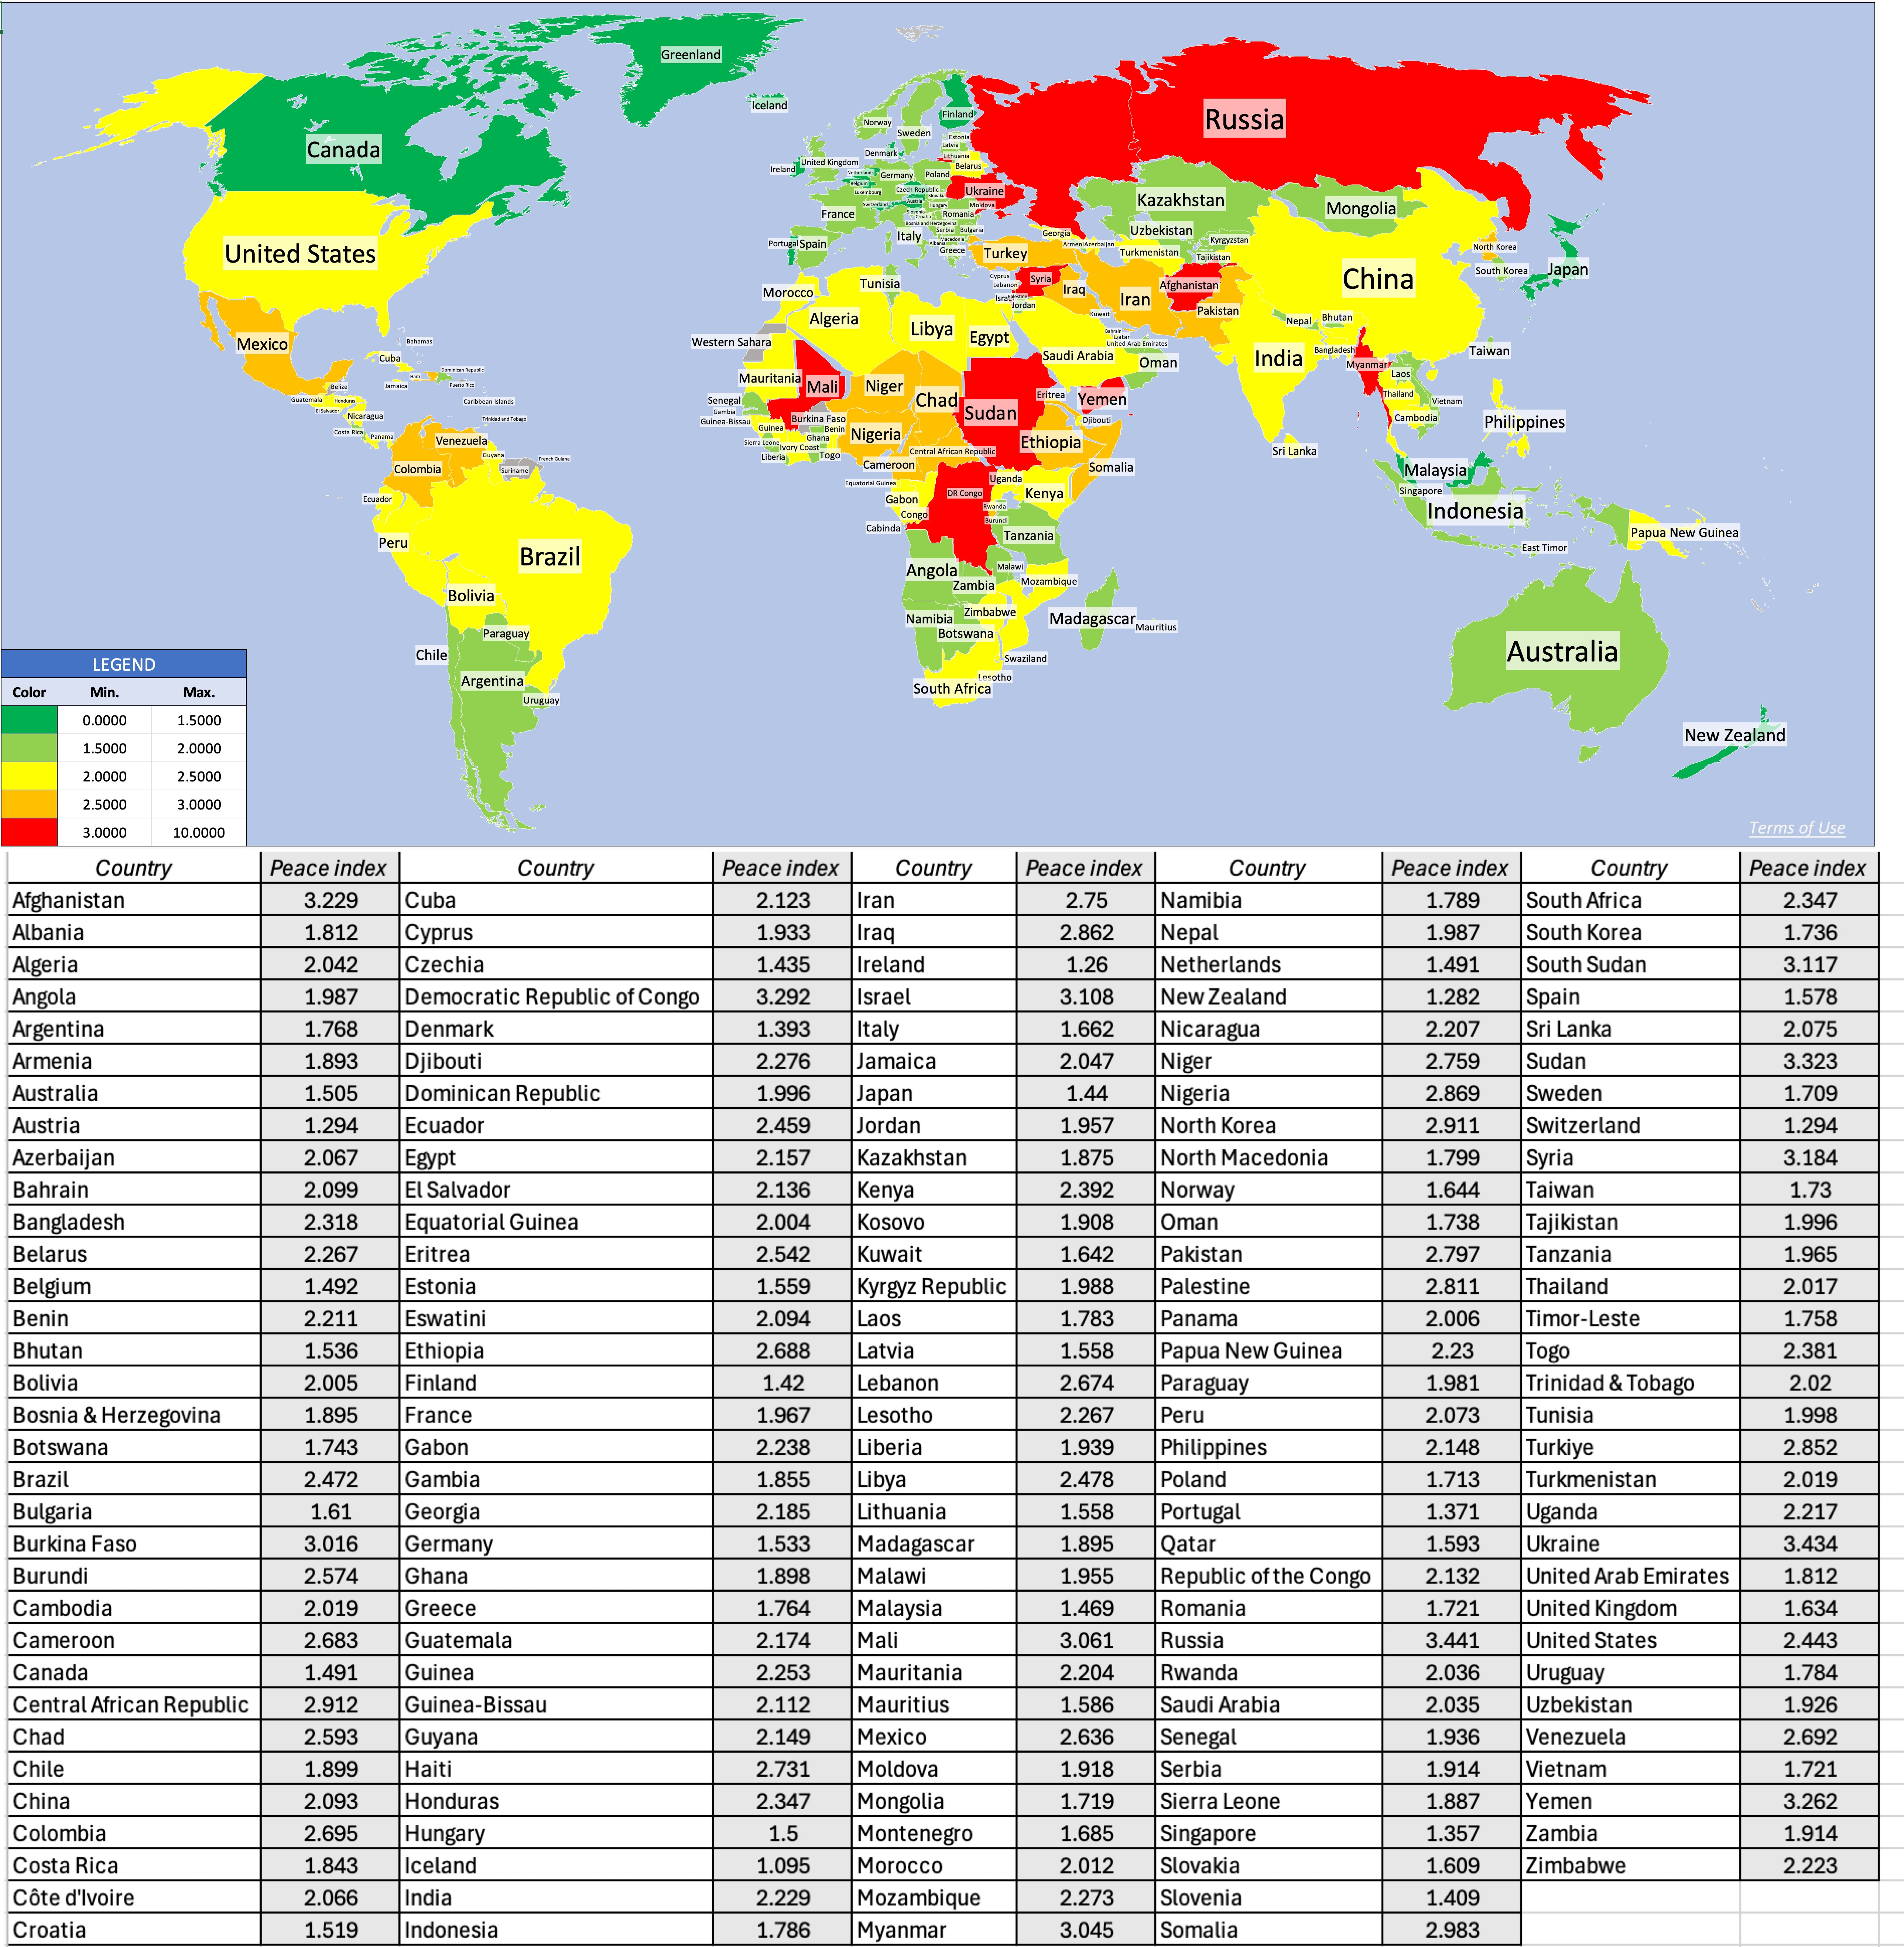
Source: Vision of Humanity
Low (High) score: Most (Least) peaceful
Canada, Australia, Japan and much of Europe score high on the peace dimension, and while Latin America and Africa score lower, there are portions of each continent that are more peaceful. The Russia-Ukraine war has created a huge area of violence across Eastern Europe and Russia, and exposure to gun violence creates a drag on the United States.
Businesses are dependent on the legal system to enforce property rights as well as contractual obligations. Countries that have legal systems that are either capricious on these fronts, or hopelessly slow in acting, create challenges for businesses that operate in them, creating both costs and risks that they otherwise would not face. Property Rights Alliance is an entity that tracks international property rights across the world, and in their most recent update, their property rights scores by country are captured below:
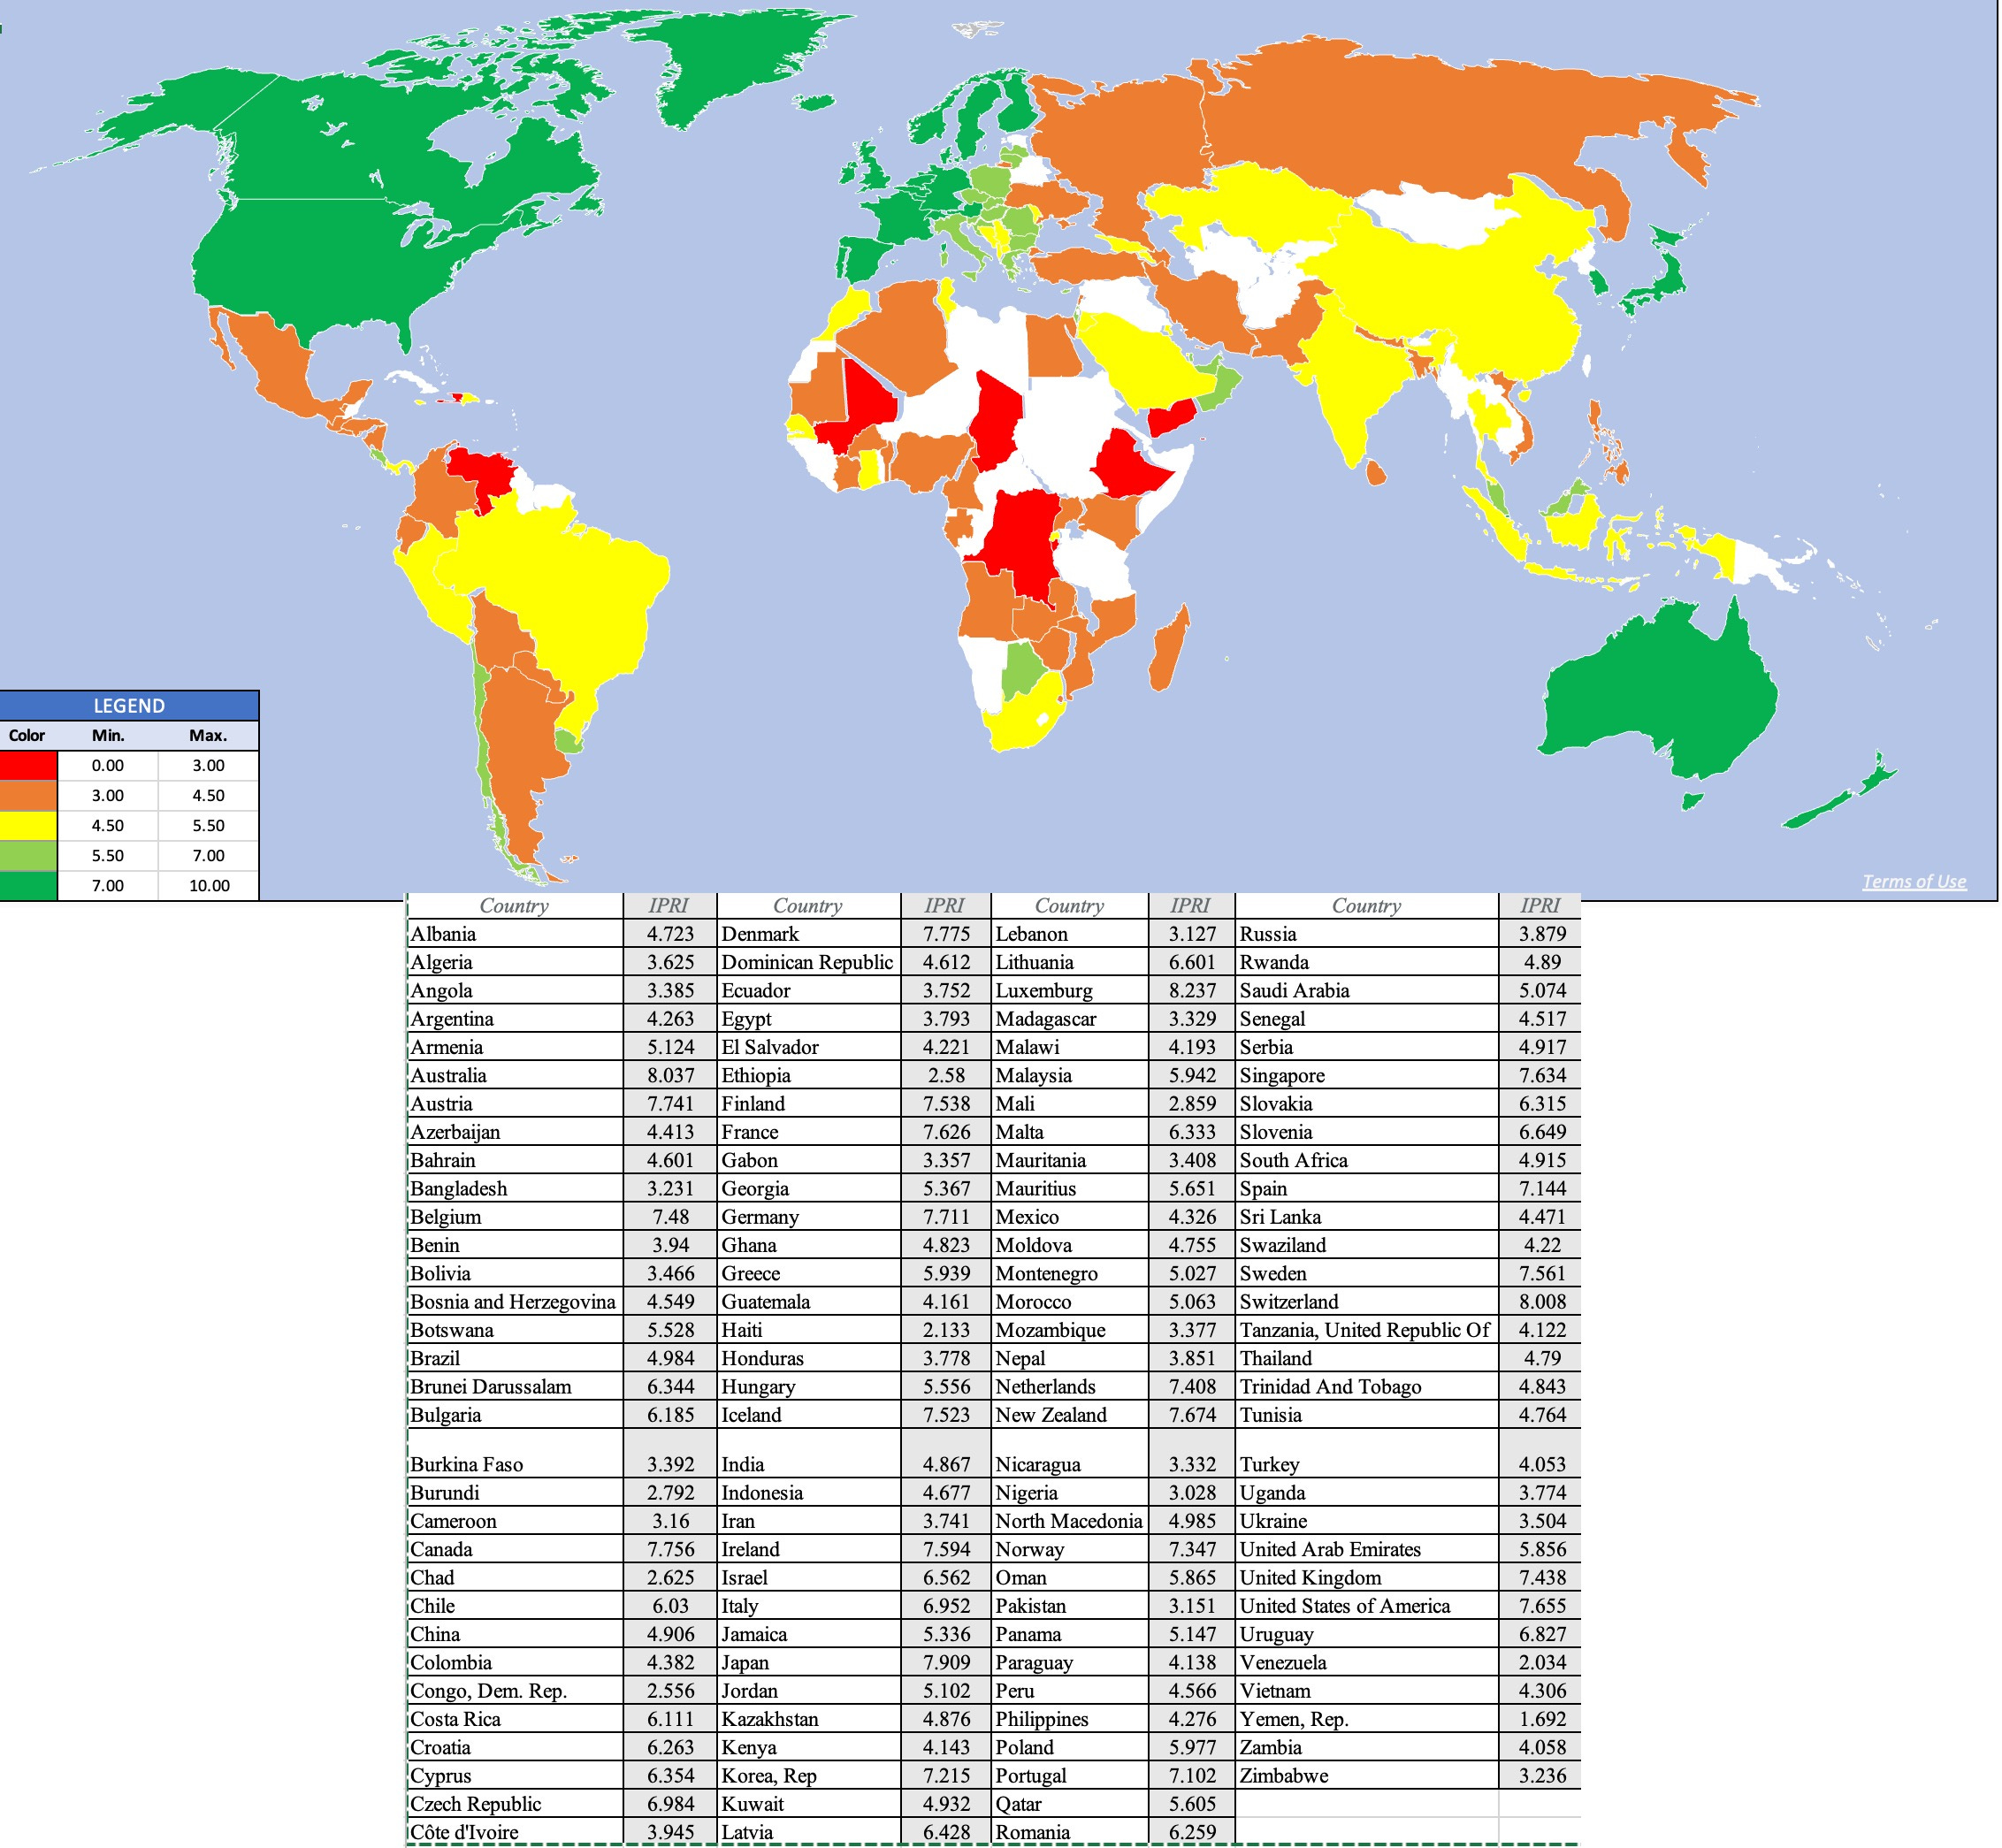
Source: International Property Rights
Low (High) score: Least (Most) property rights
There are wide differences across regions, when it comes to legal and property rights, with Latin America, Africa and Asia lagging and Europe, Australia and much of North America leading.
There is one final dimension that I have added to country risk in recent years that captures exposure to climate risk. While there are many different entities that measure this exposure, each one with its own skews, the map below which shows the climate risk exposure, by country, from GermanWatch:
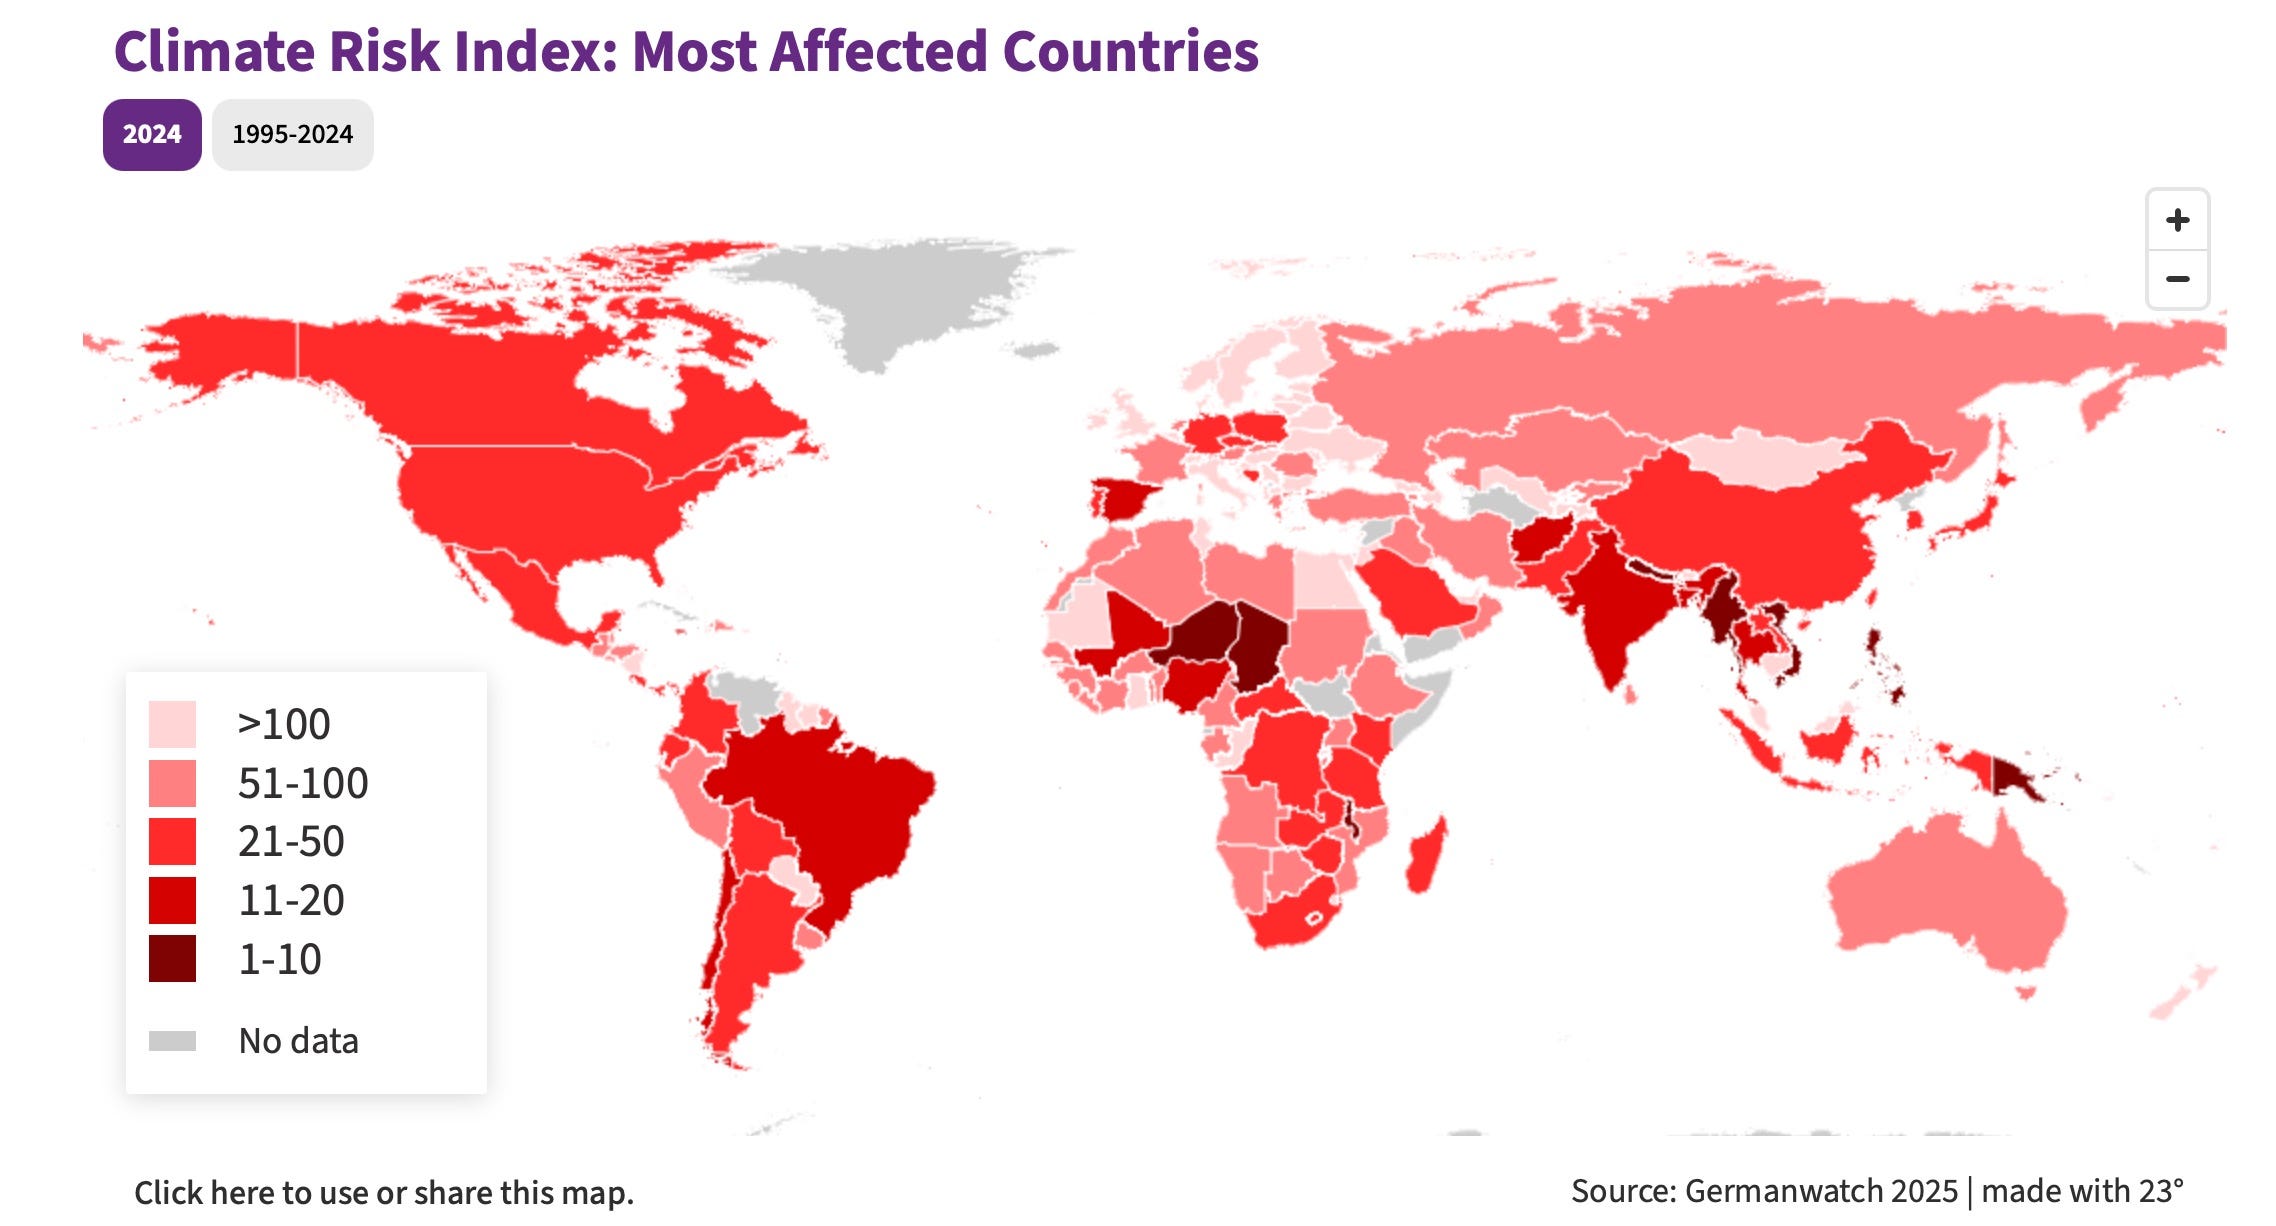
Source: GermanWatch
Low (High) score: Least (Most) affected
There are two reasons why climate risk has not become a bigger topic in country risk discussions. The first is that there is no part of the globe that is unaffected, making it less of a differentiator across countries on the risk dimension. The second is that climate risk, by itself, is an abstraction for businesses, until it starts affecting the bottom line, and while there are individual companies that are being impacted, the aggregate effects, at least at the moment, are not big enough to change the discussion.
Country Default Risk
While country risk is determined by multiple factors, the challenge that businesses is in consolidating all of those risks into one number. The market that does this most directly is the debt market, where, when countries (sovereigns) seek to borrow money, lenders determine the interest rates to charge them, based upon perceived default risk. To understand why lenders worry about default with sovereign debt, you can start by looking at the history of sovereign defaults in the graph below:
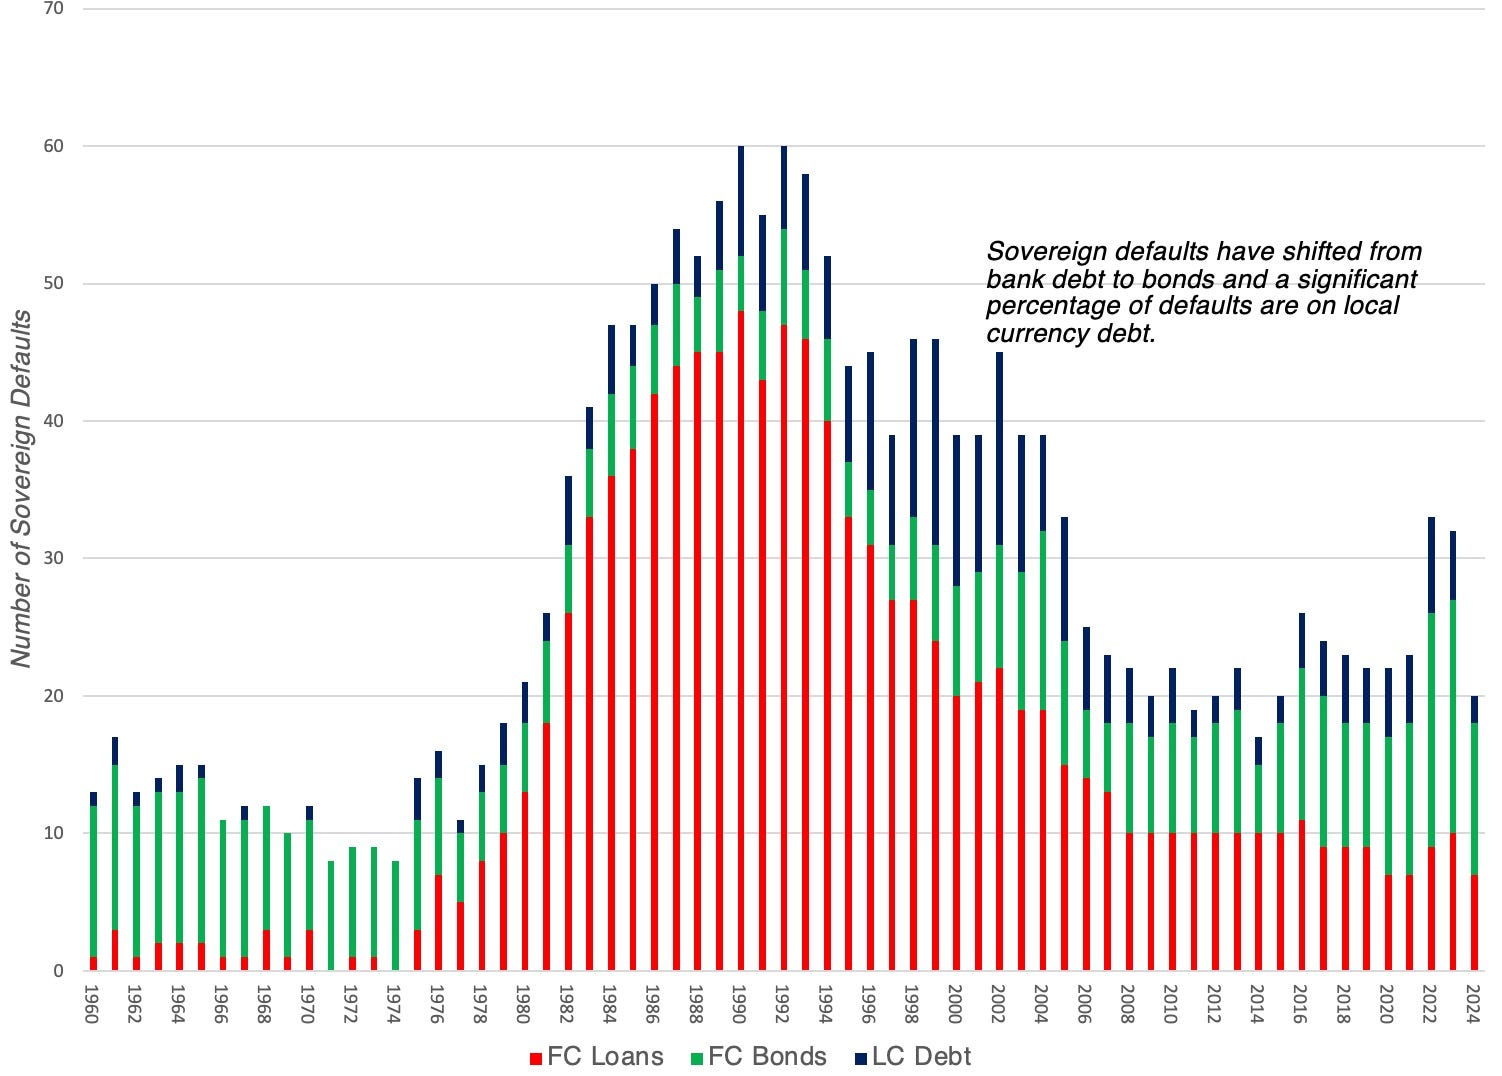
Source: BoC & BoE Sovereign Default Database
Debt defaults, which soared in the 1980s and 1990s, have been lower in this century, with a shift away from loan defaults (where banks are usually the lenders) to defaults in the bond market. It is also worth noting that a non-trivial portion of sovereign defaults in each year are local currency defaults, indicating that for some borrowers, the costs of defaulting are viewed as smaller than the costs of inflation arising from printing more currency to pay off debt. Over time, Latin America has been the epicenter for sovereign default, but at the end of 2023, sovereign debt in default had a wide geographical spread:
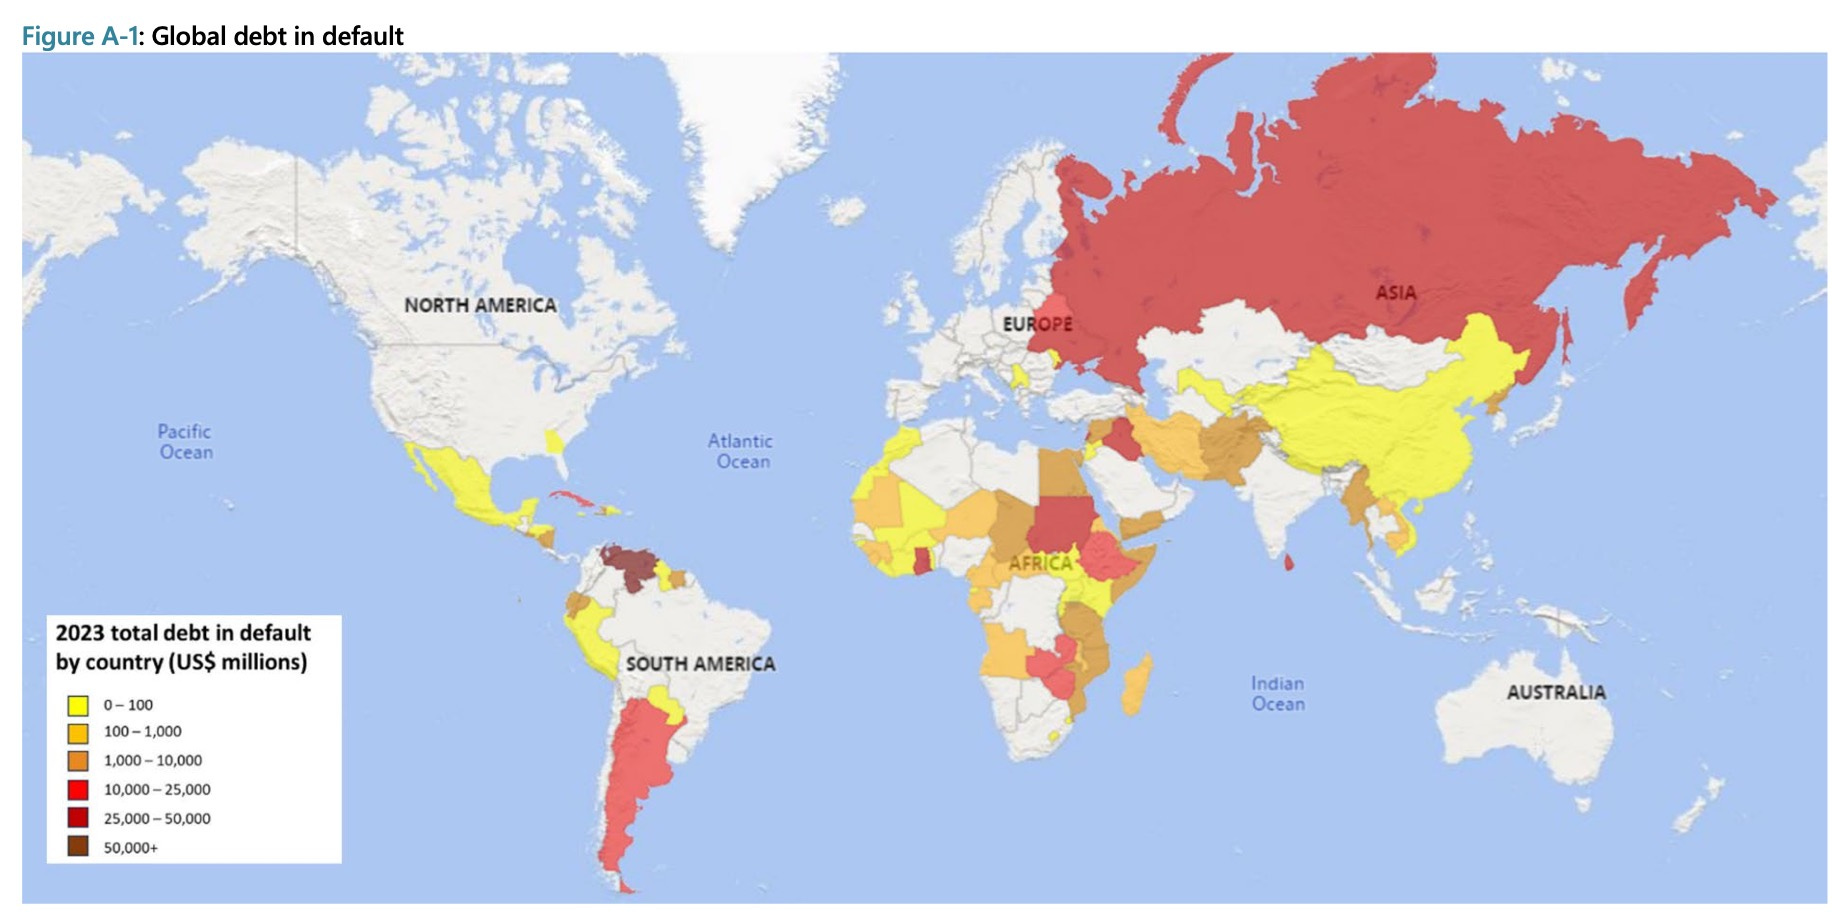
Source: BoC & BoE Sovereign Default Database
The most widely accessible measures of sovereign default risk remain sovereign ratings, with ratings agencies operating as (imperfect) arbiters. At the start of July 2026, the graph below reports the sovereign ratings for all rated countries, from S&P, Moody’s and Fitch:
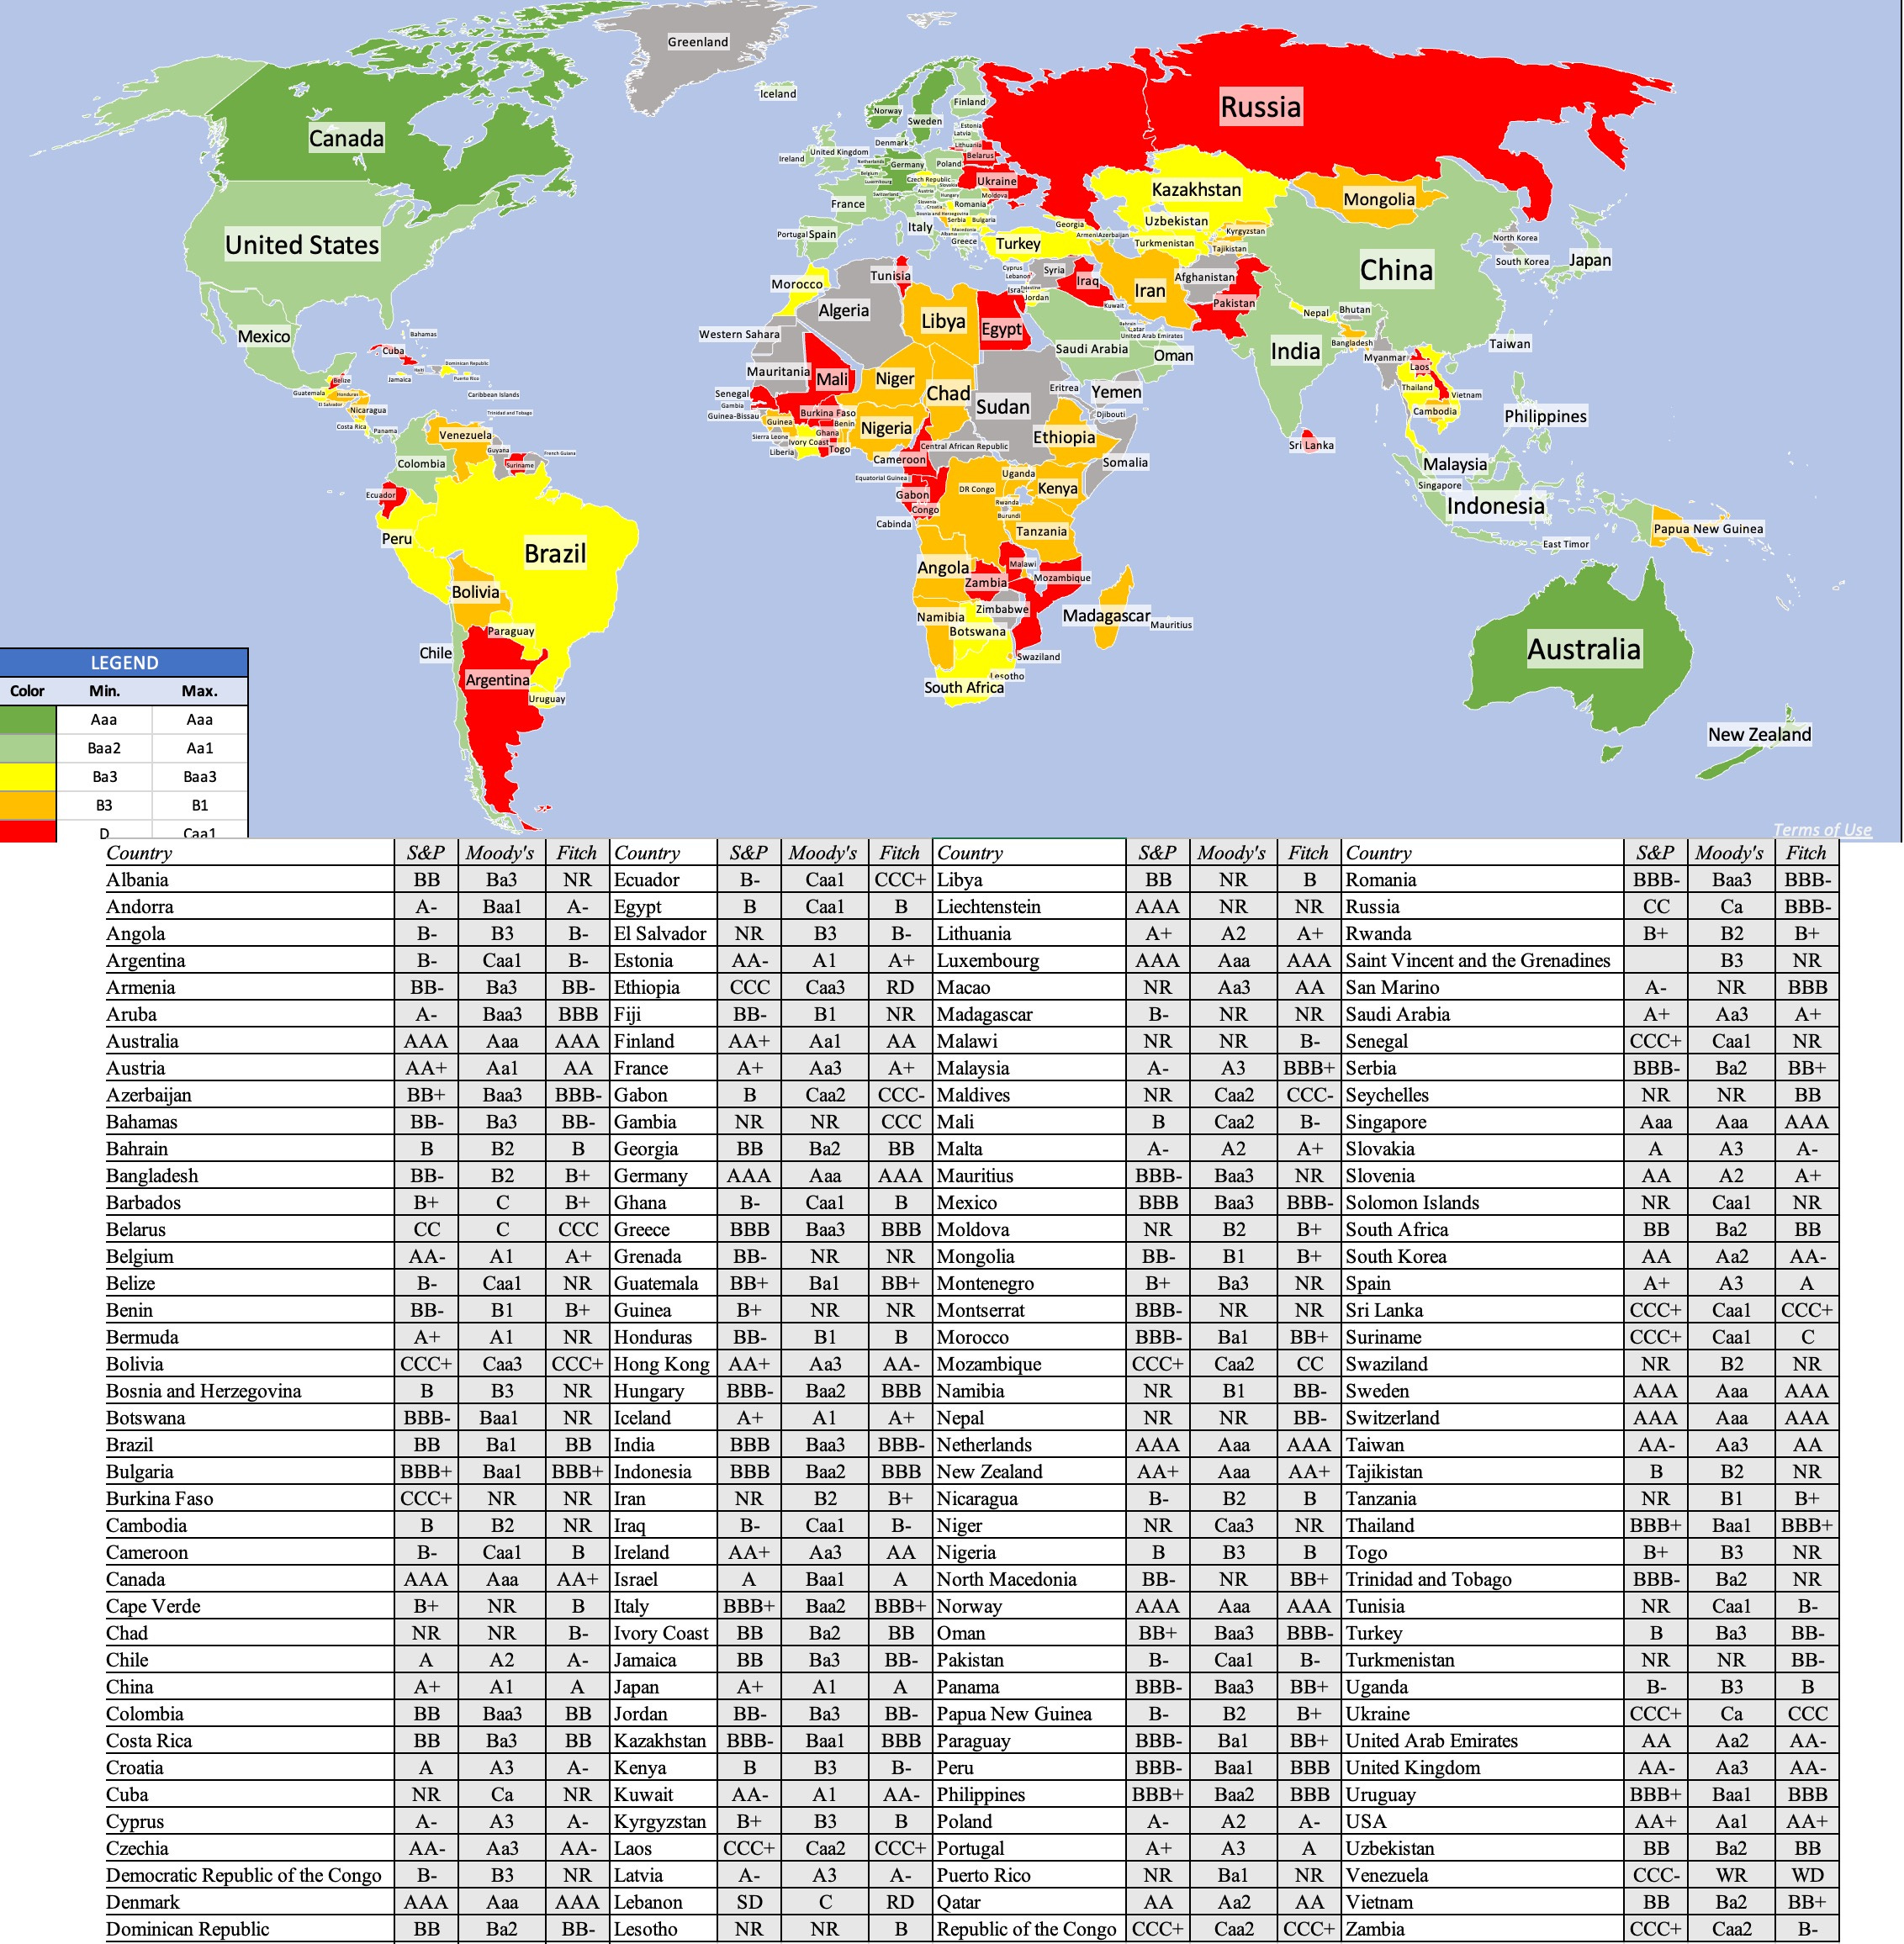
Source: Multiple public sources
As you can see, the ratings agencies mostly agree on their assessments of default risk, and sovereign ratings are correlated with the risk drivers (politics, corruption, violence, legal system) that we outlined in the last section. I do believe that ratings agencies, notwithstanding the critiques of bias and mis-measurement leveled against them, do a reasonably good job in their ratings assessments, but they are often slow to act, when confronted with change.
The sovereign CDS market offers a market-based alternative for measuring sovereign default risk, with investors making assessments of how much they would demand to insure against sovereign default in the form of (annualized) spreads. In the graph below, I list 10-year sovereign CDS spreads as of July 1, 2026:
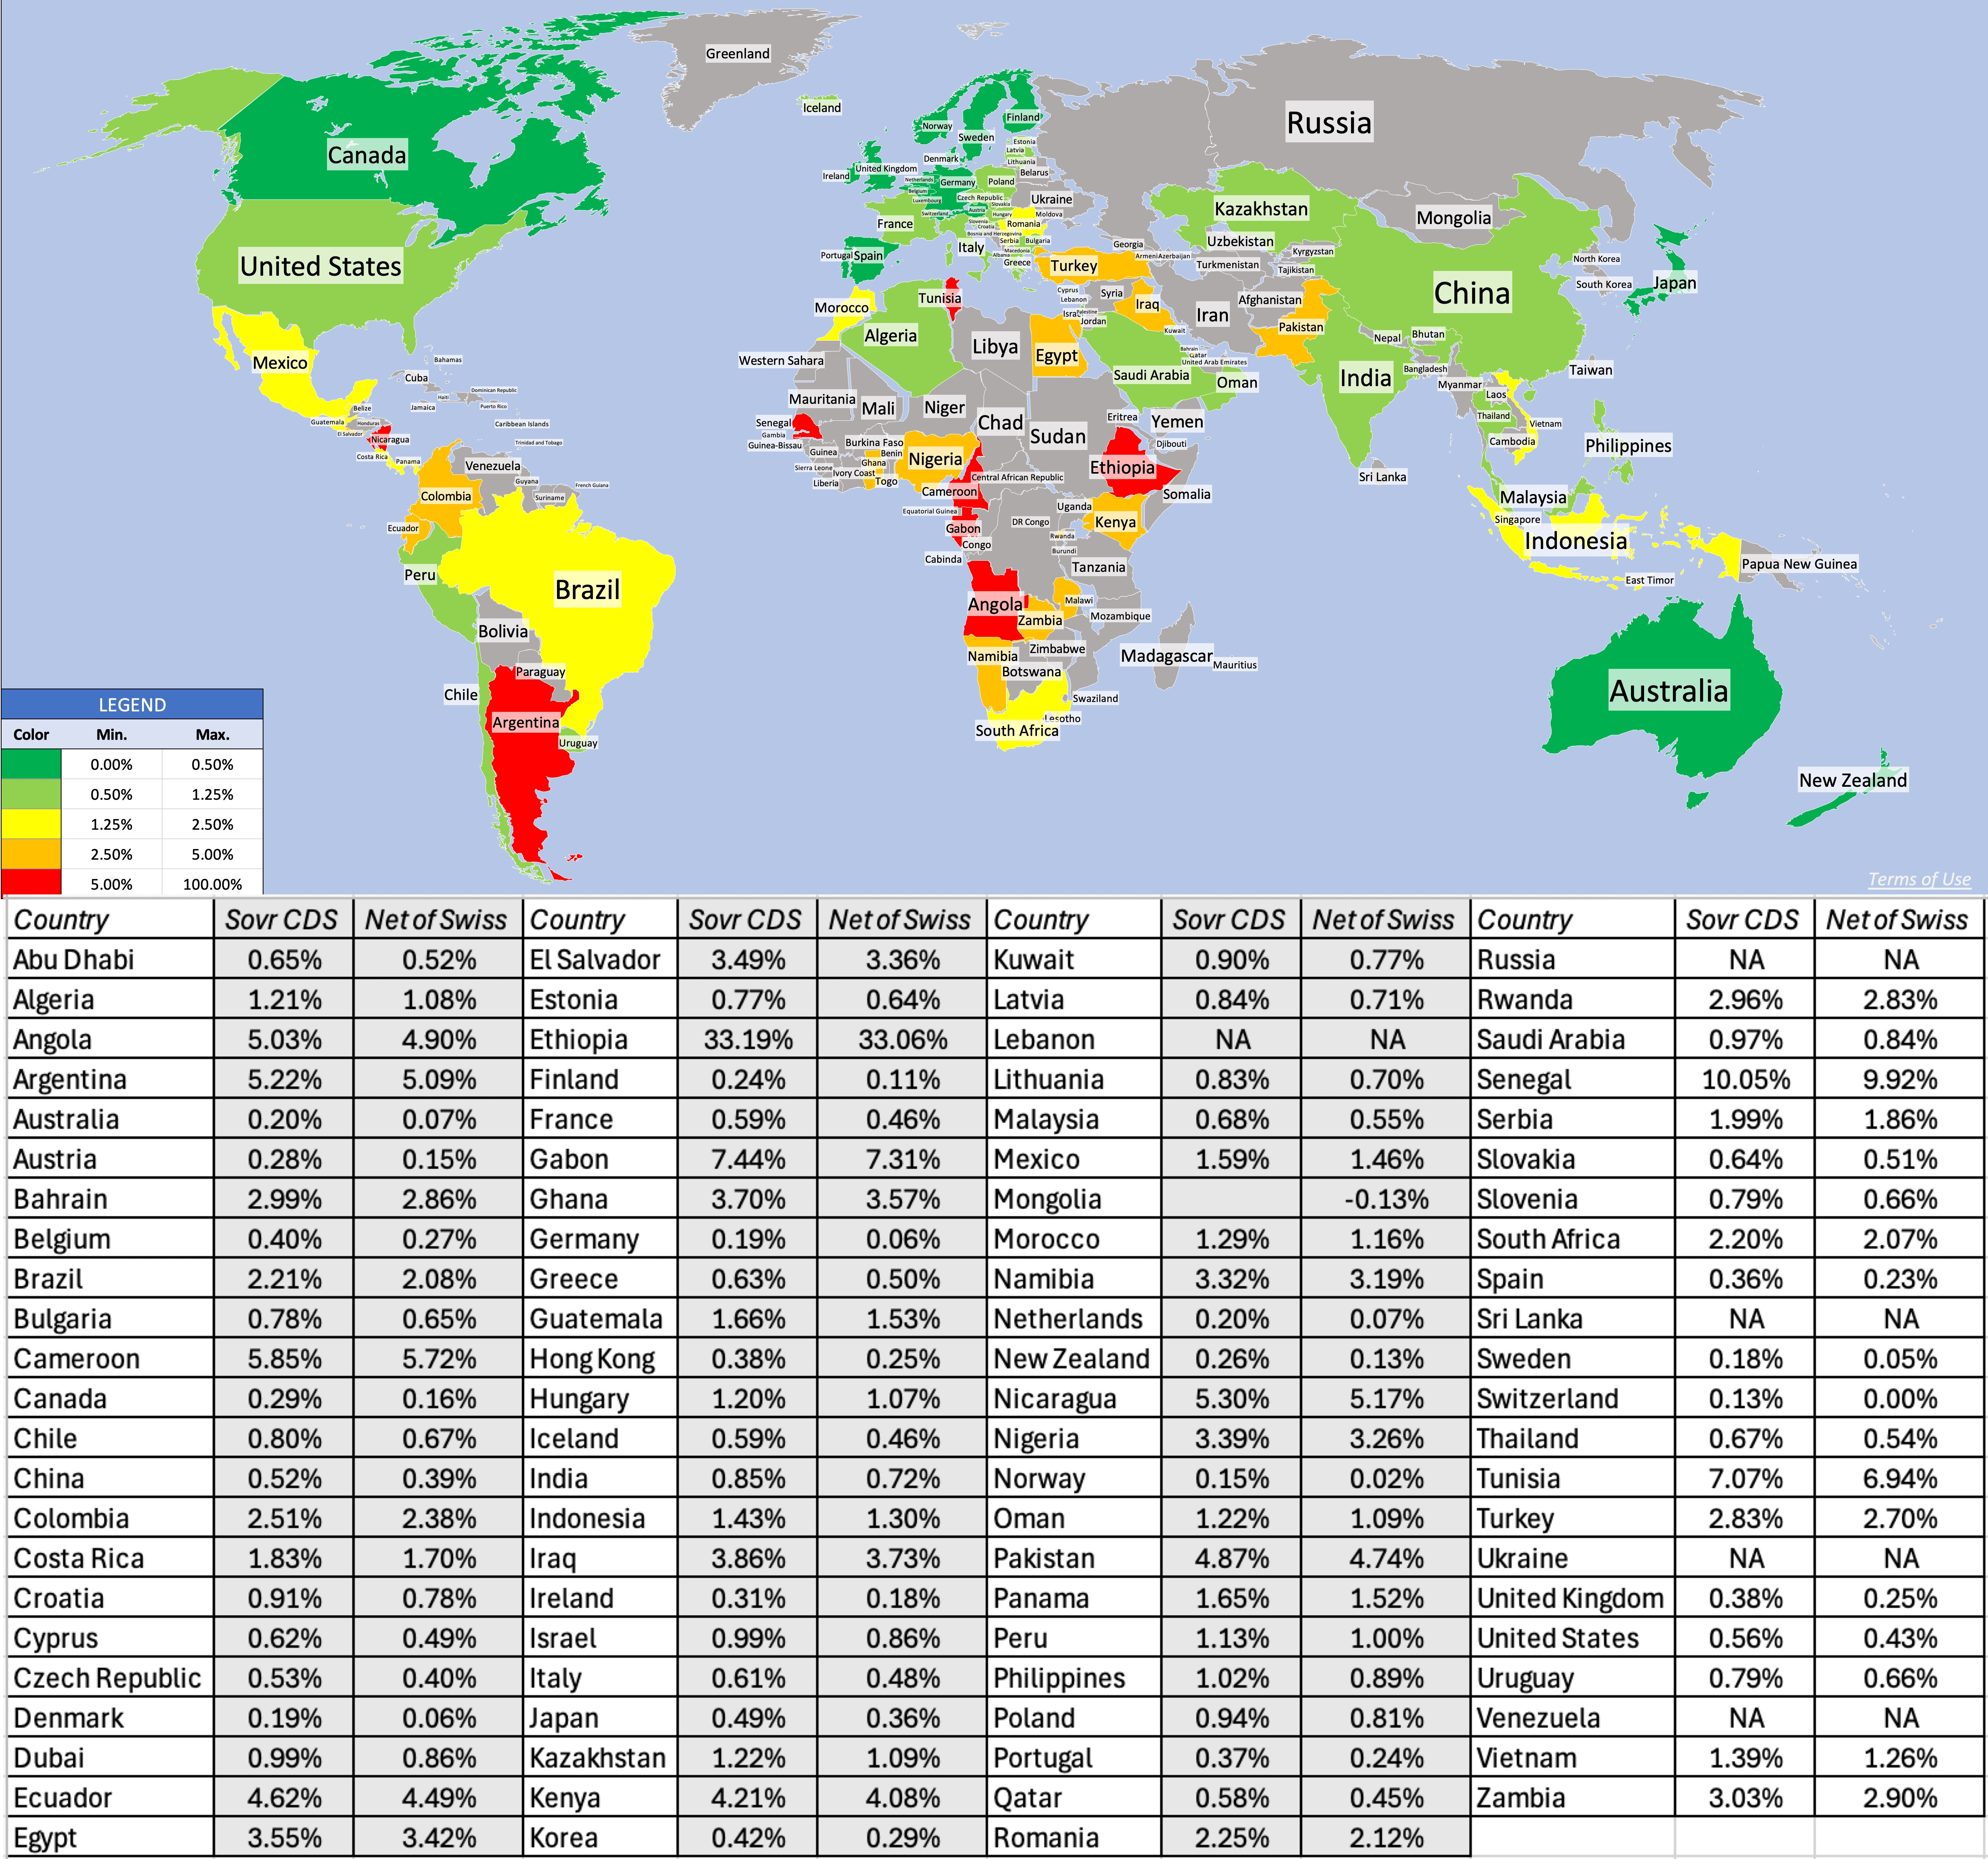
Source: Bloomberg
Note that sovereign CDS spreads are available for only 84 countries, and that there are swaths of the world (Central and North Africa, frontier markets) where they are not available.
Country Composite Risk
When you lend money to governments or buy government bonds, sovereign default risk is your key concern, and both sovereign ratings and CDS spreads try to measure that risk. When running a business in a country, you are exposed to a much wider range of risks, and measuring exposure to those risks may require different measures. One alternative is country risk scores, where services evaluate how countries measure up on different risk drivers, and come up with composite scores for these countries. In the table below, I report the country risk scores from two services - Political Risk Services (PRS) and the Economist (EIU), at the start of July 2026:
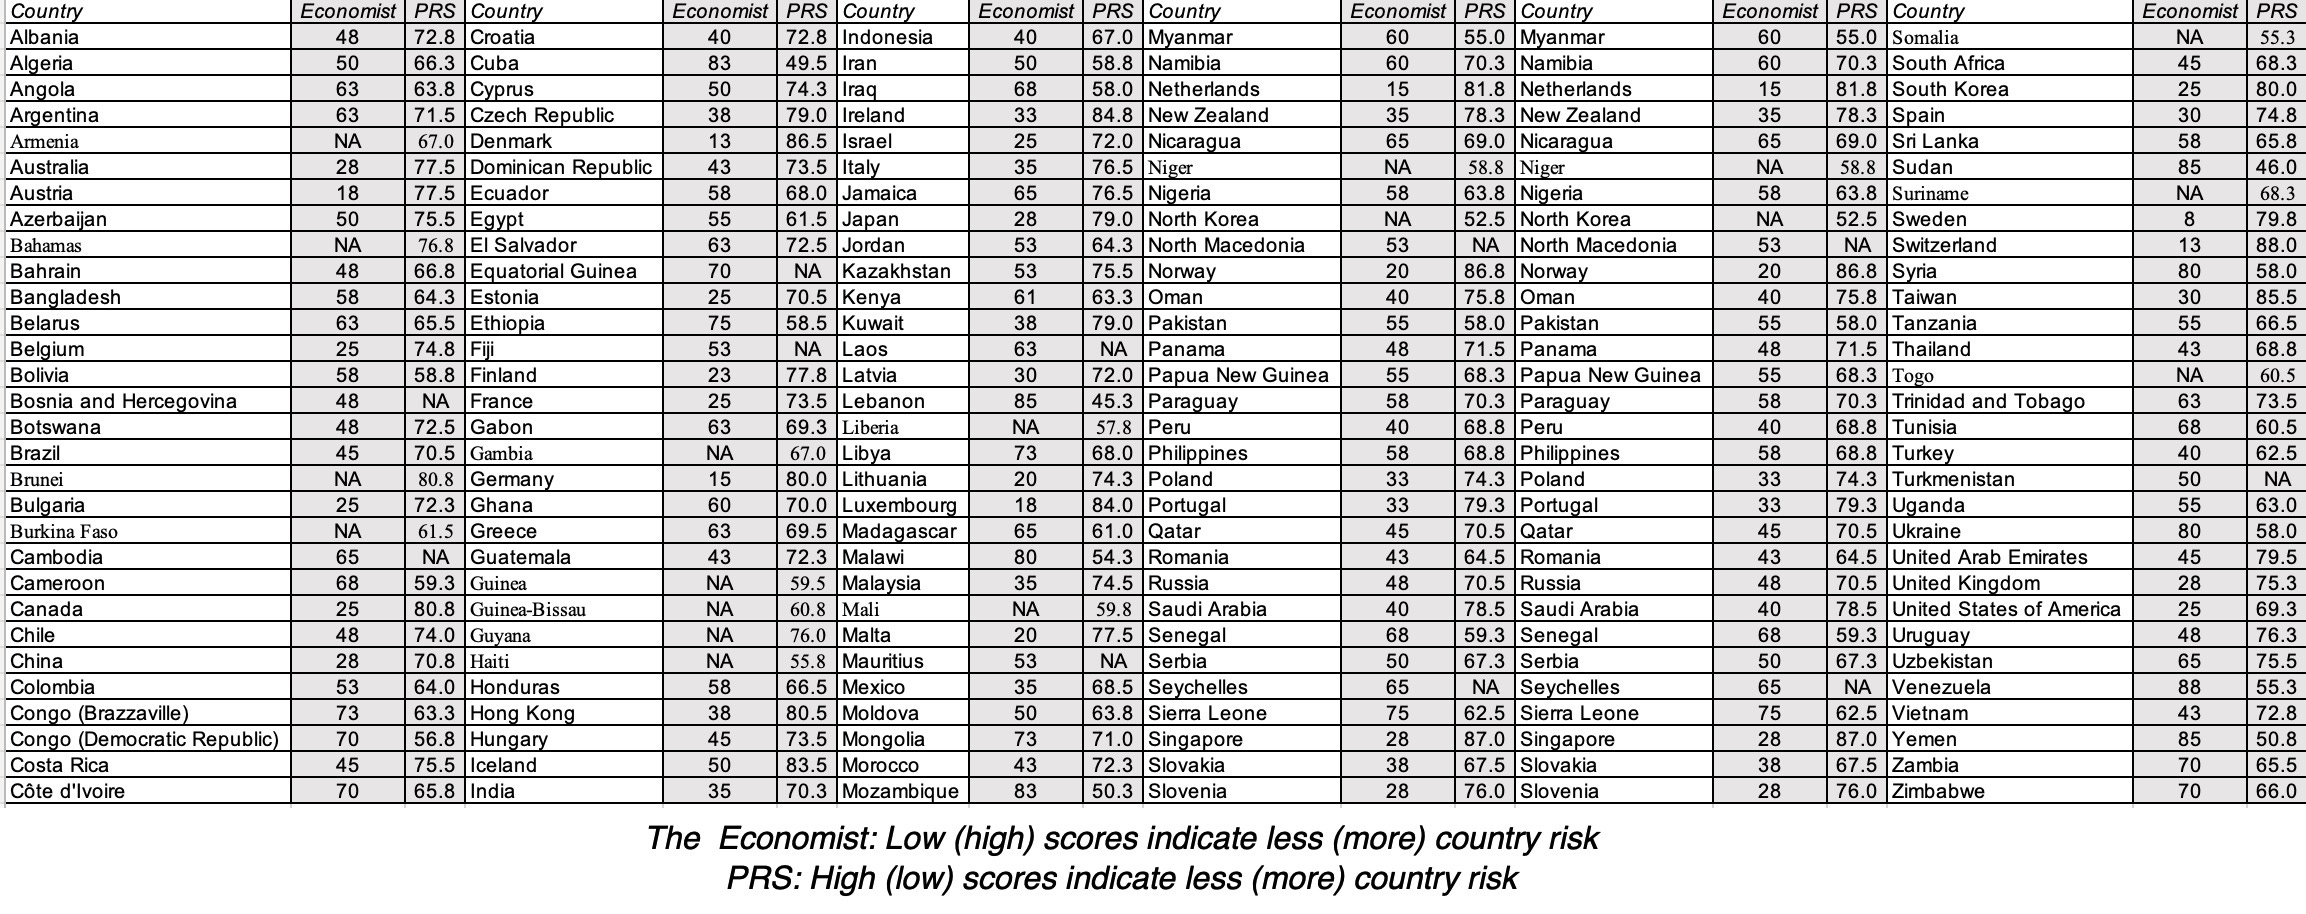
Sources: EIU (Economist) and PRS
The table illustrates three problems that you face with political risk scores. The first is that the scoring is idiosyncratic, with the Economist going from low scores for the safest countries to high scores for the riskiest, and PRS doing the reverse. The second is that each service picks different factors to consider, and different weightings, leading to scoring divergences that sometimes confound; PRS, for instance, ranks the United States as riskier than Ghana, on a composite risk basis. The third is that the scores, by themselves, are difficult to convert into inputs in financial analysis, either in cash flow or discount rate adjustment.
It is to combat the third problem that I started estimating country equity risk premiums, and while the details of the process and the data that I use have changed over the last three decades, the basic structure has remained unchanged. I start with an estimate of the equity risk premium for a mature market, and build a country risk premium, if needed, for riskier countries. Until 2025, I estimated the mature market premium by computing an implied equity risk premium for the S&P 500, and using that as the base, arguing that the US, as a Aaa rated country (at least according to Moody’s), represented a mature market. The Moody’s downgrade for the US, from Aaa to Aa1, has thrown a wrench into that approach, requiring adaptation. In response, I now start with an estimate of the implied ERP for the S&P 500, but then adjust that estimate for the default spread (based on the Aa1 rating) for the US, with the resulting values at the start of July 2026 below:
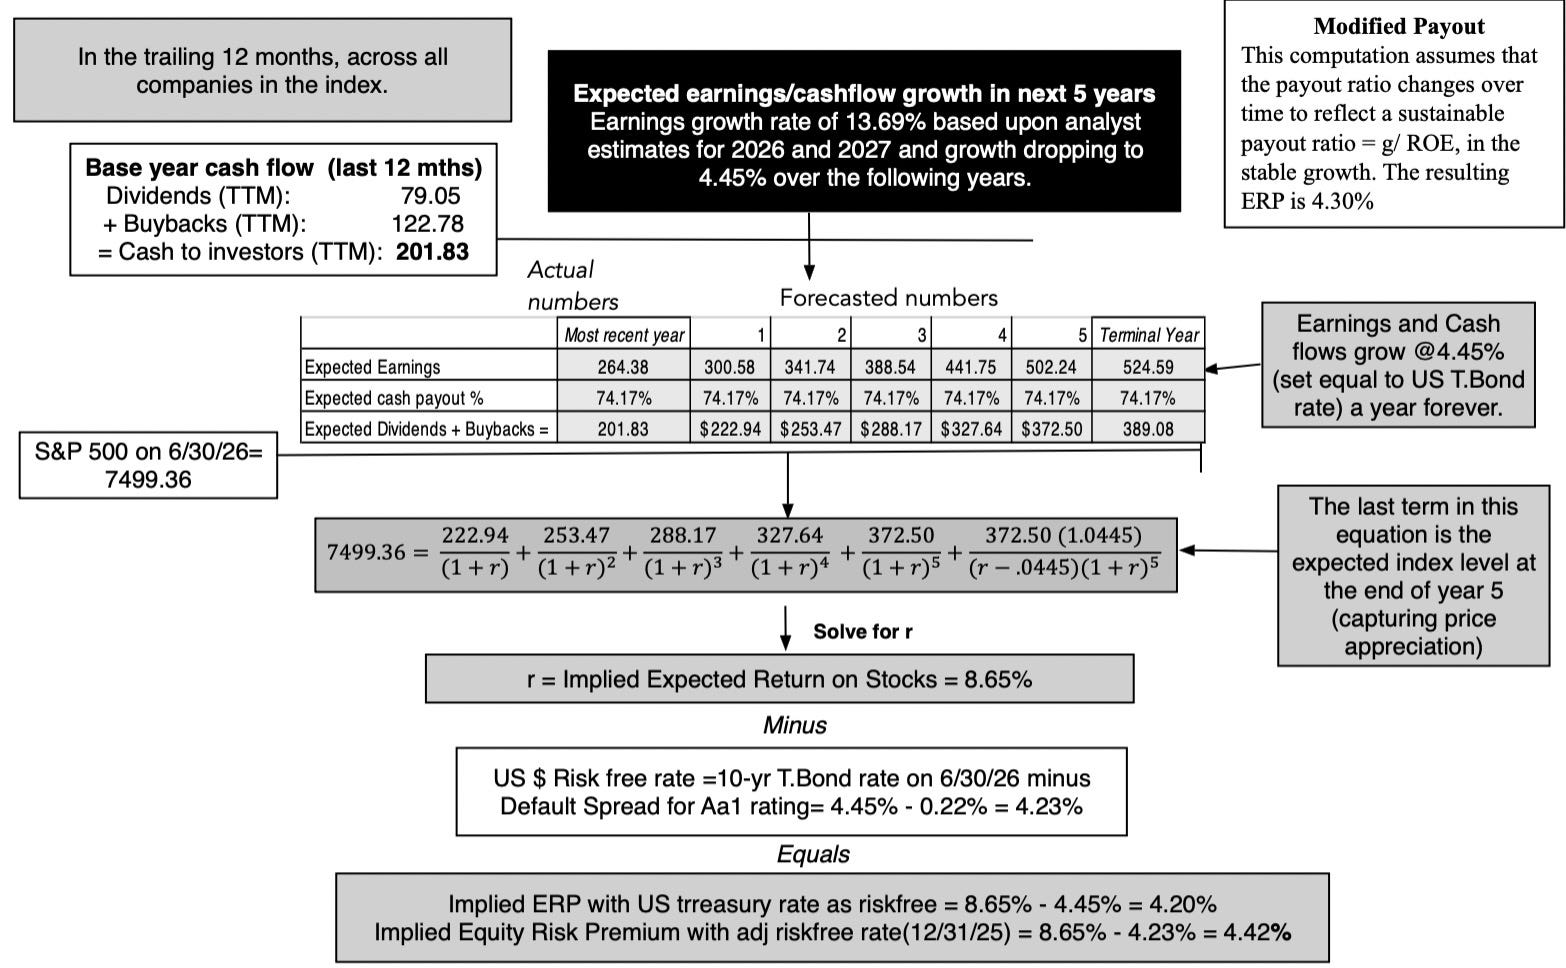
Spreadsheet: https://pages.stern.nyu.edu/~adamodar/pc/implprem/ERPJuly26.xlsx
As you can see, with the S&P 500 at 7499.36 on July 1, 2026, the implied equity risk premium for the United States is 4.42%, and netting out the default spread of 0.22% for the Aa1 rating yields a mature market premium of 4.20%.
To estimate country risk premiums, I start with the sovereign ratings for rated countries and convert those ratings into default spreads. To adjust for the higher risk associated with equities, relative to government bonds, I estimate a composite measure of that relative risk, by scaling the volatility in an emerging market equity index to the volatility in a emerging market government bond ETF, and scale the default risk up with this relative risk measure (1.55 in July 2026) to get country risk premiums:
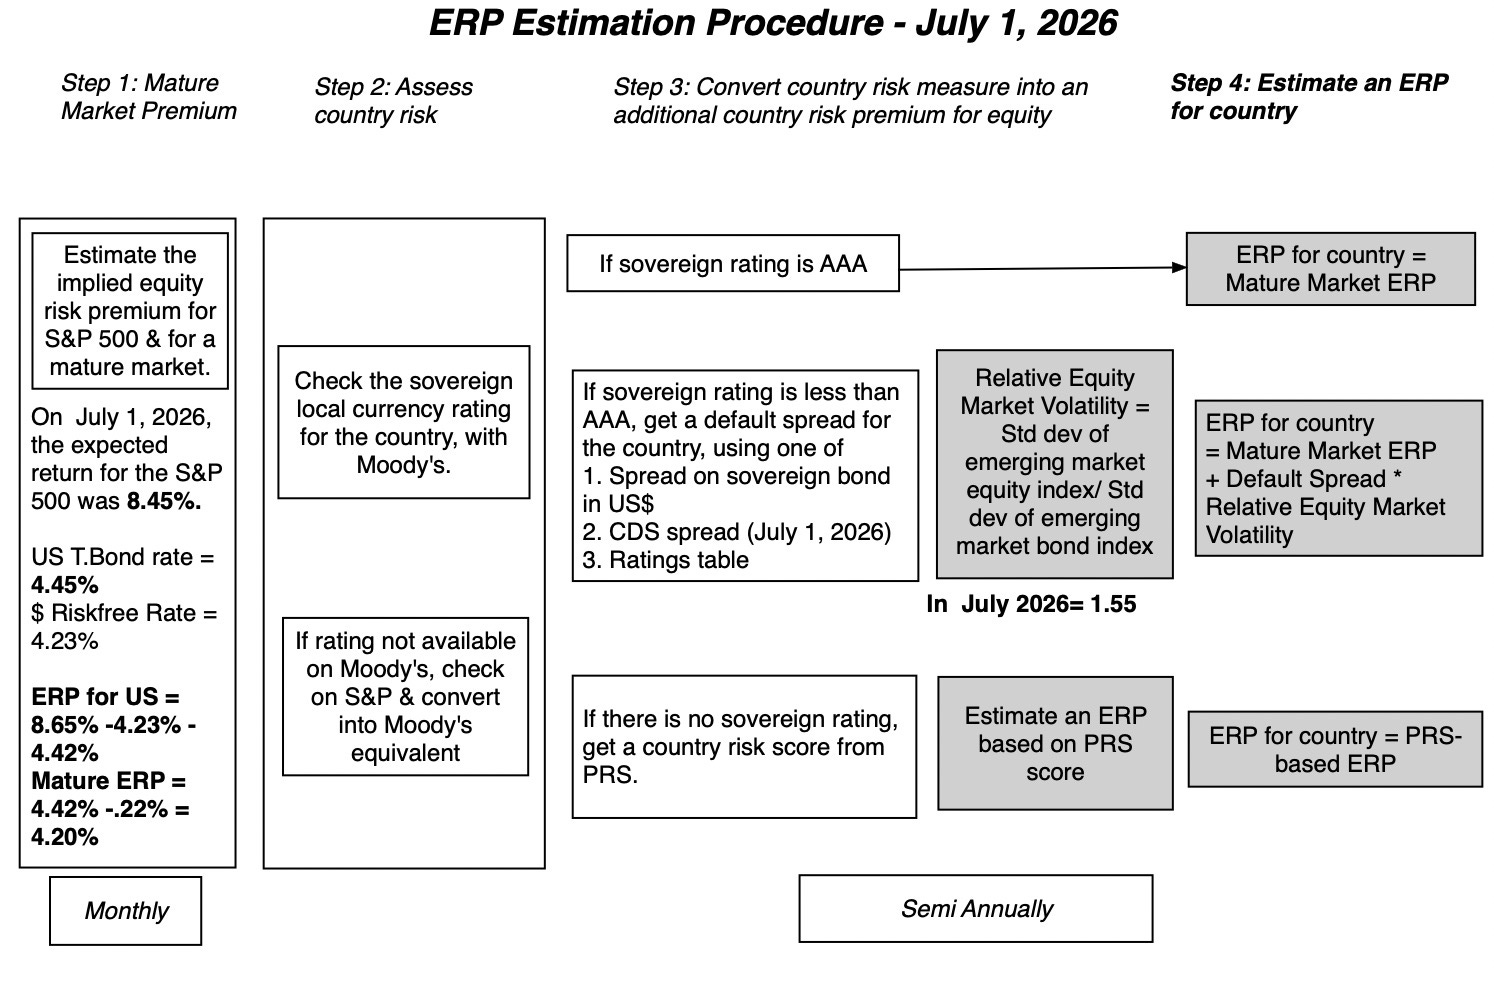
For the two dozen countries that have no sovereign ratings, I adopt an even more makeshift approach, where I used political risk scores for these countries, and then looked for rated countries with similar scores. The table below has equity and country risk premiums, by country, for all of the countries that I evaluated in July 2026:
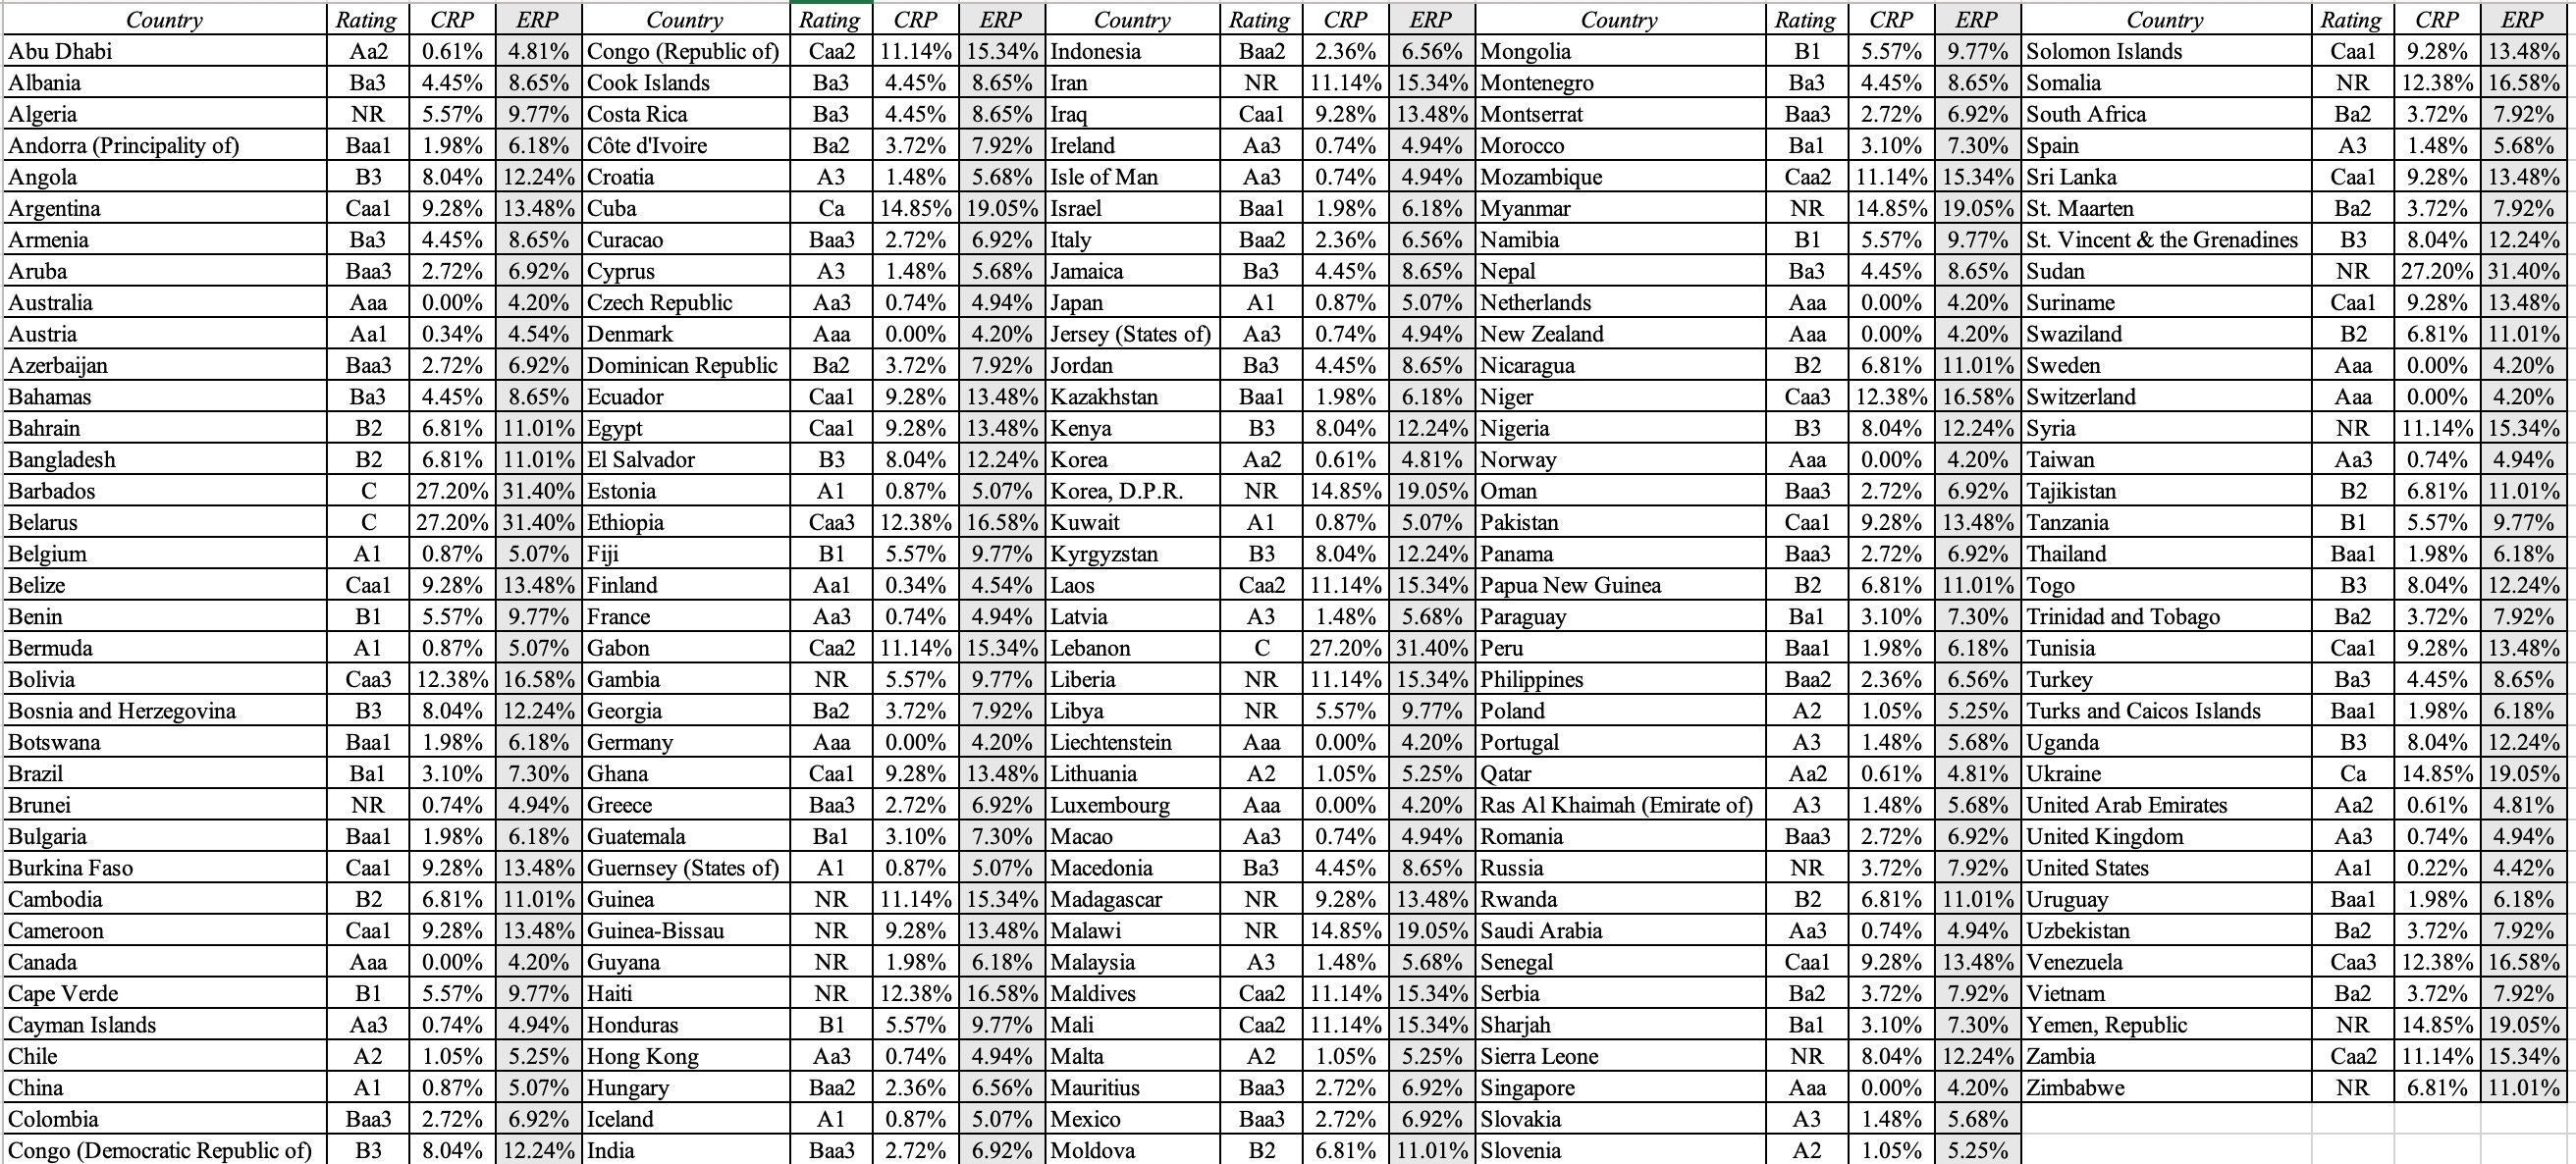
I did post an earlier version of this table a couple of weeks ago, but the numbers that I reported reflected in incomplete update of sovereign default spreads, and this table (and the data on my webpage) now reflect the corrected (and lower) spreads. (As a solo act, I am deeply grateful for the checking that those who use my data do, and thankful when they point out mistakes that I have made.)
Company Exposure to Country Risk
If you buy into my argument that every company has a narrative, and it is the narrative that drives its value, it is worth considering where country risk fits into that narrative. The answer, I believe, comes from looking at where the country in question falls in the life cycle:
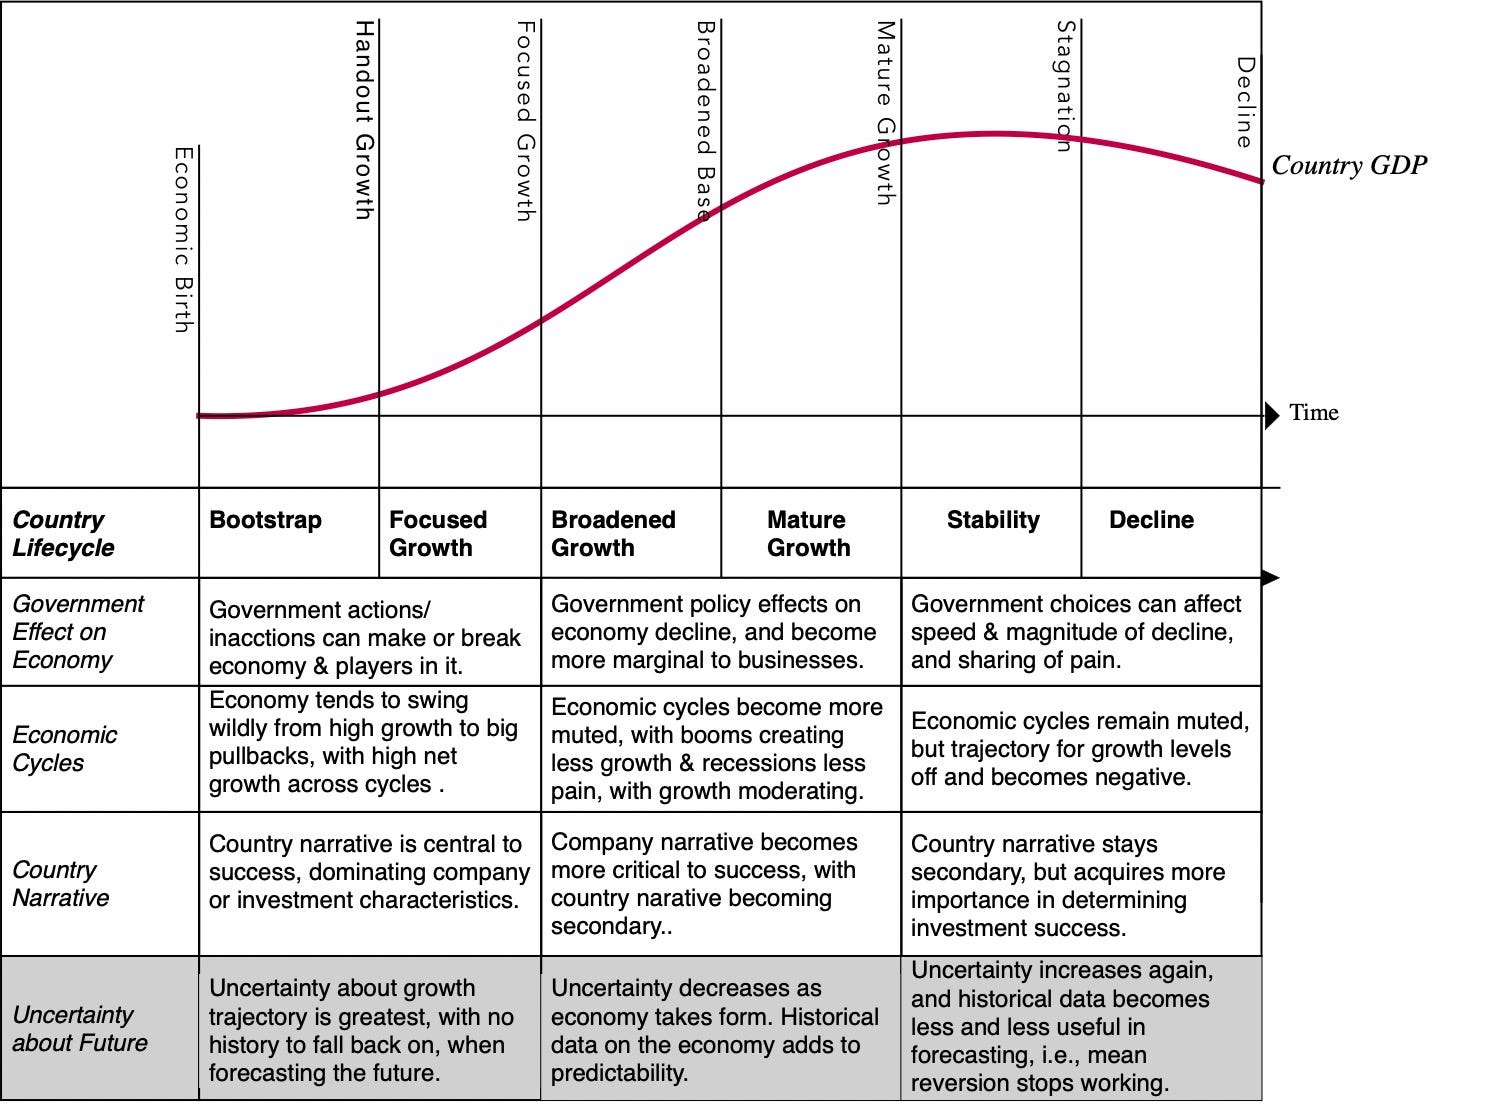
The message from this life cycle view is a sobering one, especially for those analyzing companies that operate in very risky countries, since the narratives for these companies implicitly or explicitly incorporate a country risk component. You cannot value a Venezuelan company without taking a strong view about Venezuela, or even an Indian and Brazilian company without an India or Brazil country story underpinning value. In contrast, you may be able to value US and European companies, without explicitly considering the evolution of country risk in those parts of the world.
When looking at an individual company, I believe that country risk exposure comes less from where the company is incorporated and more from where it operates. It is undeniable that companies around the world have substantial exposure outside their domestic markets, and that exposure has increased over time. In the graph below, I look at the revenue breakdown of companies in four indices - the S&P 500 (US), the FTSE 100 (UK), the Nikkei 225 (Japan) and the Sensex (India):
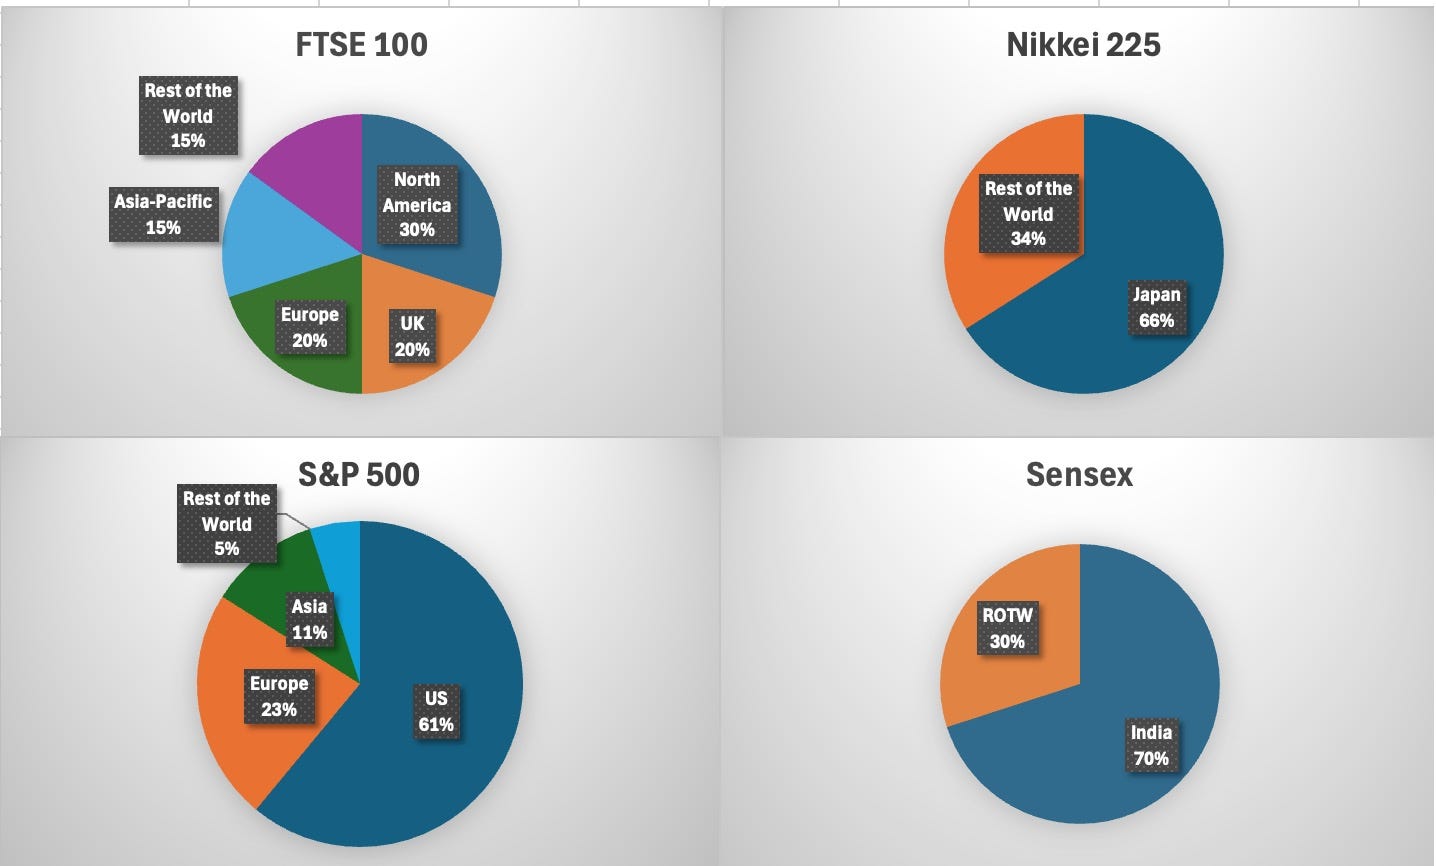
In every single index, companies that comprise that index get a significant portion of their revenues from outside the domestic market. Looking across sectors, exposure to foreign markets varies widely with technology companies often generating more than half of their revenues outside their domestic settings. I believe that equity risk premiums for companies should reflect exposure to foreign markets, though it is worth debating how best to weight that exposure - revenues work well for consumer product and service companies, production works better for natural resource companies and a mix of revenues and production may be the right choice for manufacturing companies:
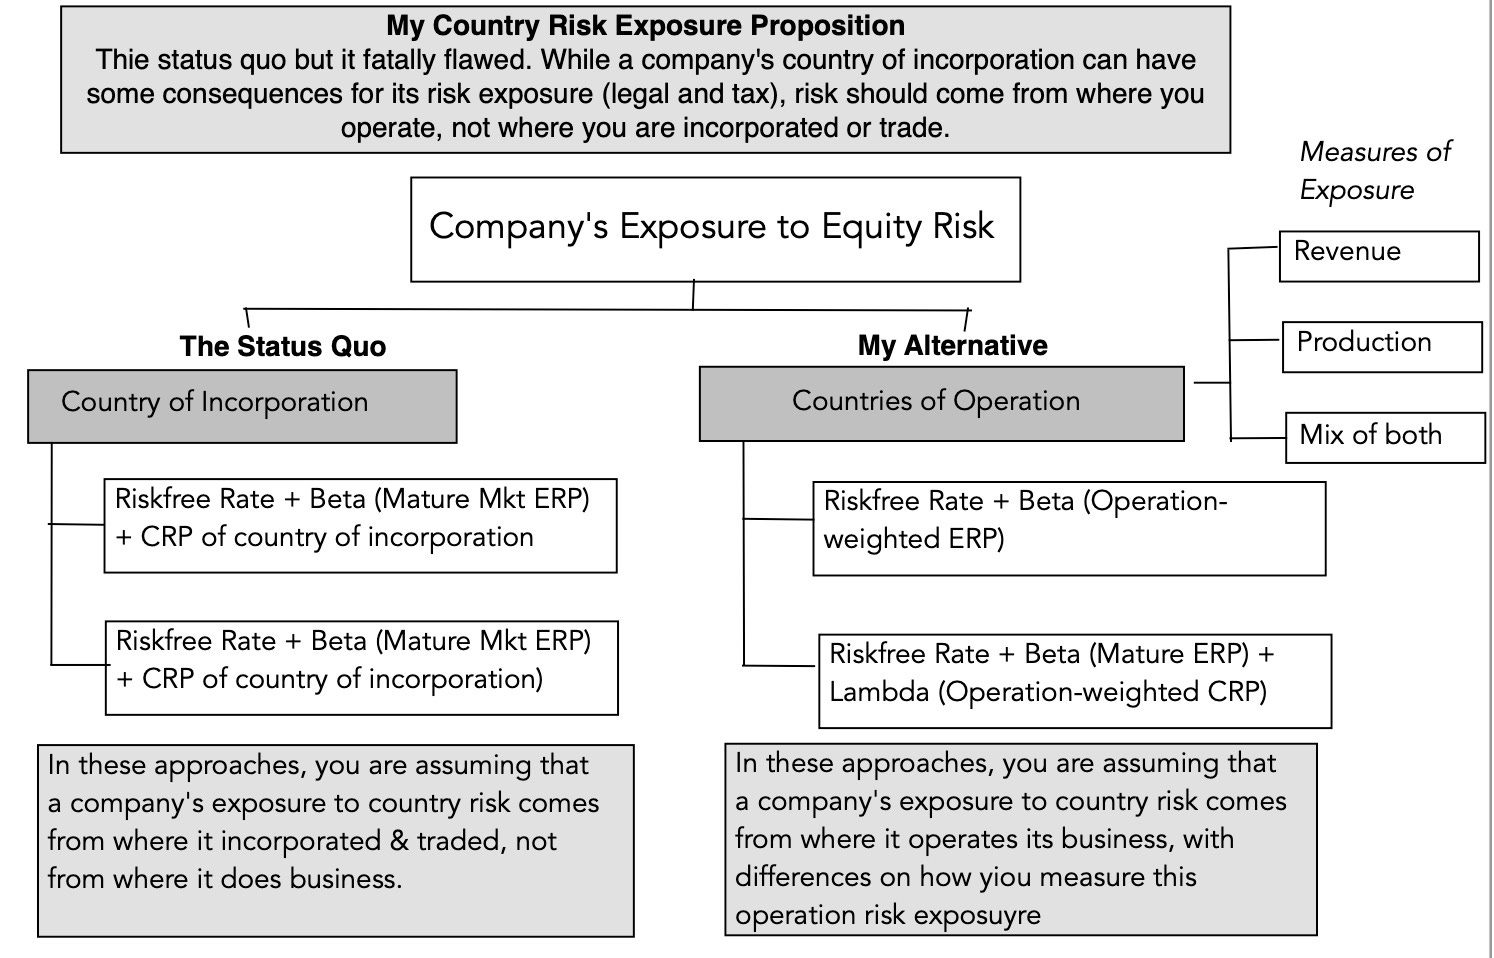
With this framework, you can see why almost all analysts will confront country risk, sooner or later, no matter where they operate in the world and which companies they analyze.
For companies, country risk will also come into play when faced with capital budgeting decisions, where they need estimates of hurdle rates for individual projects, to decide where to invest. For a multinational operating in many businesses, the project cost of equity will have to then also reflect the business the project is in, in addition to country risk. Thus, the cost of equity for a Siemens Appliances for a project in India should reflect the beta for the appliance business, in addition to the country risk for India. In contrast, a Siemens power tool project in Hungary should be computed using the beta for an power tools project and the country risk for Hungary. It is also possible that country risk is not easy to isolate, if the production facilities are in one country but revenues are generated in another. If the Siemens appliance factory in India will be producing products that will be sold in Japan, should we be showing the country risk of India or Japan in the cost of equity calculation? The answer, as was the case in the earlier section on valuation, is that it depends on where the company sees risk coming from. If the risk is that production will be delayed or disrupted by political and economic risk in India, it is Indian country risk that should be looked at, but if the primary concern is that revenues in Japan will be volatile because of economic conditions there, it is Japanese country risk that matters more. If both risks are considerations, you should use a weighted average of Indian and Japanese country risk.
Currency Questions
For some of you, it may seem odd that I have spent almost an entire post talking about country risk without bringing up currencies. The reason is simple. Currencies are measurement mechanisms, and while they may be affected by the same political and economic factors that drive country risk, they don’t determine country risk and in my view, should not command risk premiums, on their own.
It is true that hurdle rates are affected by both the equity risk premiums that you estimate and the riskfree rate that you use, and that riskfree rates vary across currencies. In the figure below, I estimate riskfree rates in about 40 currencies, where a local-currency government bond rate is present, and I adjust that government bond rate for the default risk of the government in question:
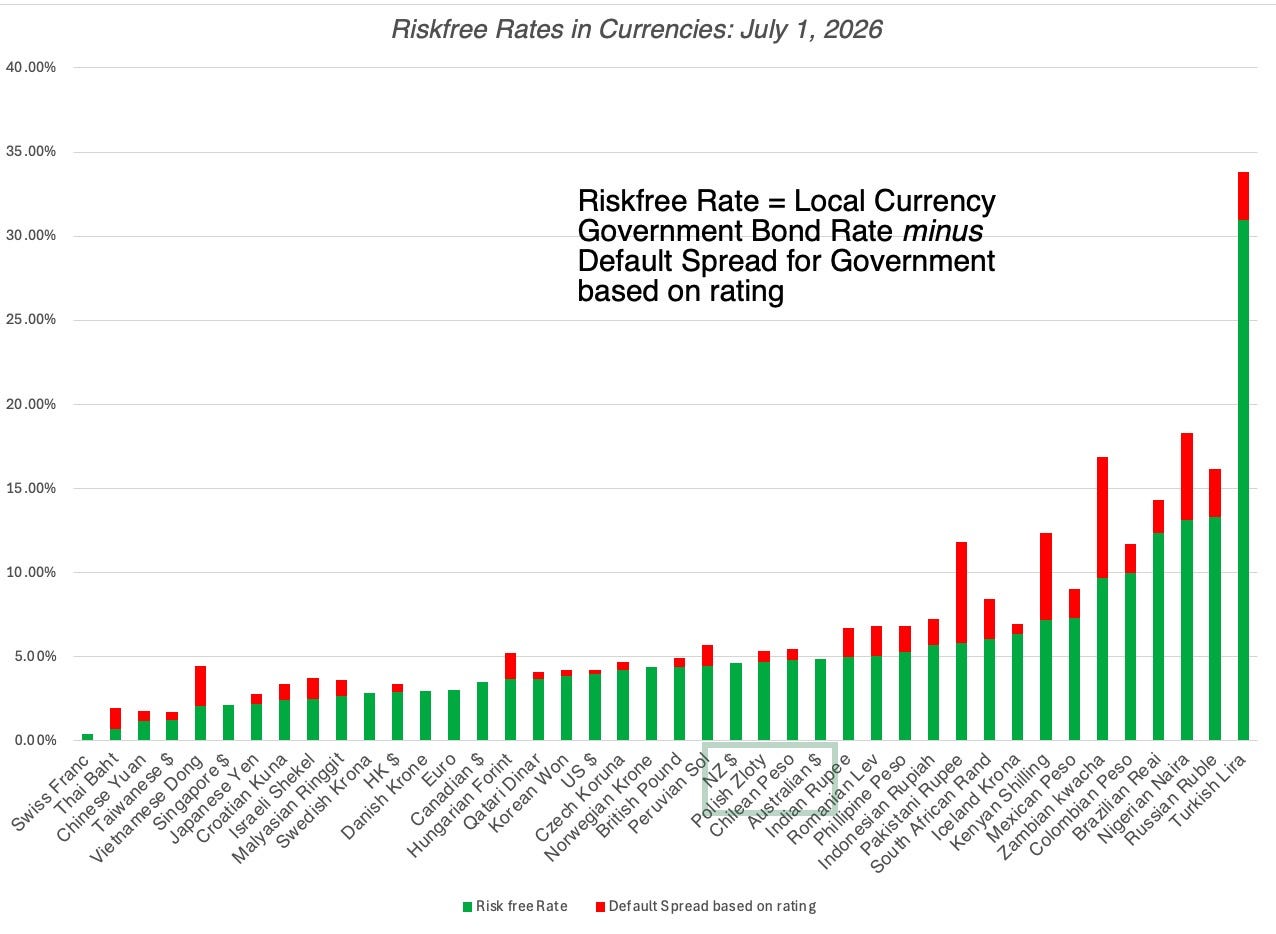
When estimating the cost of equity for a Turkish project or company in Turkish lira, we start with a riskfree rate in excess of 20% and build on it, by adding equity risk premiums to it, but the cost of equity for the same project or company in Euros will begin with a riskfree rate close to 3% (the German Euro bond rate) and arrive at a much lower number. While this may sound farfetched, the value that you derive for the project or company should be the same using either currency, if you are consistent about estimating your cash flows in the same currency:
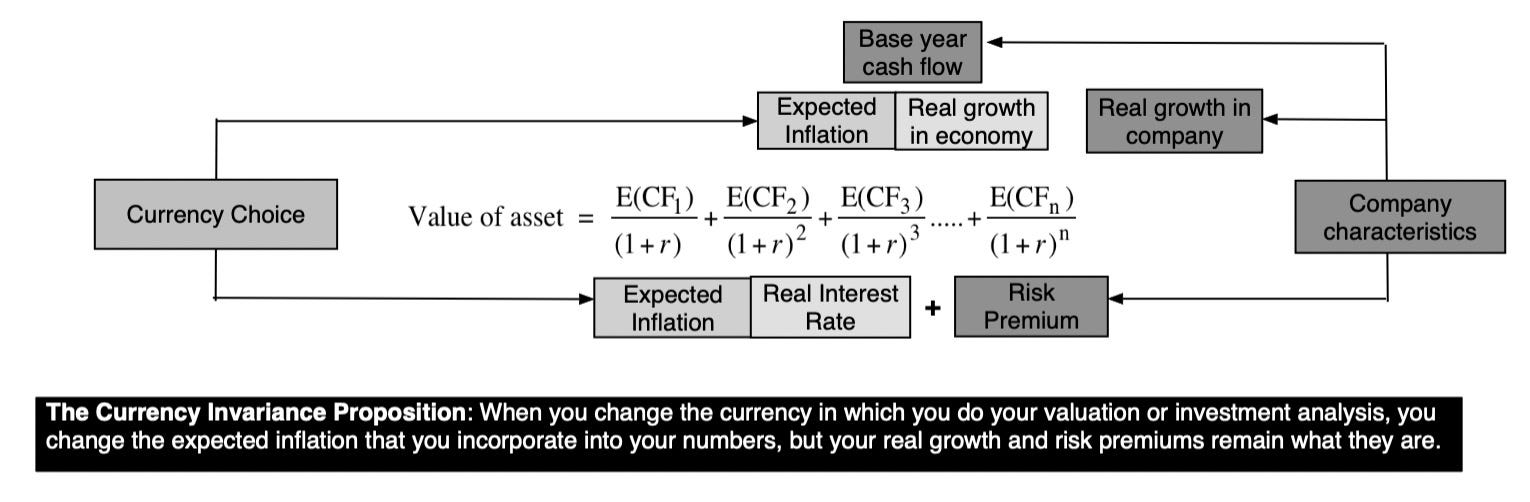
Since much or almost all of the differences in riskfree rates come from inflation differentials, matching the high Turkish lira discount rate with a high growth in cashflows in Turkish lira, and the low Euro discount rate with the low growth in cashflows estimated in Euros will yield results that are consistent.
If you do want to estimate riskfree rates in currencies where there is either no local currency government bond that is traded or where you mistrust the government bond rate, because of light trading or government intervention, the fact that riskfree rate differences across currencies can be tied to differential inflation can be used for estimation; the riskfree rate in any currency can be computed from a base currency (dollar or Euro) riskfree rate and the difference in expected inflation between the local and base currencies:
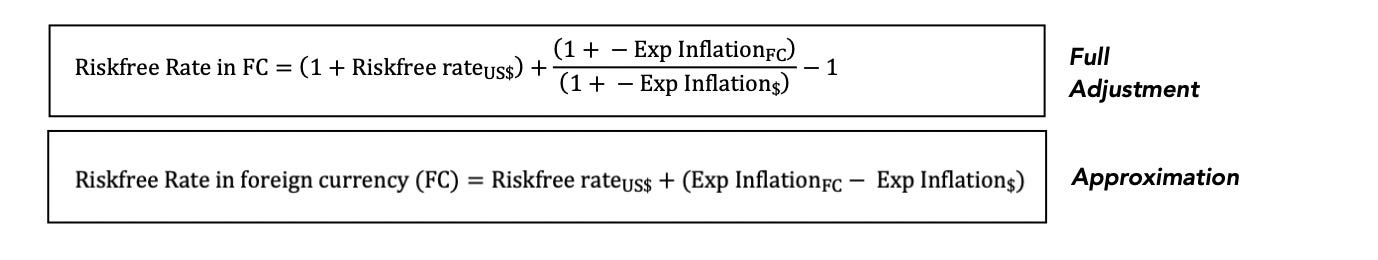
Put simply, if the expected inflation rate and riskfree rate in US dollars are 2.5% and 4% respectively, and the expected inflation rate in Brazil is 10.5%, the riskfree rate in Brazilian reais should be roughly 12%. The implication of this approach is that currency pegs, when they do exist, will hold only if the inflation in the pegged currency matches or is close to the inflation in the index currency to which it is pegged. It is true that the estimates of riskfree rates will only be as good as the expected inflation rates that are embedded in the estimation, but the good news is that being wrong on expected inflation will be largely offsetting, since both your cashflows and your discount rates will be wrong in the same direction; if you underestimate expected inflation, you will underestimate (overestimate) your riskfree and hurdle rates, but you will also underestimate (overestimate) your expected growth rate in cash flows.
Conclusion
One of the side effects of the rise of globalization is that there are fewer and fewer companies that are entirely local-country focused in both their revenues and production, and as a result, almost every business and investor is exposed to risk in other parts of the world. The problem with measuring country risk is that while its consequences are economic, it has its sources in history, politics and governance structures. The measures of country risk, whether they be entity-based like sovereign ratings, or market estimates like sovereign CDS spreads, reflect this interplay.
I confess that I have made simplistic assumptions and cut corners in my attempt to estimate equity risk premiums, by country, and there will be individual countries, perhaps even your own, where you might disagree with my assessments. As I noted earlier, my estimation approach remains a work-in-progress and I am always open to suggestions on how to estimate these premiums better, but keep in mind that whatever those improvements may be, they will have to work across 180 countries.
YouTube Video
Papers on country risk and equity risk premiums
Data
Implied Equity Risk Premiums for the S&P 500 (Annual since 1960 & Monthly since Sept 08)
Spreadsheet
Professor Damodaran,
Thank you for another thoughtful paper. Having spent nearly three decades investing across emerging and frontier markets, I found it both rigorous and immensely practical.
Reading it, however, left me wondering whether sovereign analysis is approaching the same inflection point that corporate valuation experienced several decades ago.
Corporate valuation gradually evolved from focusing primarily on tangible assets toward recognizing that much of a firm's value resides in intangible assets—brand, talent, intellectual property, organizational culture and networks. I wonder whether sovereign analysis now faces a similar evolution.
Most country-risk frameworks ultimately ask one question:
How risky is this country today?
That is exactly the question lenders and fixed-income investors need answered.
Long-term equity investors, however, are often asking something different:
What is the probability that this country becomes materially better—or materially worse—than today's measures imply?
Those are related questions, but they are not the same.
The greatest investment opportunities I have encountered rarely emerged because a country became objectively "safe." They emerged because its trajectory changed before conventional measures recognized it. Vietnam illustrates this well. Twenty-five years ago it was unquestionably high risk, but the more important story was that its institutions, policies and global integration were steadily improving. Investors who focused only on the level of risk missed the direction of change.
That experience has led me to wonder whether sovereign analysis should distinguish more explicitly between the level of risk and the trajectory of risk.
More broadly, traditional frameworks seem naturally organized around downside—default, inflation, corruption, conflict and political instability. They measure these exceptionally well. But countries also possess upside. Those beginning from very low expectations often have the greatest convexity, where relatively modest improvements in governance, credibility or connectedness can produce disproportionate increases in equity values and private investment. Fixed-income investors primarily participate in the reduction of downside; equity investors participate in the creation of upside.
Perhaps the biggest omission, however, is that countries are still analyzed largely through their liabilities rather than their assets. We carefully measure debt, deficits and reserves, yet devote far less attention to intangible national capital: institutional competence, legitimacy, policy credibility, connectedness, human capital and, perhaps most importantly, the capacity to adapt. Singapore's long-term success is difficult to explain without these assets, just as Iran's unrealized potential is difficult to understand without considering the costs of prolonged isolation.
Finally, I wonder whether countries behave less like balance sheets and more like living systems. Institutional quality, legitimacy, confidence and capital flows reinforce one another through powerful feedback loops. Lebanon's collapse illustrates how quickly negative loops can accelerate. Successful reform stories demonstrate that positive loops can compound just as powerfully.
None of this diminishes the importance of your framework. On the contrary, I think it answers one question exceptionally well.
I simply wonder whether long-term investors increasingly need a complementary framework that asks a different one:
Not simply, "What is the probability this country defaults?"
But, "What is the probability this country adapts?"
I think for the corruption article, you meant lower scores mean higher corruption.