
Markets play an expectations game, and in March 2026, we saw the process play out, with all of its upsides and downsides. The month started with a war in the Middle East, which quickly percolated into soaring oil prices and dropping stock prices, but the overwhelming factor was uncertainty about almost every dimension of the war - how long it would last, what permanent changes to oil prices would emerge as a consequence and how global governments and economies would respond to these changes. As we reach the end of the month, rather than getting answers, we face more questions, and not surprisingly, markets are volatile, not just on a day-to-day basis, but in intraday trading, driven as much by rumors and conjecture, as by facts. In keeping with my view that it is during periods of maximal uncertainty that you need perspective and to back to basics, I will focus my attention on market behavior in March, and what we can learn from that behavior, as a precursor for the months to come.
The Market Narrative in March
We live in an age of commentary, as self-proclaimed experts offer prognostications, half-baked or otherwise, about what is to come, and the Iran war, with its mix of politics, economics and religion baked in,, has drawn a large and extremely diverse set of expert forecasts. Given the strong priors (about Iran and Trump) that many of these experts bring to the game, it should not be surprising that their views about how the war will play out and the effect on markets is driven by those priors. It is up to markets to reconcile these contradictory perspectives, and come to consensus, and I will try to extract from market behavior what the market narrative is, leading into April 2026, with the recognition that it could be wrong and change overnight in good and bad ways. That said, over the last decade, I have learned that the market is far better at making sense of complexity and uncertainty than experts are, and it behooves us therefore to listen to what it is saying.
The Oil Price Shock
As with almost every event in the middle east, the effects of the Iran War played out first in oil prices, and oil has been the lead player in March, surging and volatile, but with disparate impacts even within that market. In the graph below, I look at spot prices on Brent Crude and West Texas Intermediate (WTI) during March:
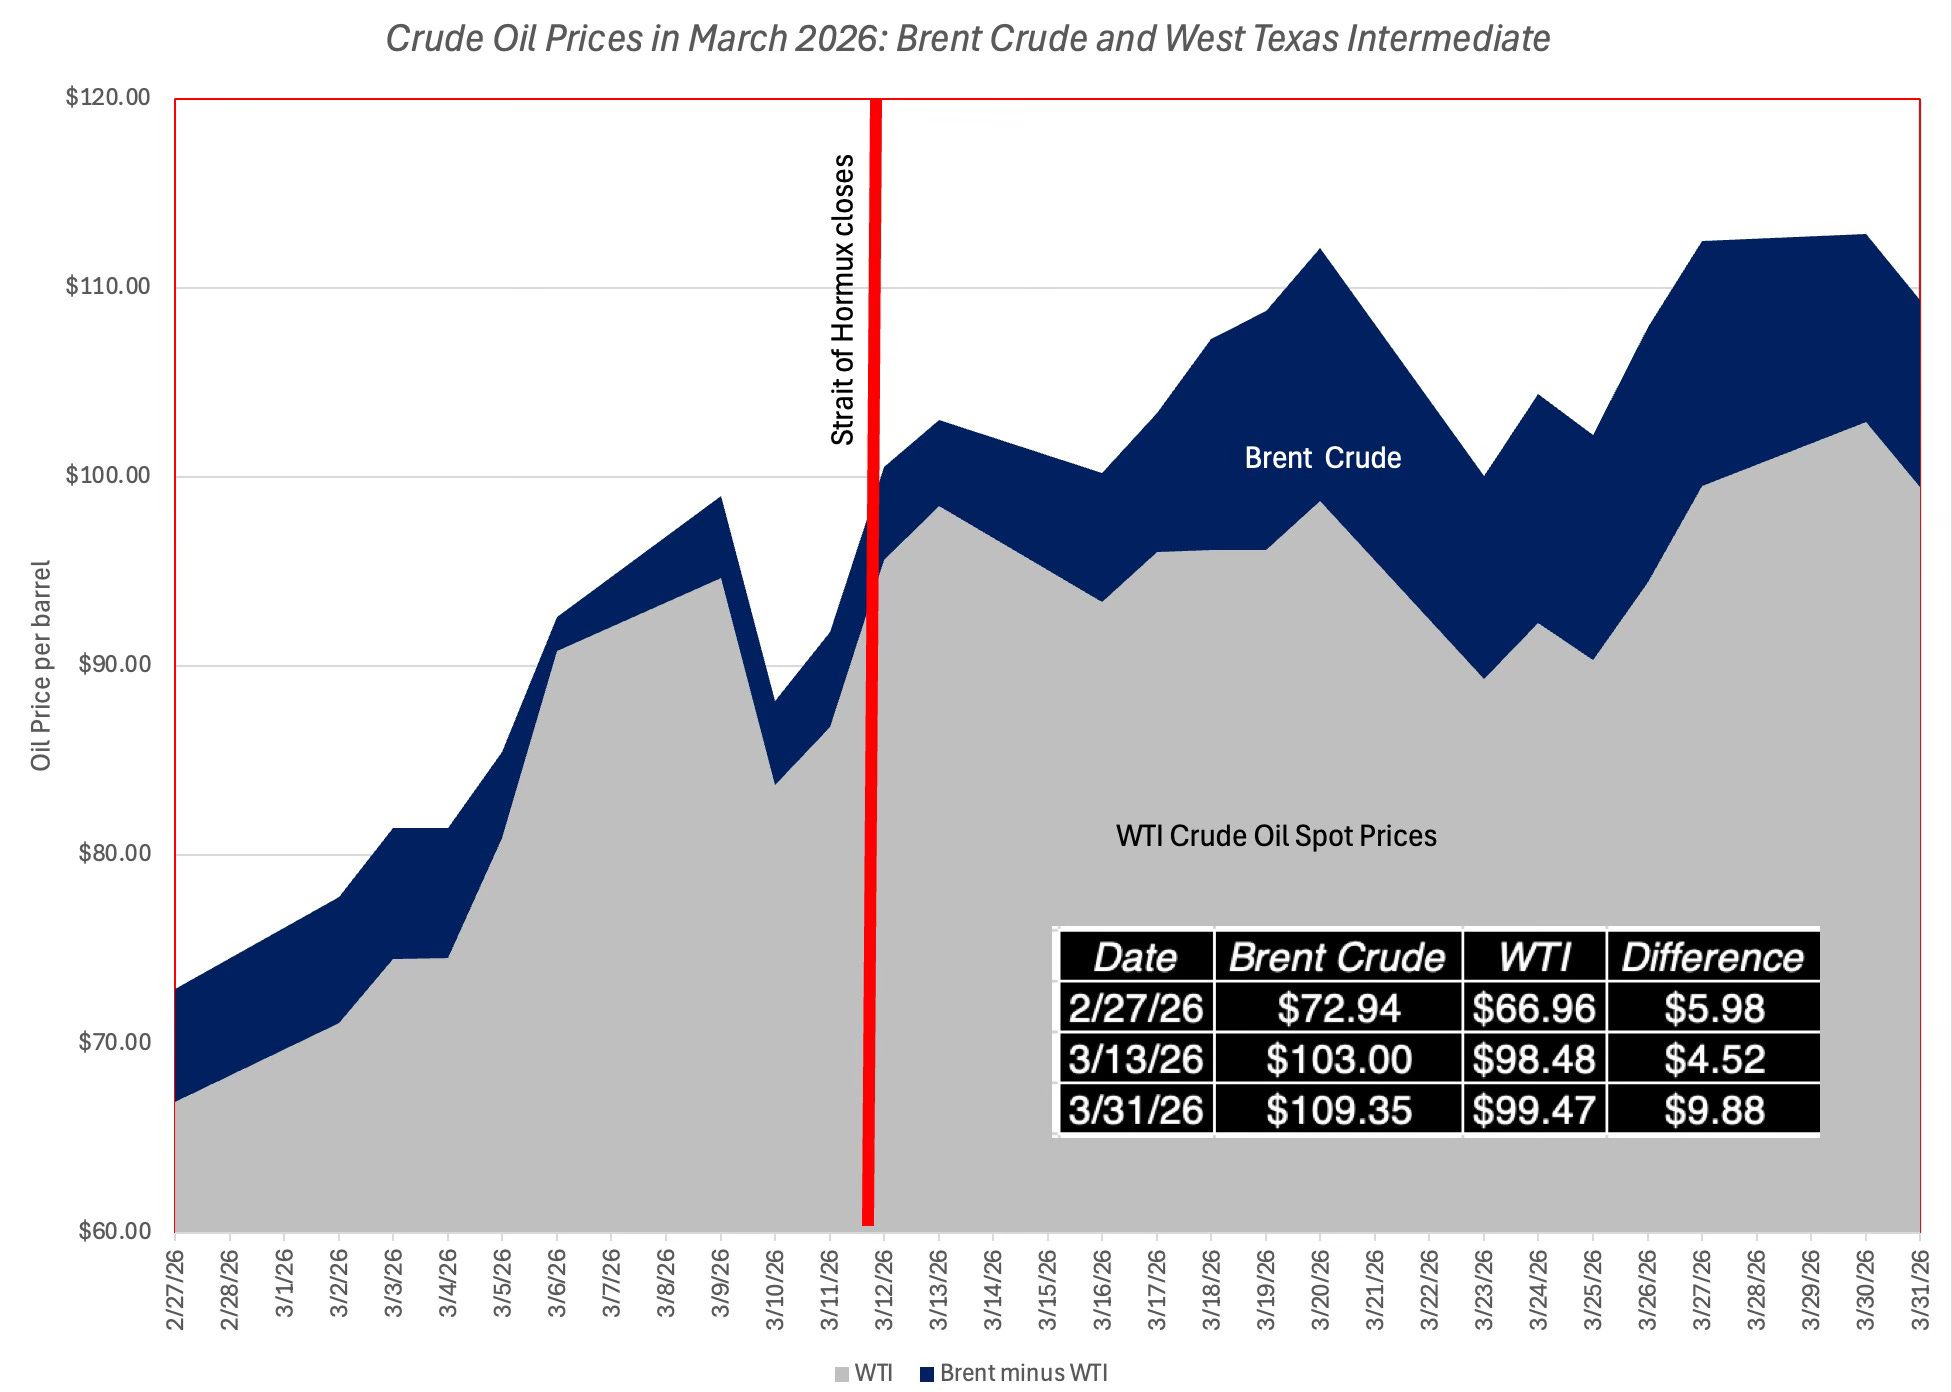
Both Brent and WTI crude oil saw prices increase in March, but with the price of Brent rising 49.9% and WTI rising 48.6% during March, the difference between the two almost doubled during the second half of the month. That divergence reflects the two-fold effect of the war on oil supply, with the first being the shuttering of oil production in the Gulf States and the second being the effecting throttling of ship traffic through the Strait of Hormuz, a key passageway for Middle Eastern oil to Asia and Europe. While both factors push up oil prices, oil and gas production in the US, the largest oil producer in 2025 (producing 13.58 million barrels or 16% of the total), was less affected by the Hormuz closing and supply chain issues, explaining the increasing price divergence mid-month.
There was another tea leaf to read, and it came from watching oil futures prices. In the graph below, I compare the spot prices to Brent crude to June and December futures contracts prices:
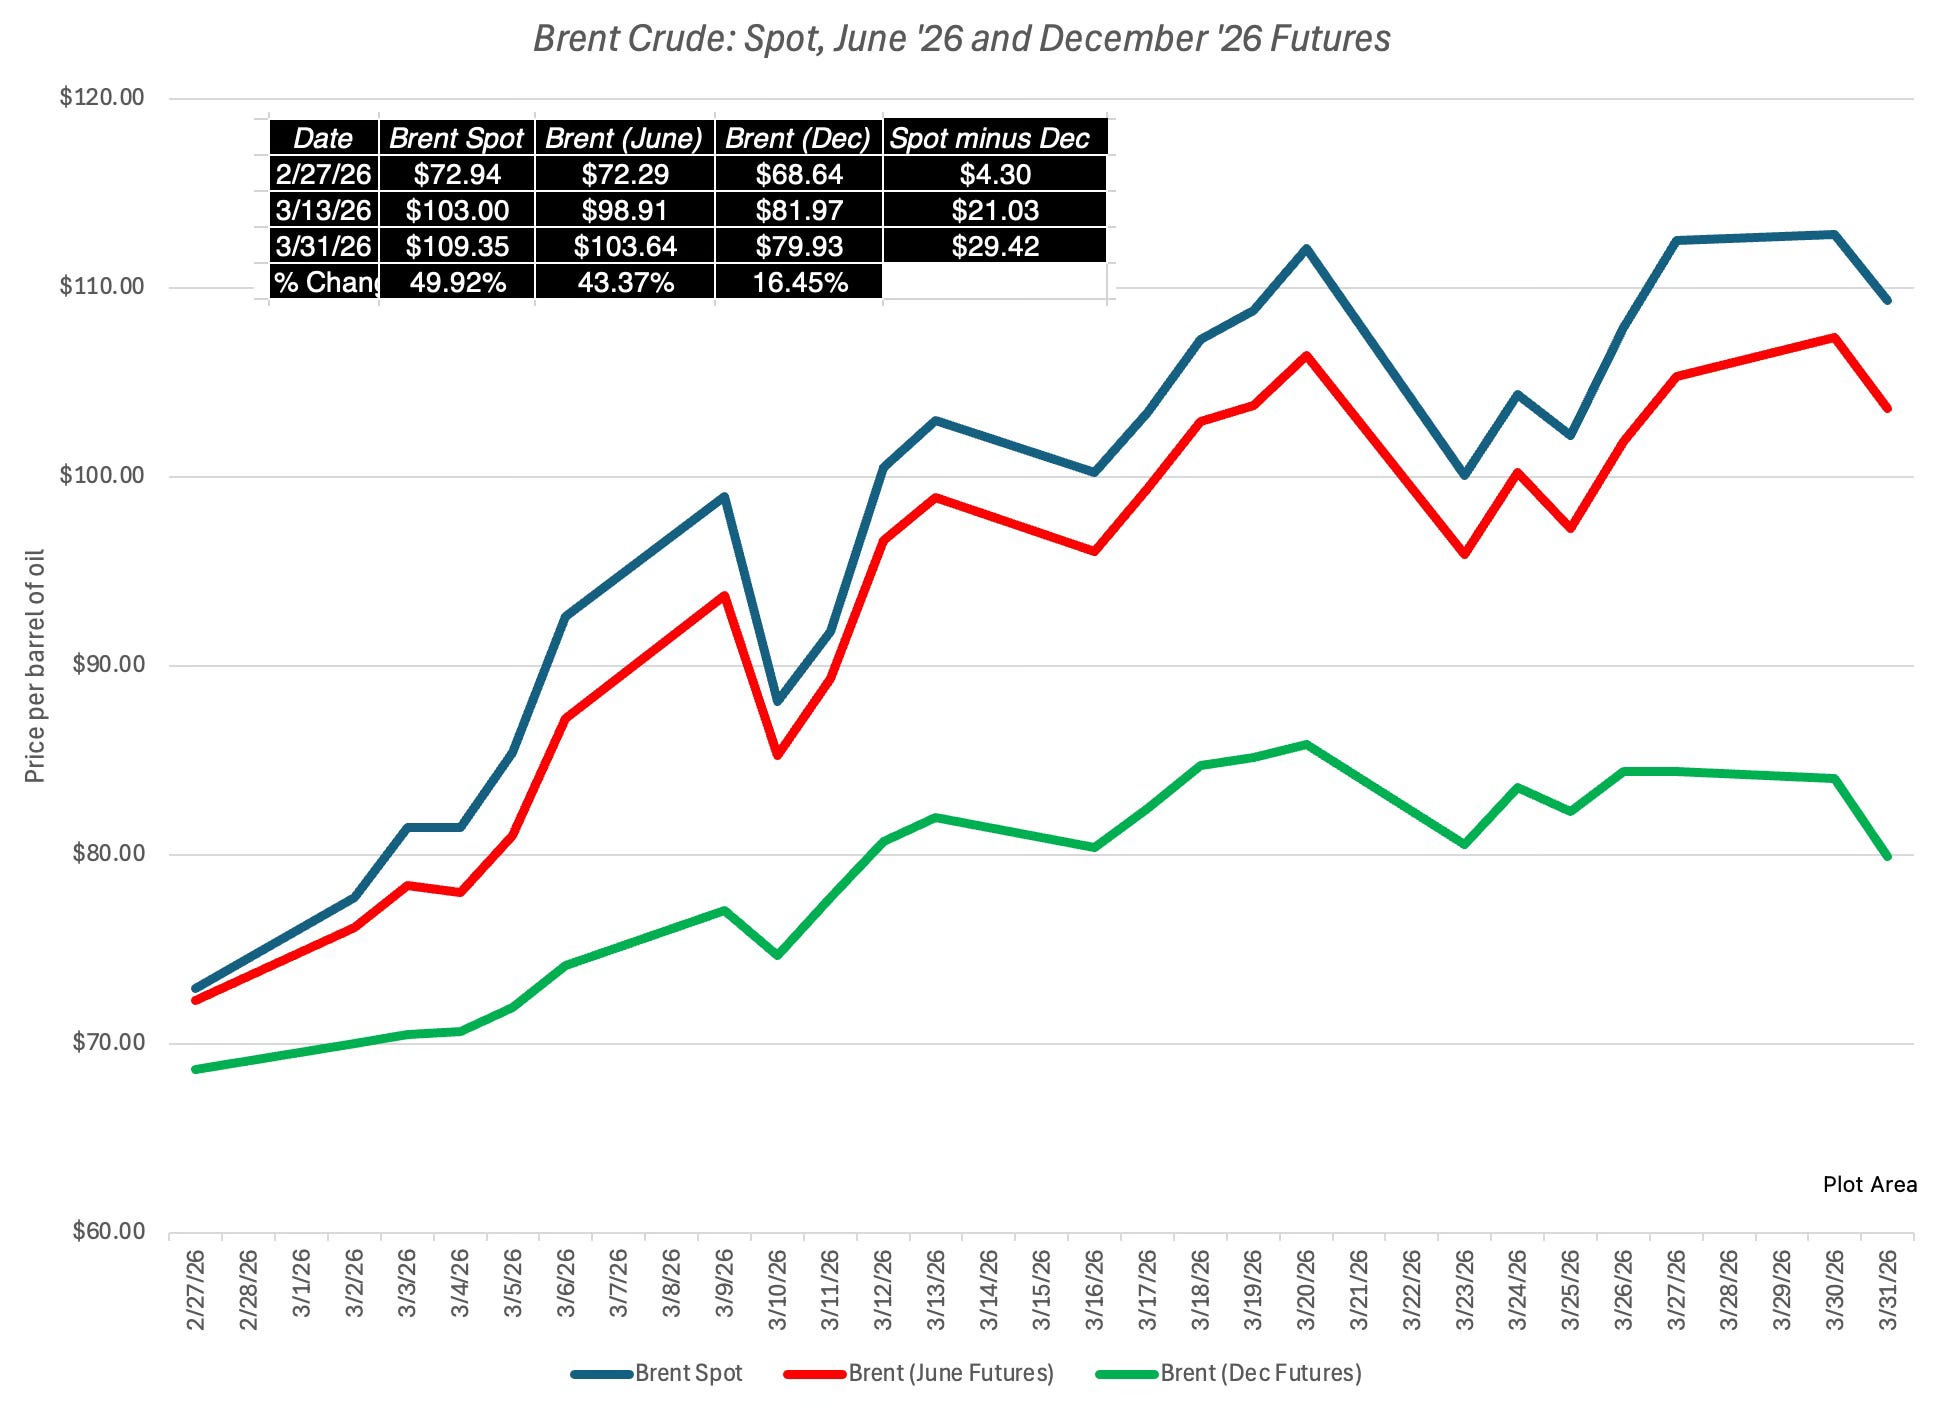
While spot and futures prices have both risen in March, the latter have gone up less, indicating that, at least for the moment, the market sees the interruptions in oil supply as more temporary than permanent, though the market does see a lasting impact even in that optimistic scenario, with December futures up almost 25% over the pre-war level.
Inflation, Interest Rates and the Economy
The creation of OPEC and the oil price embargo in the 1970s and the subsequent inflation spiral in the 1970s is now part of market legend, and the interlude in 2022, when the Russian invasion of Ukraine, and the subsequent sanctioning of Russian oil, caused a spike in inflation rates, has made investors wary. While the effects on gasoline prices are in the news, it is one item in the inflation basket, and it is unclear still how much higher oil prices will affect inflation for the rest of the year and perhaps into next year. While we wait for the actual inflation numbers to come out, markets don’t have that luxury and the early and perhaps best indicator of market expectations on inflation are showing up in interest rates. The graph below looks at 3-month and 10-year US treasuries over the course of March 2026:
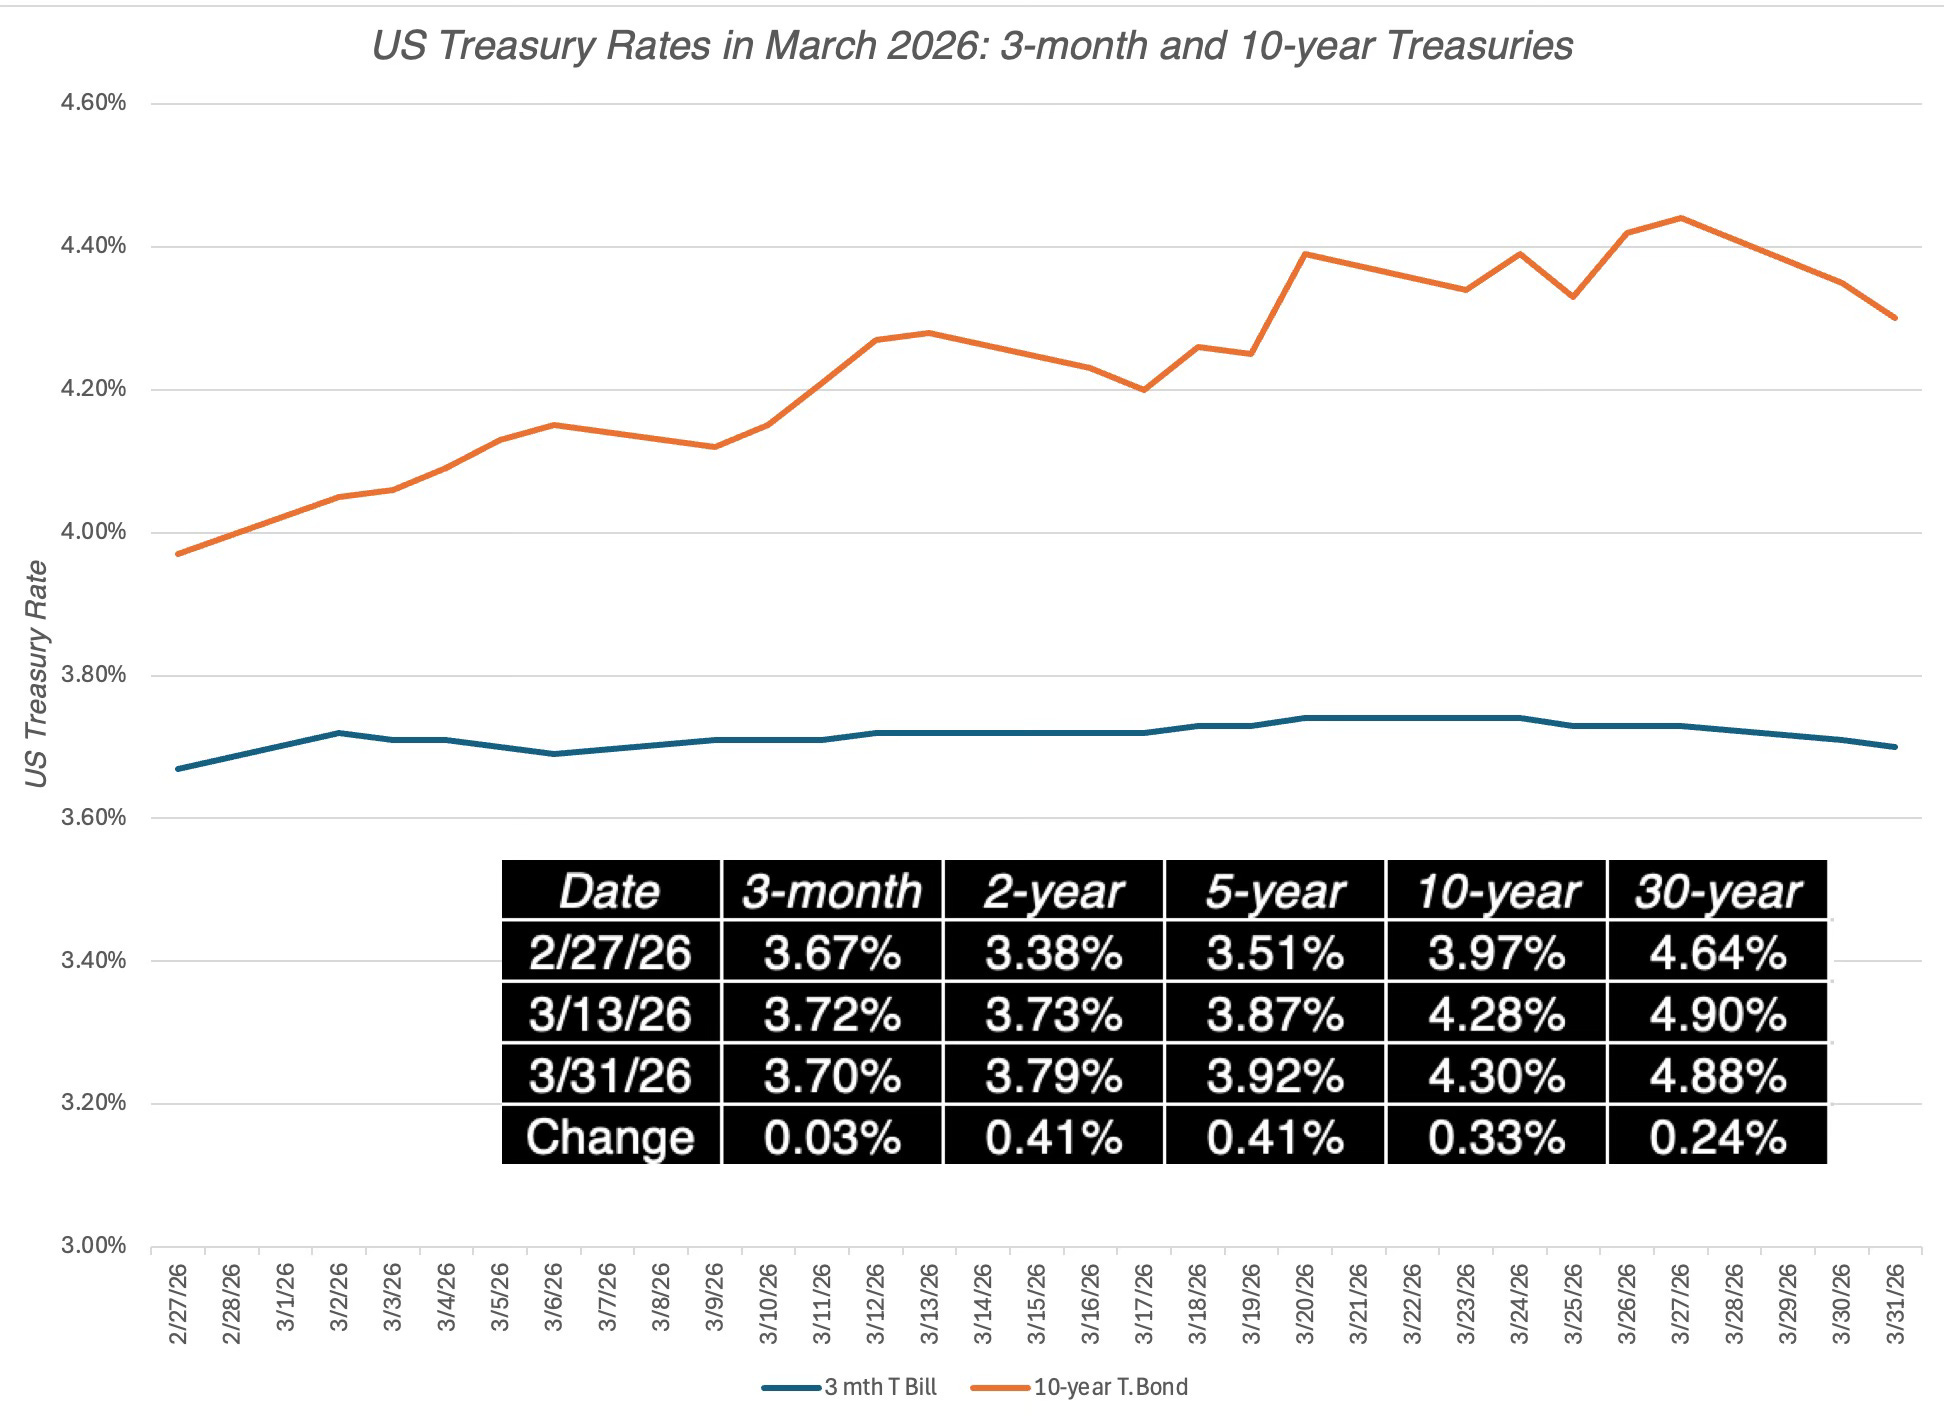
The 3-month treasury bill rate has barely budged over the month, moving from 3.67% on February 27, 2026 to 3.70% on March 31, 2026, but the ten-year bond rate saw a much bigger increase from 3.97% on February 27, 2026, to 4.30% on March 31, 2026. The biggest increases in rates are in the intermediate maturities, with the 2-year and 5-year rates rising by 0.41% over the course of the month. If you view interest rates, as I do, as driven by expected inflation and expected real growth, the most plausible reading is that the market sees an increase in inflation that is persistent. If you are a Fed-watcher, though, your reading may be that the rise in oil prices has tied the hands of the Fed, lowering the likelihood that the Fed Funds rate will be cut in the coming months, but that would leave you with a puzzle to resolve. Since the Fed Funds rate, an overnight bank borrowing rate, has its biggest impact on the short end of the maturity spectrum, how do you explain the fact that short term rates have not changed much?
The increase in interest rates is not just specific to the US, with rises in rates across other currencies, as you can see in this graph of ten-year Euro, Yen and Yuan rates:
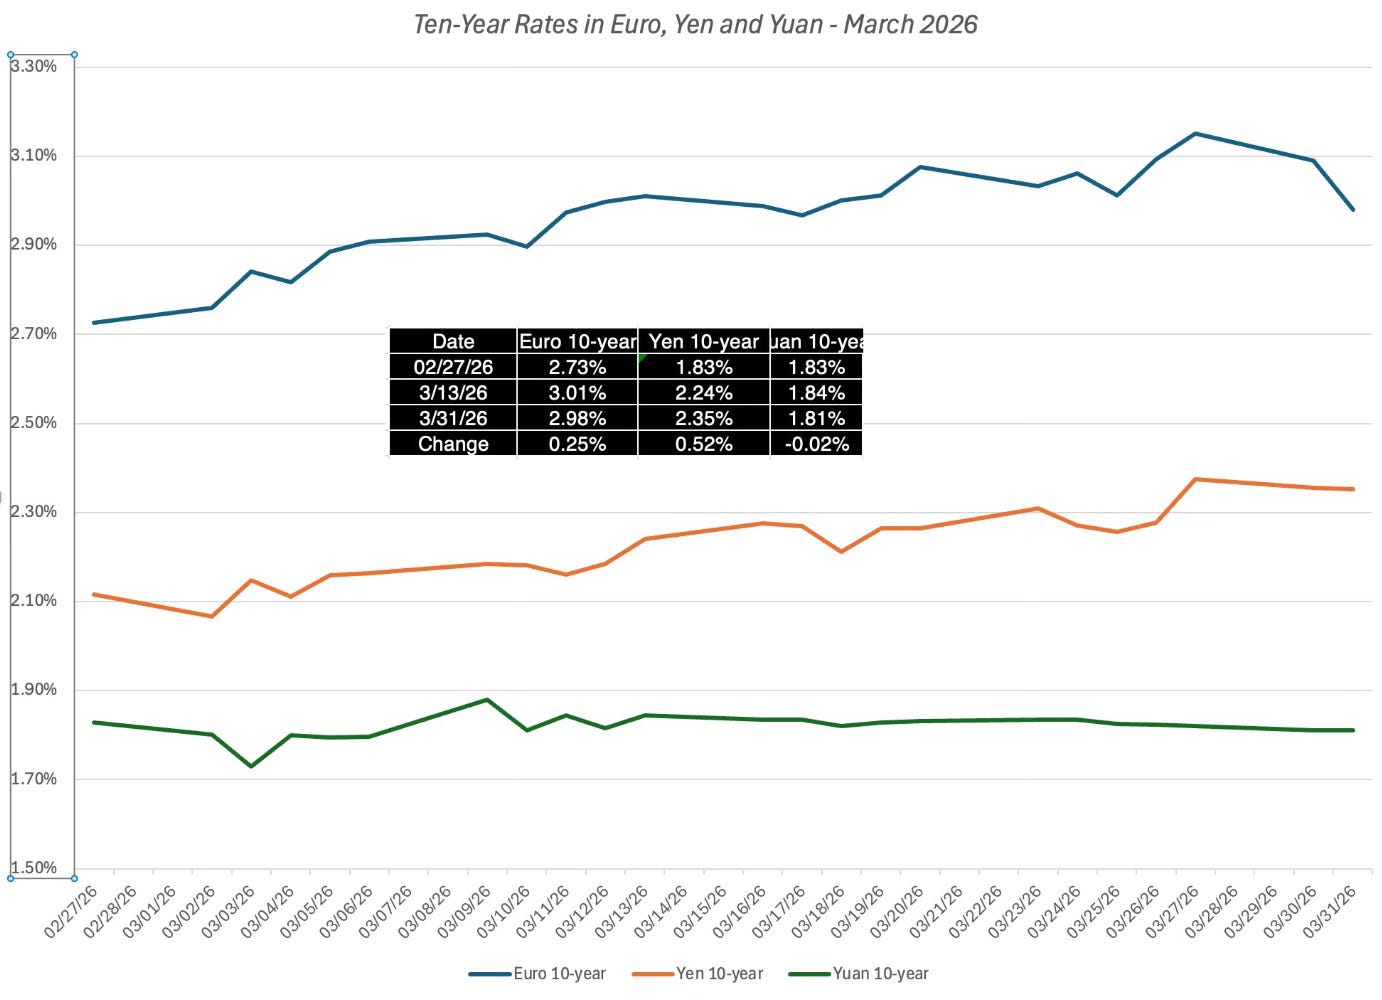
The Japanese Yen and Euro rates are up significantly over the month, but the Yuan rate has seen no change in March 2026. Staying with the market narrative, this indicates higher inflation across countries and currencies.
While there are many who are speculating on what higher inflation and oil prices will do to the economy, and investment banks and data services (See Moody’s, Goldman Sachs) have been rushing to update their forecasts for the US economy, the market has not been in as much of a rush to make the judgment. The economy was showing signs of fatigue coming into March 2026, with anemic growth and employment numbers, and it is possible that the oil price shock will tip it over into a recession.
The Price of Risk
The heightened uncertainty generated by war and its consequences has played its way out not just in oil prices and treasury rates, but in the prices that investors charge for risk. In a month where the clash between greed and risk took front stage, with the balance shifting often on a minute-by-minute basis during the trading day, we also see increases in the price that investors charge for taking risk in both equity and bond markets. In the equity market, that price of risk is the equity risk premium, a topic that I talked about extensively in this post and paper, with the argument that a good measure of this risk premium will be forward-looking and dynamic. My implied equity risk premium estimates tried to capture the changes in equity risk premiums on a daily basis, and completing the assessments for the entire month, here is what the equity risk premiums looked like in March 2026:
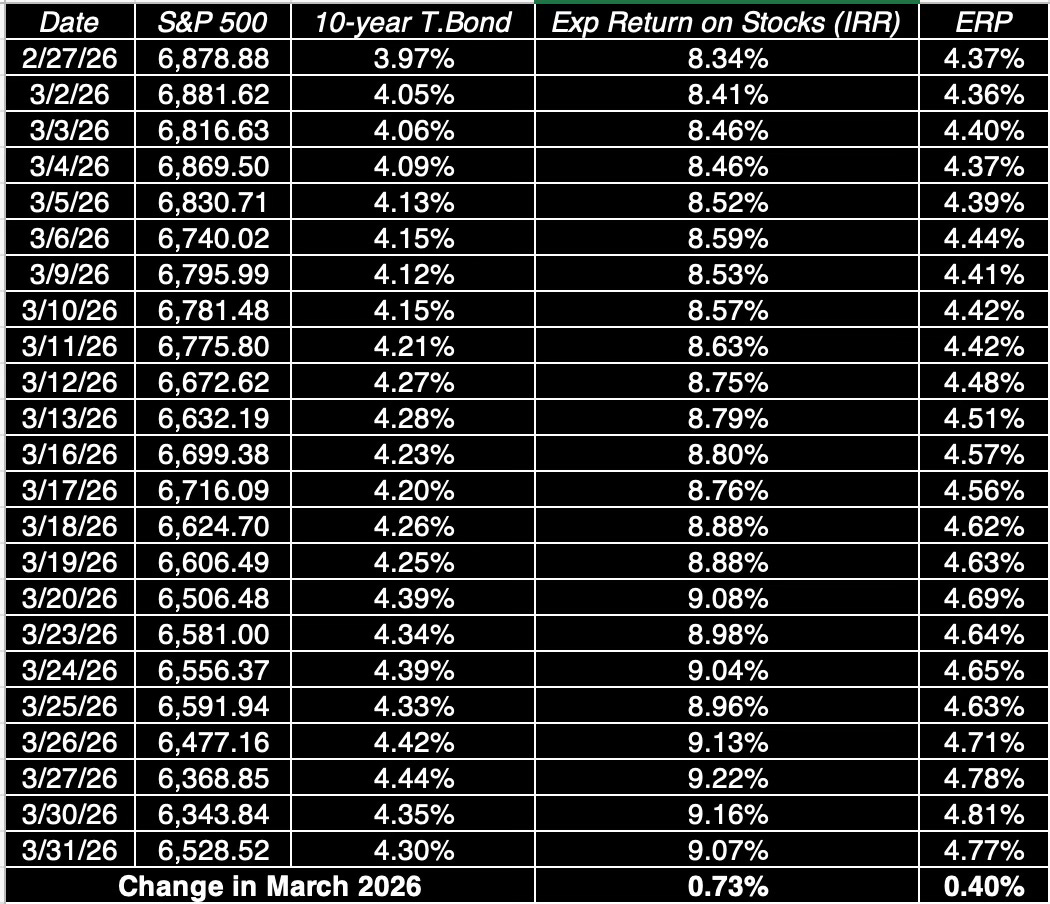
The surprise here is not that the equity risk premium rose over the course of the month, expected given what was happening in the Middle East, but that it rose so modestly. In fact, over the course of March, the implied equity risk premium for the S&P 500 rose from 4.37% on February 27, 2026, to 4.77% at close of trading on March 31, 2026, an increase of 0.40% for the month.
In the bond market, the price of risk is the bond default spread, and in the graph below, I look at default spreads for seven bond ratings classes from AAA to C (& below):
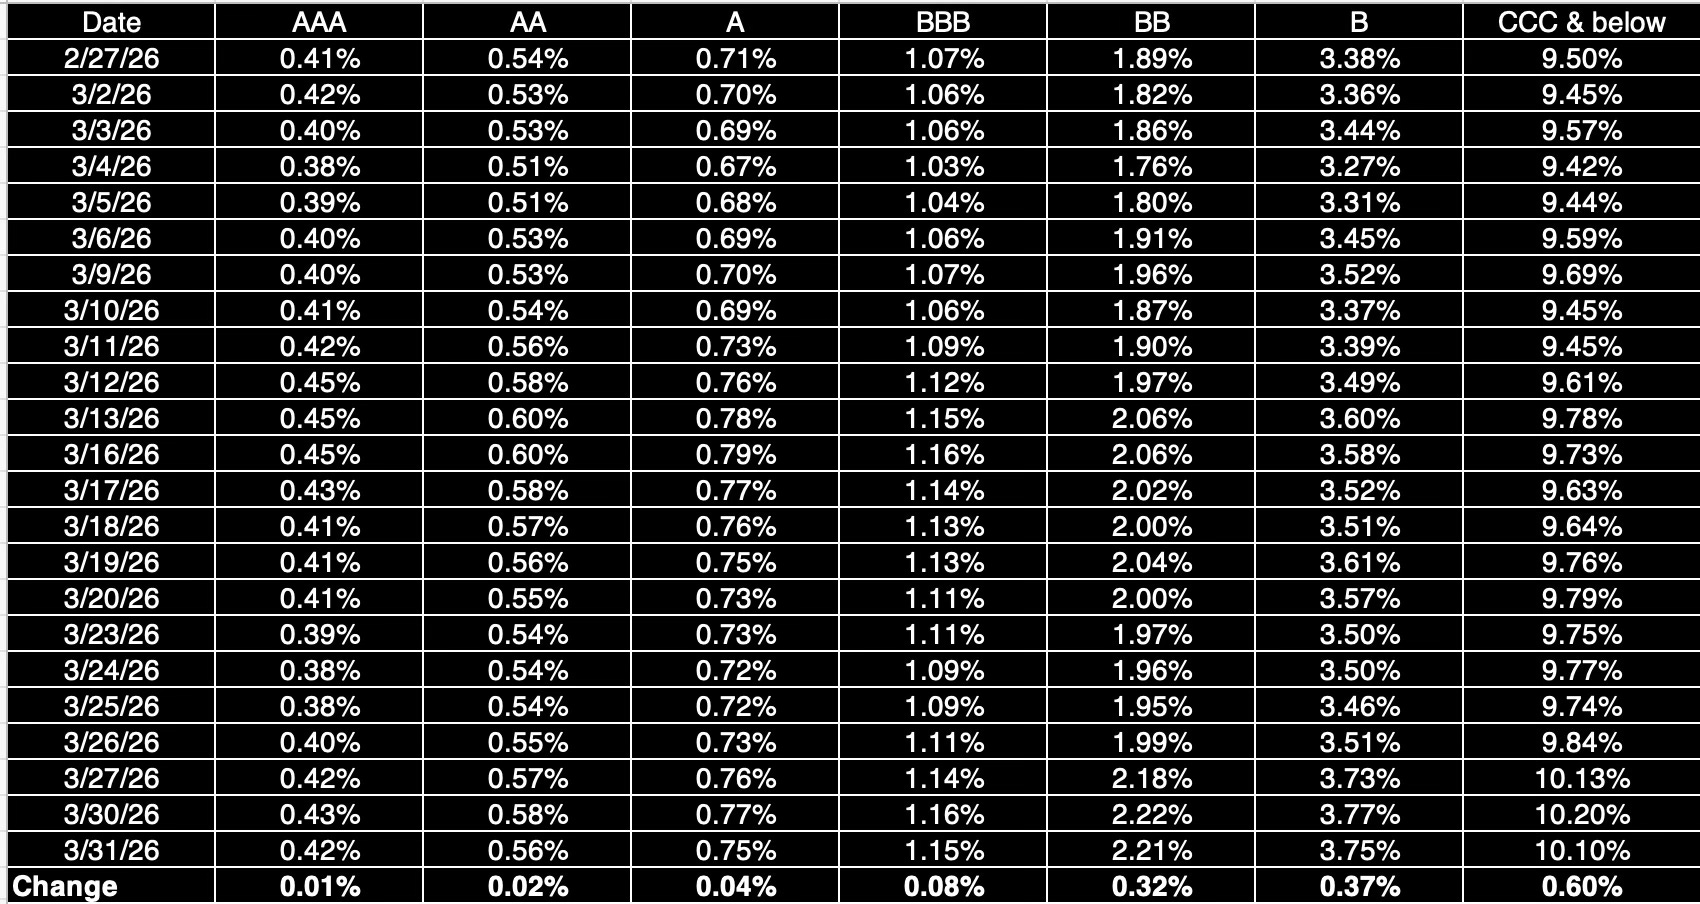
Here again, the spreads increased over the month, but only modestly, even at the lowest ratings classes. Thus, the BBB default spread over the 10-year treasury rose only 0.08% during the month, from 1.07% on February 27, 2026, to 1.15%on March 31, 2026, and the high yield spread (for CCC and below) increased from 9.50% at the start of March 2026 to 10.10% at the end of the month.
The third proxy for risk is the volatility index (the VIX) for US equities, and that measure rose during the course of March 2026:
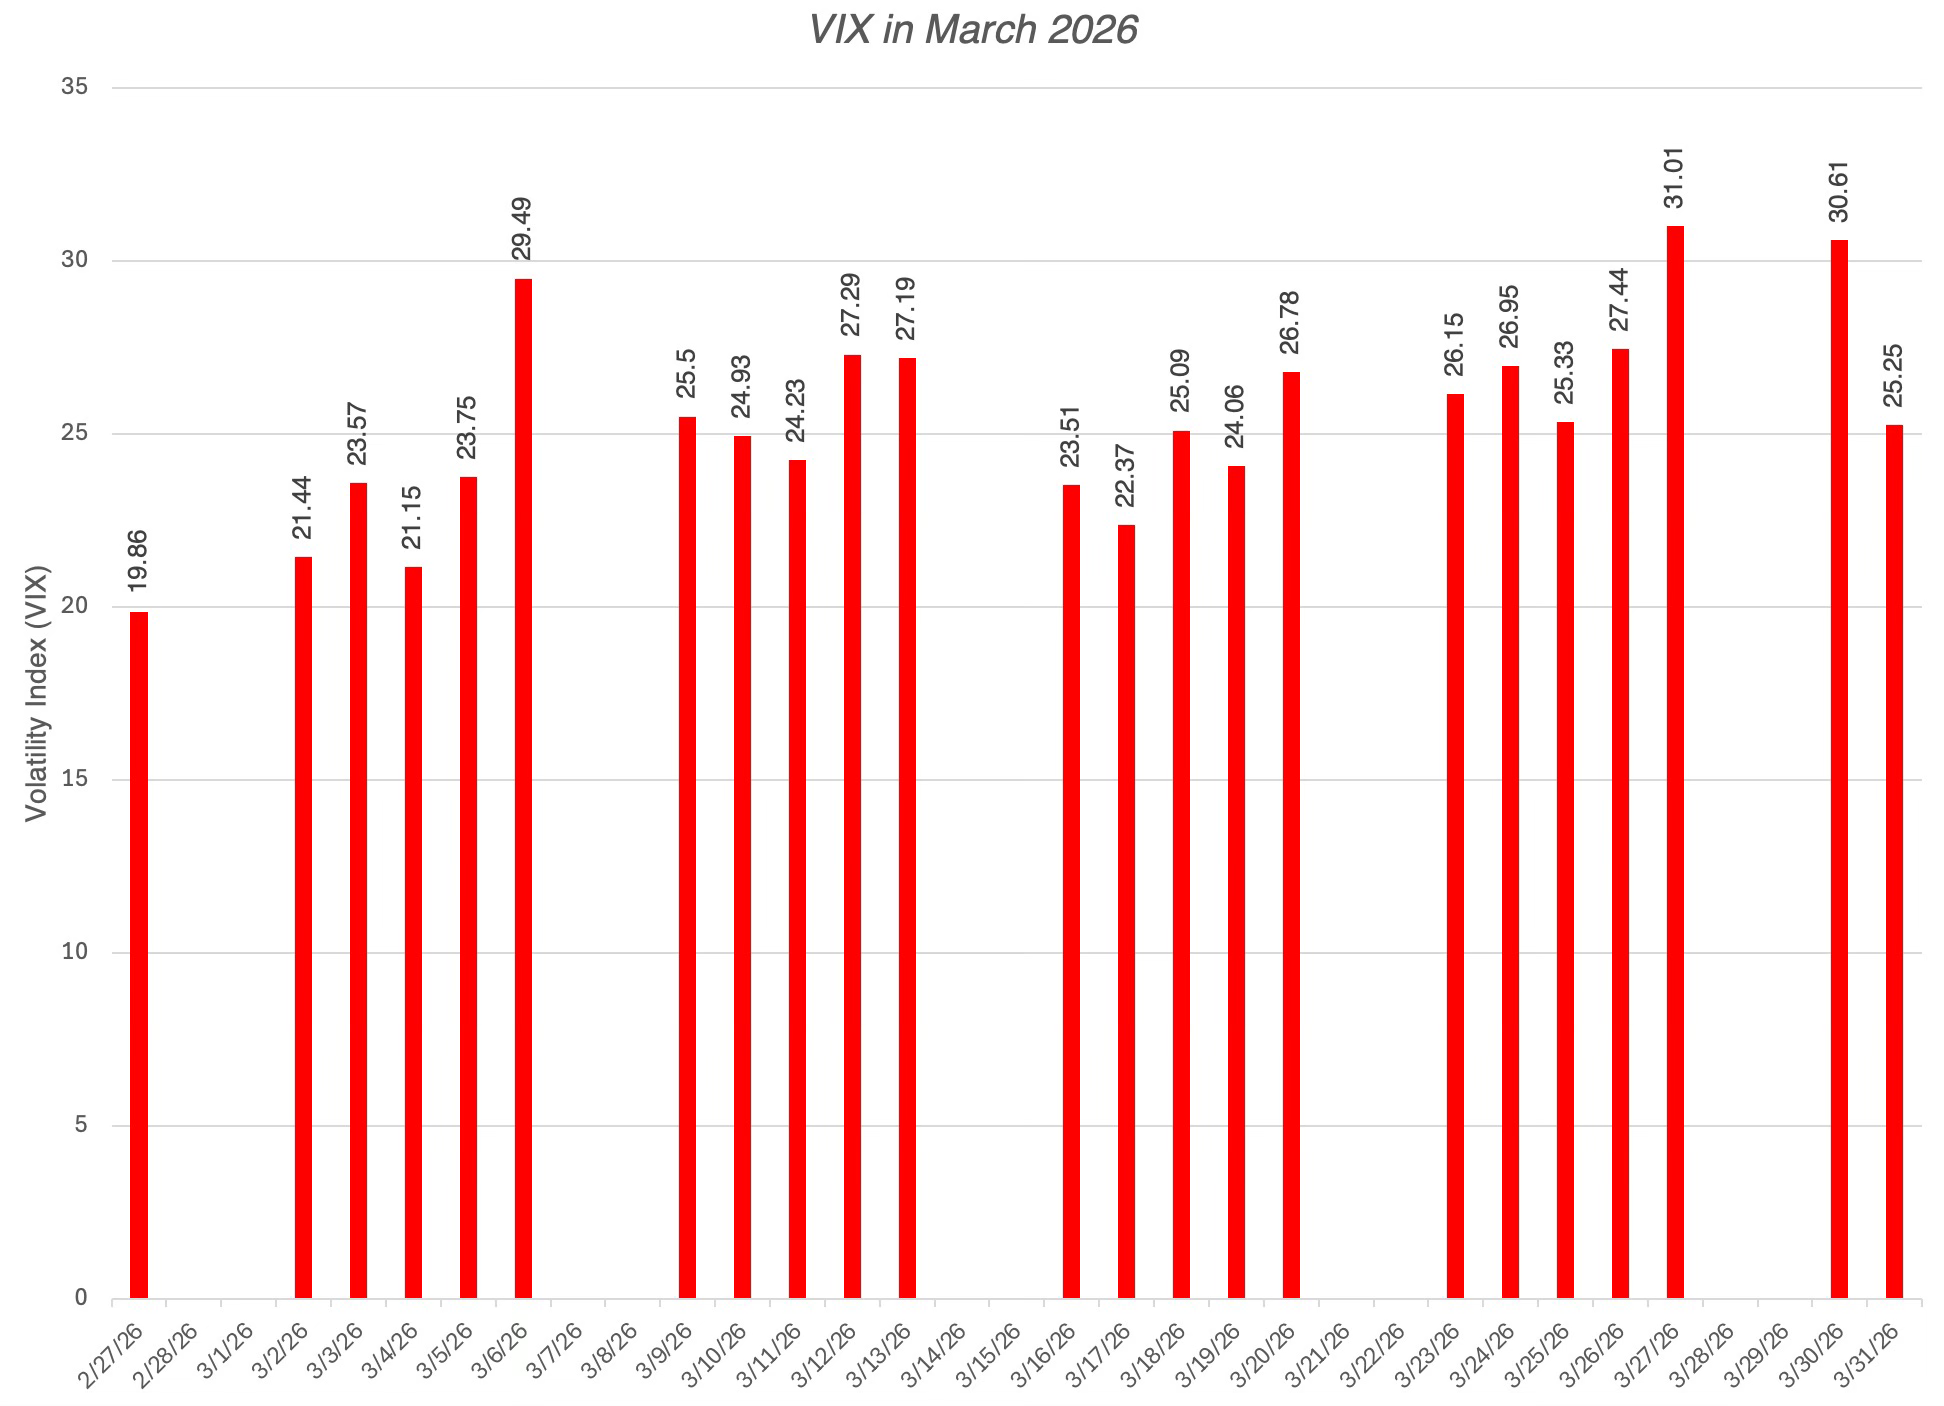
During March 2026, the VIX rose from19.86 at the start of the month to 25.25 by the end of the month, an increase much smaller than the increases we saw in March 2020 (COVID) or in the first week of April 2025 (Tariff week).
With the caveat that this is still mid-narrative, the bottom line from the movement in all of these risk measures is that while the market had a bad month, much of the marking down in equity values can be attributed to real concerns about higher inflation and economic damage, and is not the result of panic selling, at least in the aggregate. To back this up, I took a look at two collectibles - gold, which has a history of holding its value or even increasing during crises and panics in financial markets, and bitcoin, which has not had that history so far, but is marketed by its advocates as a potential hedge:
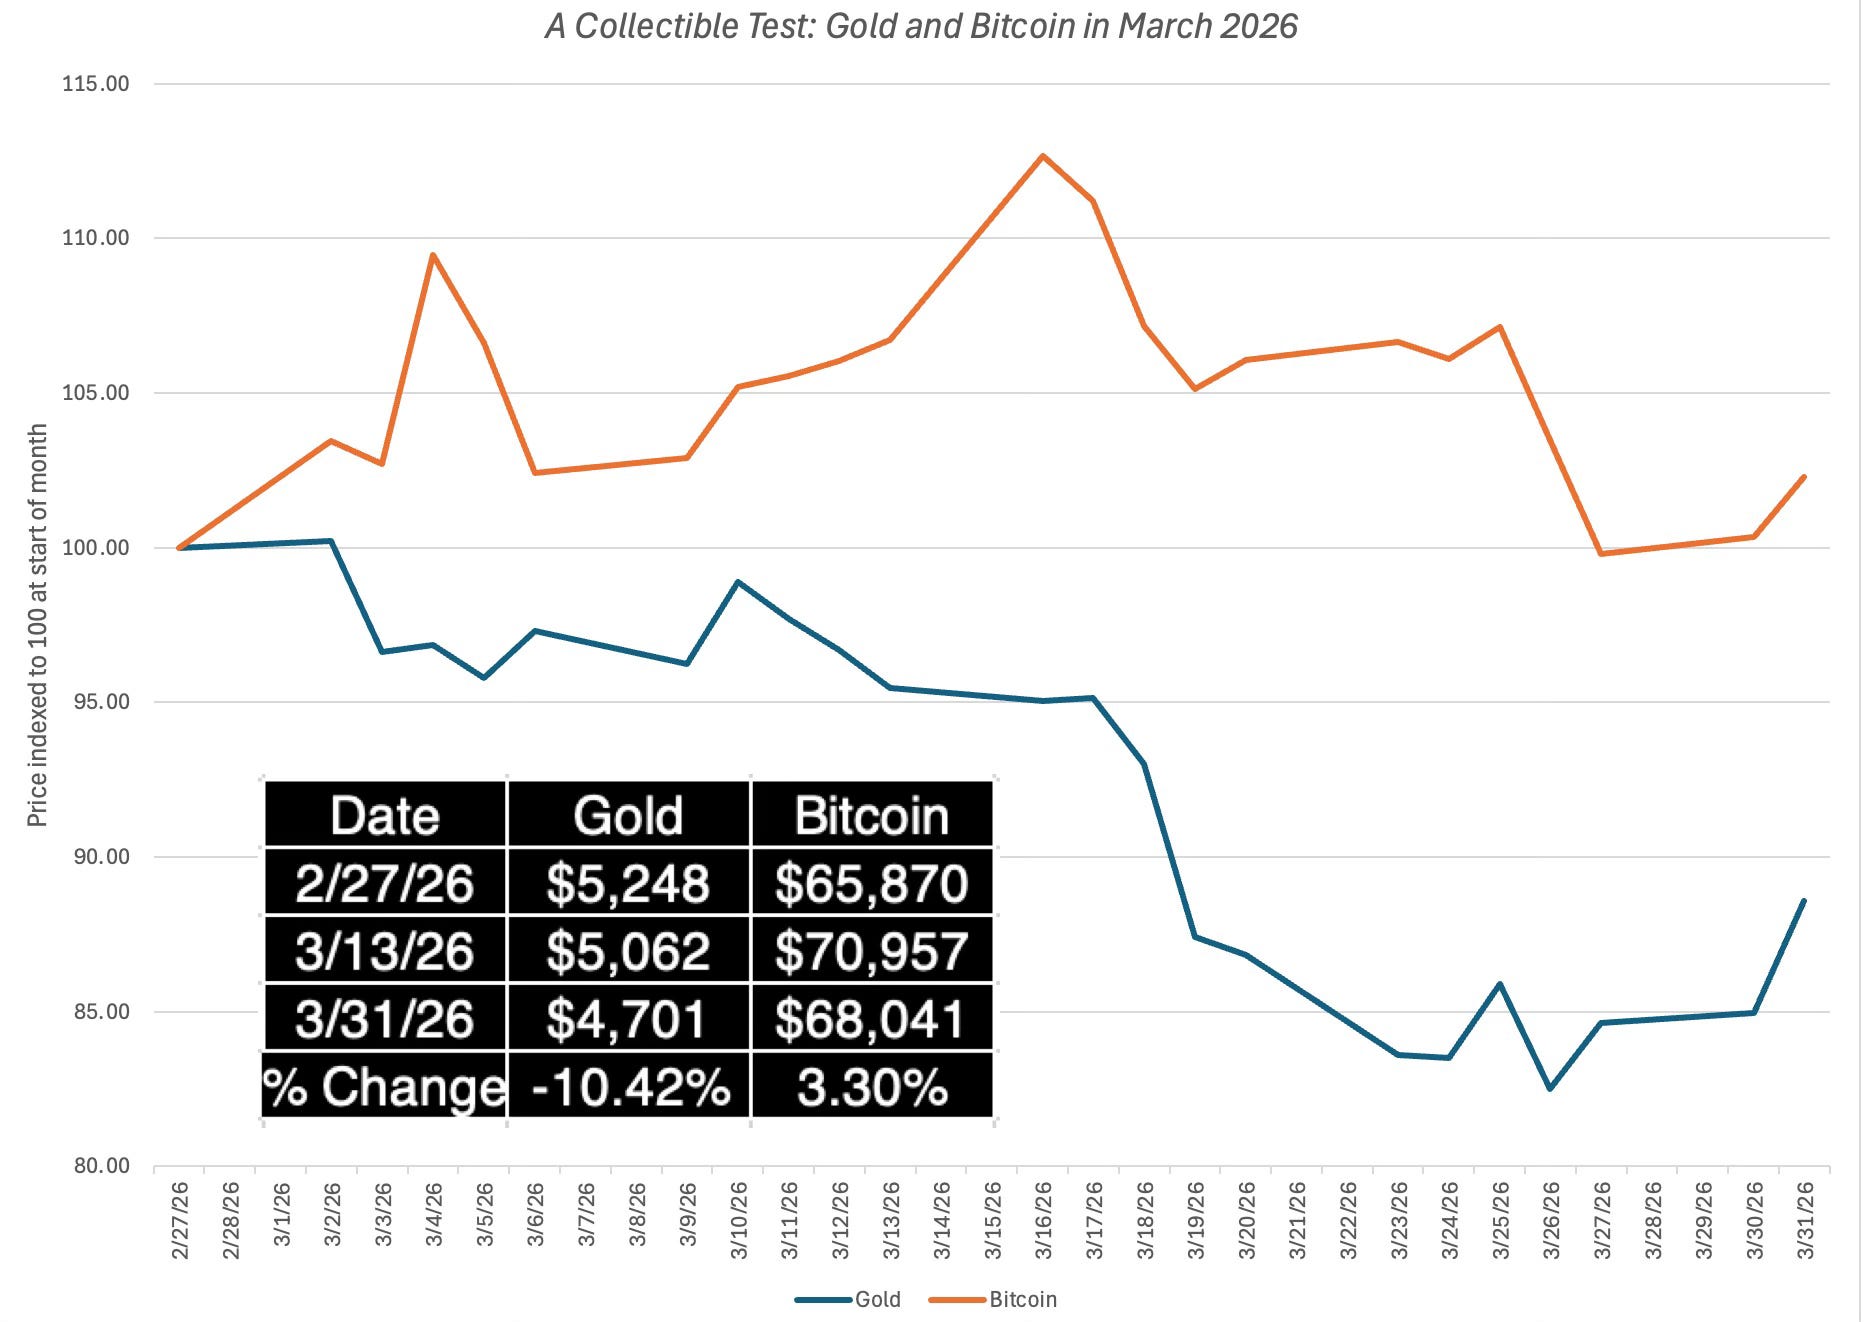
Gold was down 10.42% during March 2026, uncommon for a crisis month, but bitcoin was up 3.30% during the month, and it is entirely in keeping with bitcoin investors marching to their own music, though it will be interesting to see how this dynamic plays out, as this repricing continues.
Effect across Geographies
The war is in the Middle East, but there is no place to hide from its effects. To see how the war has played out in different regions, I looked at the change in aggregate market cap, in US dollar terms, in March 2026:
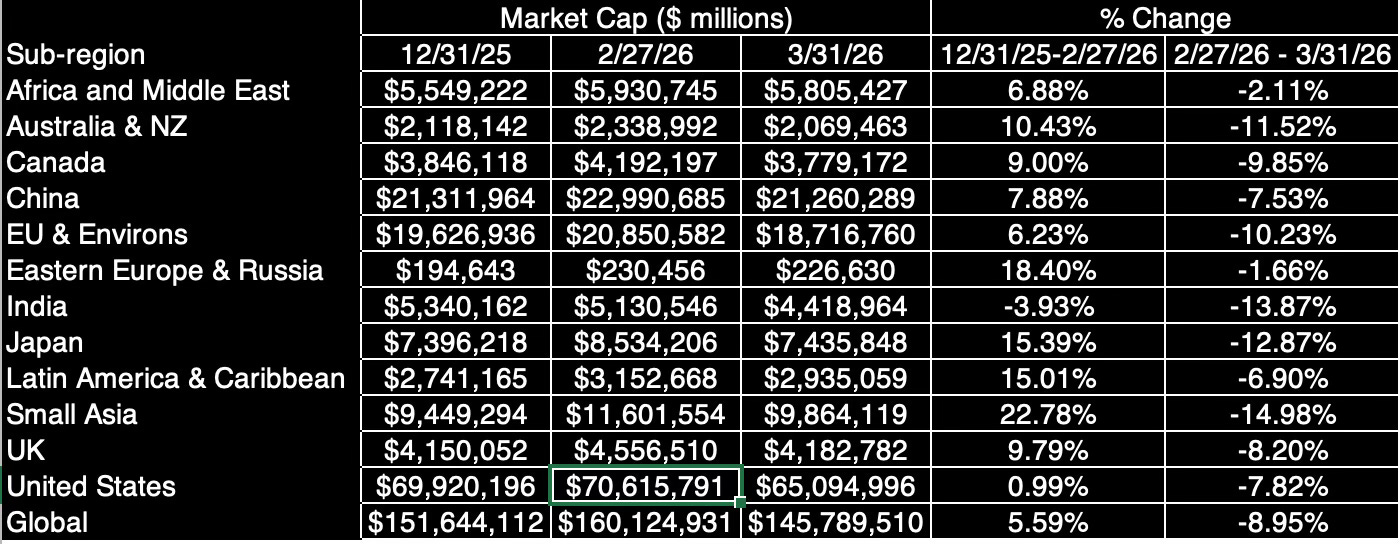
You may be surprised to see Africa & the Middle East and Eastern Europe & Russia show up as the best performing markets, with about 2% decreases in market capitalization, but it reflects the dual impact of the war. While it has wreaked havoc across the Middle East, the higher oil prices that it has brought with it are providing upside for oil producers that offsets some of the damage.
Since these dollar returns reflect local market performance as well as the strength/weaknesses of their currencies against the dollar, I looked at the US dollar’s performance in March 2026:
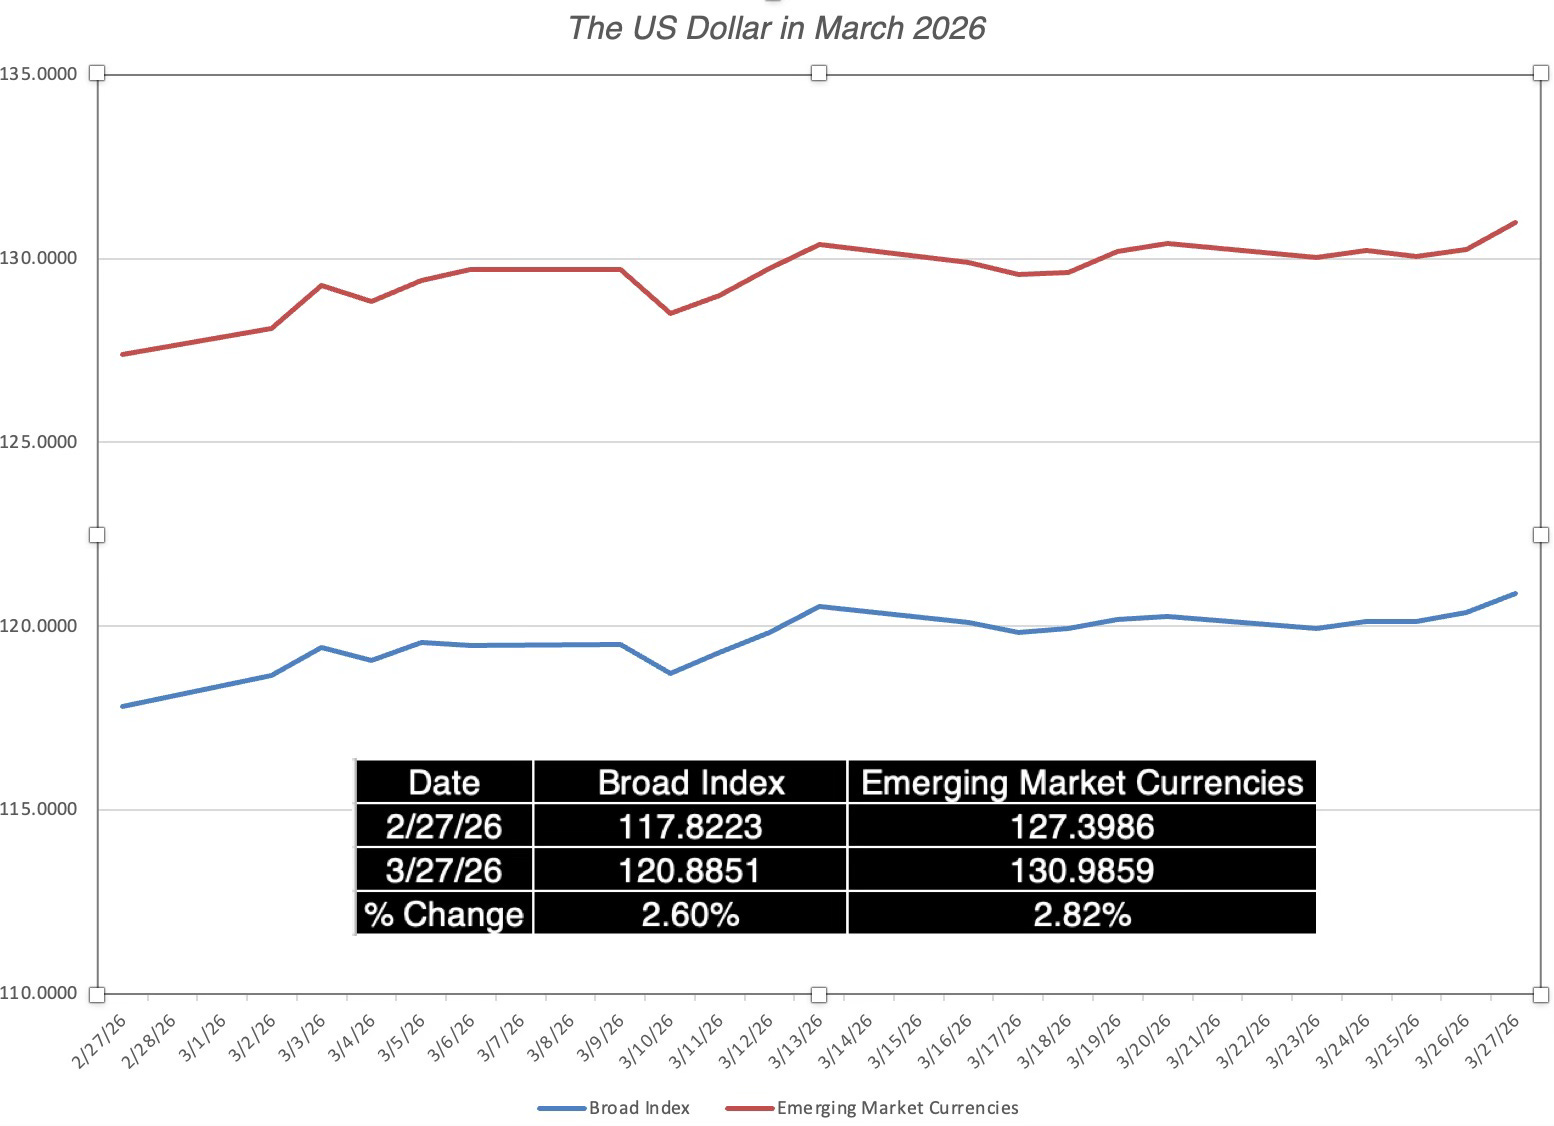
I know that I am piling on at this stage, but I do compute equity risk premiums for other countries twice a year, once at the start and once mid-year. Given how much March has shaken up the status quo, I will make an exception and re-estimate equity risk premiums, by country, updating both my mature market premium (which I estimate from the S&P 500) as well as the country ratings, default spreads and country equity risk premiums for other countries.
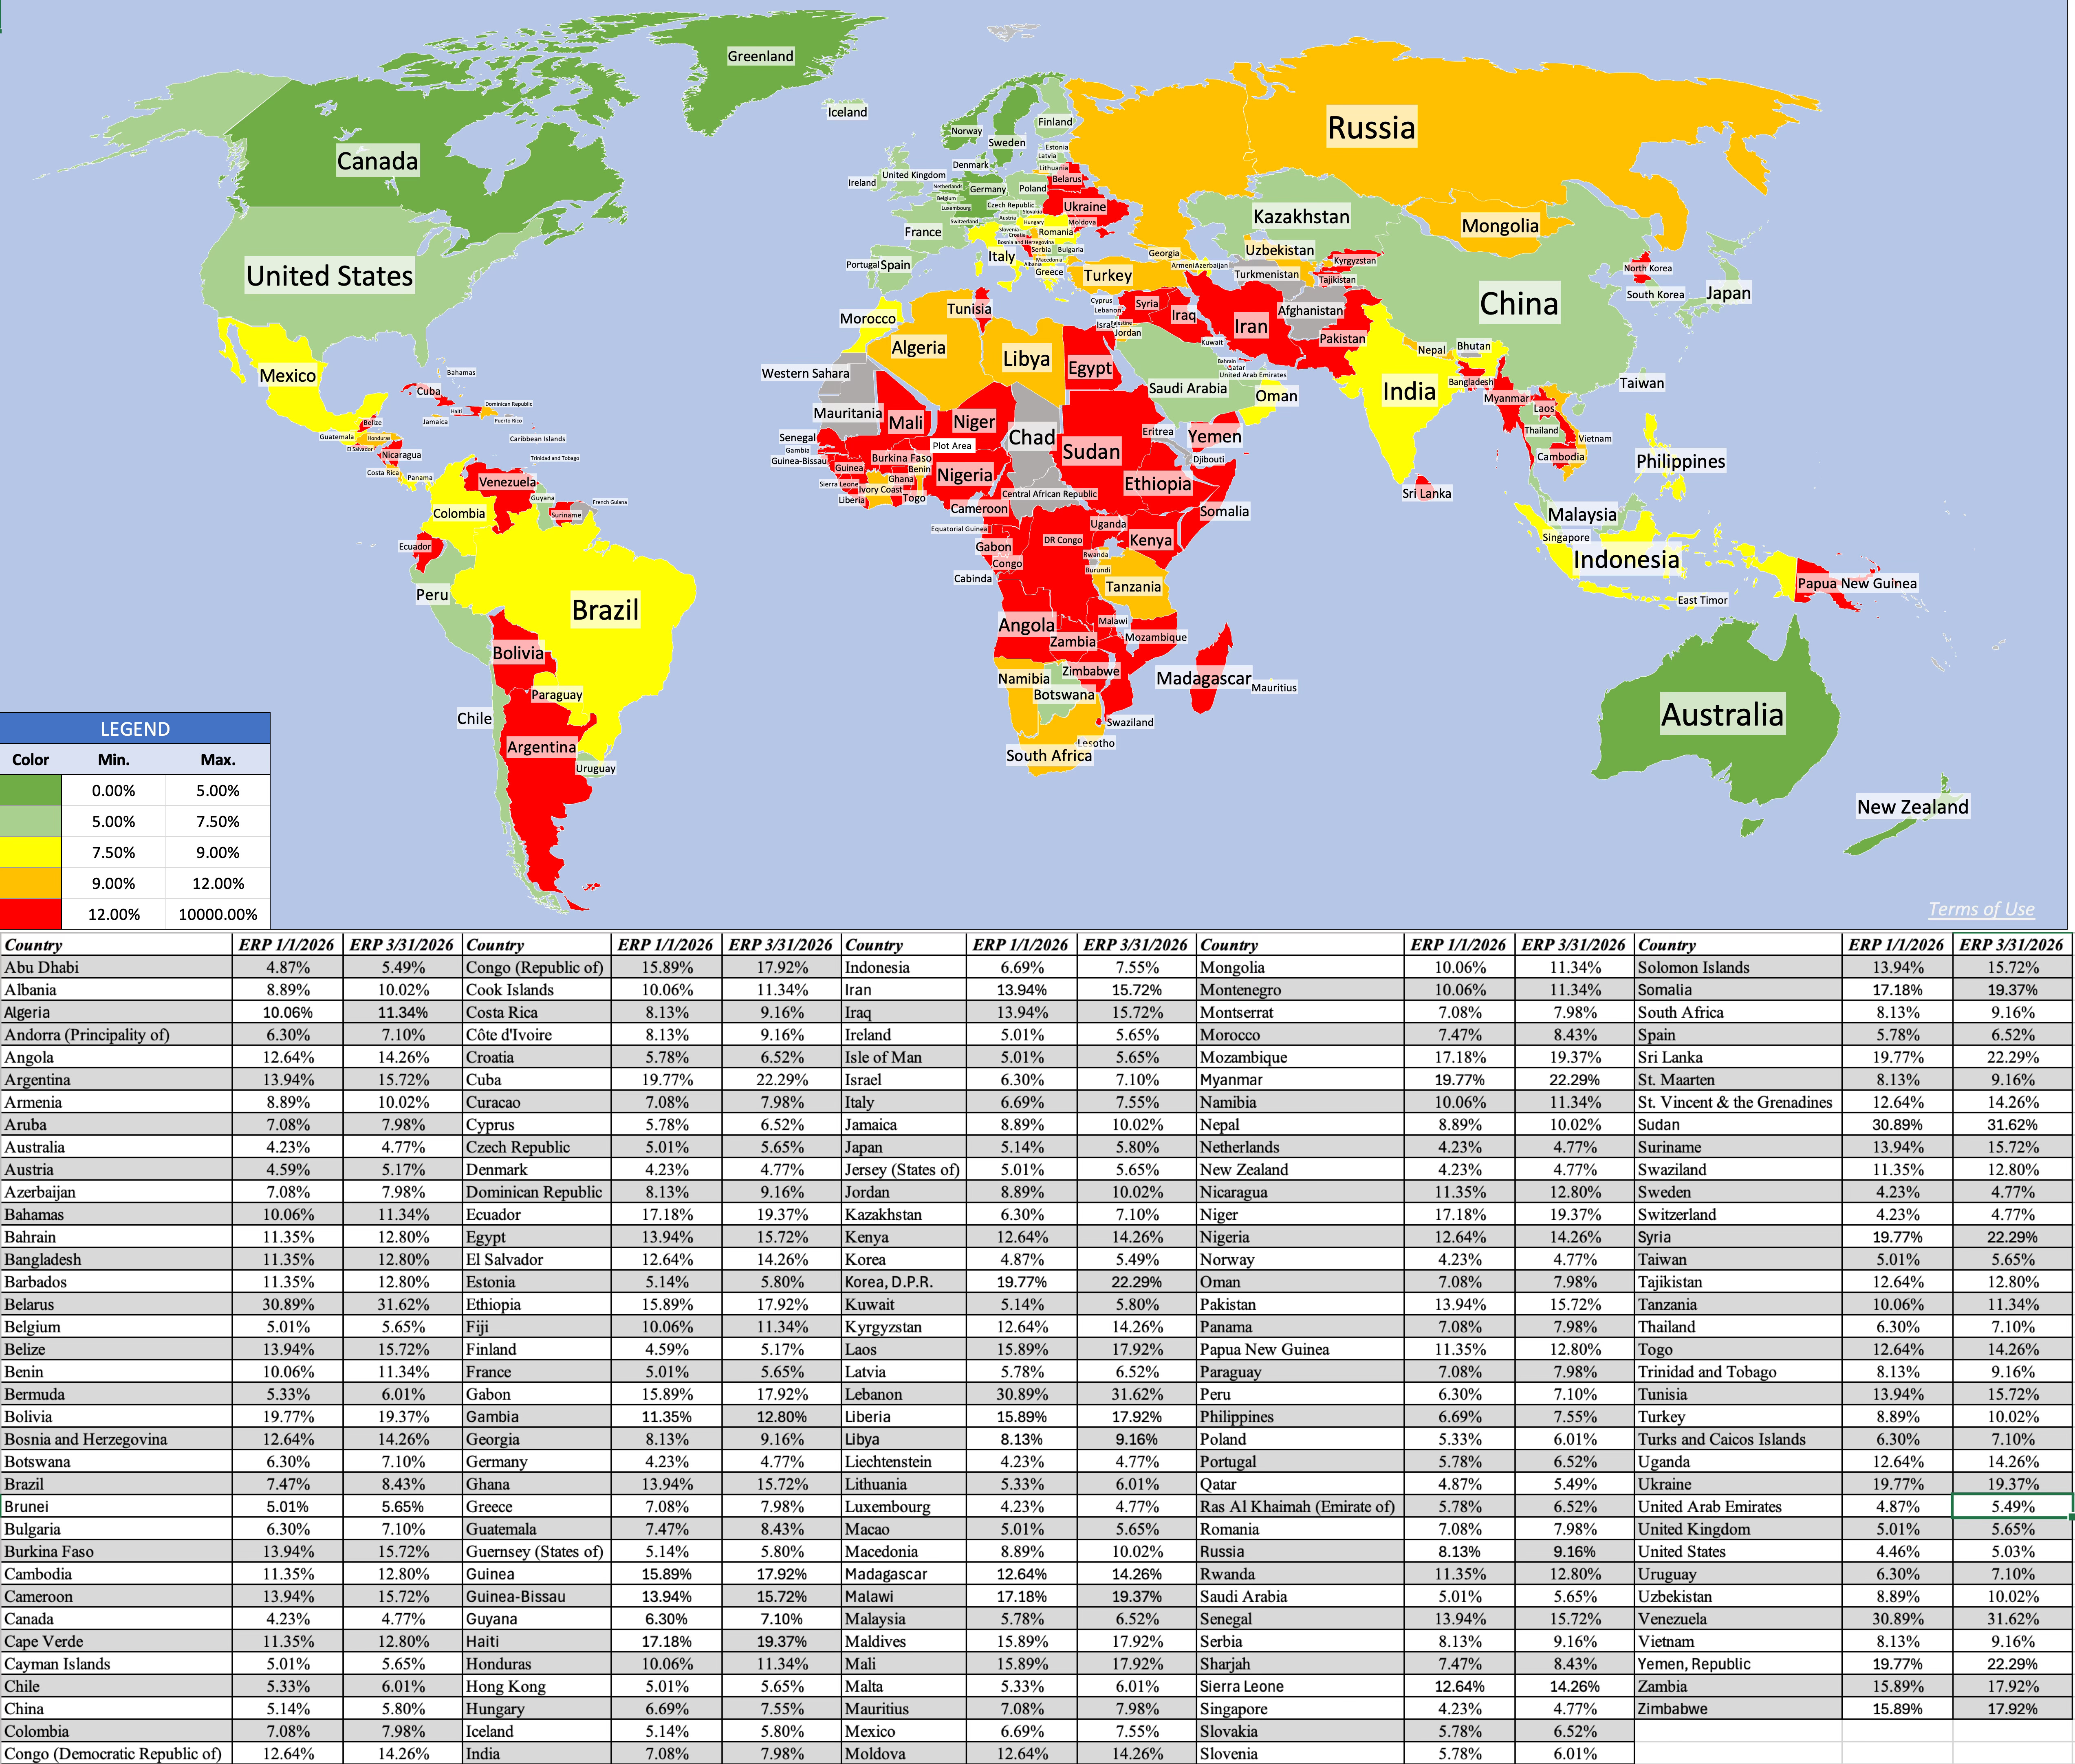
Download spreadsheet with country ERPs
It is worth noting that these equity risk premiums are computed based upon sovereign ratings, which are slow to change, as the world convulses. That has been an issue with my ERP computations for Russia and Ukraine, since 2022, with the rating for the former withdrawn and the rating for the latter frozen at Ca (Moody’s); I have use a country risk score from PRS for the last two years to update Russia’s equity risk premium, an have done the same for the Ukraine in this update. You can see the same issues now, with the war in Iran rocking the boat, and at least for the Middle East, there is reason to believe that the ratings may understate country risk. While none of the countries in the war zone have seen their sovereign rating change (yet), these countries have market estimates of sovereign default risk in the form of sovereign CDS spreads, I looked at the movement in those spreads during the course of the month:
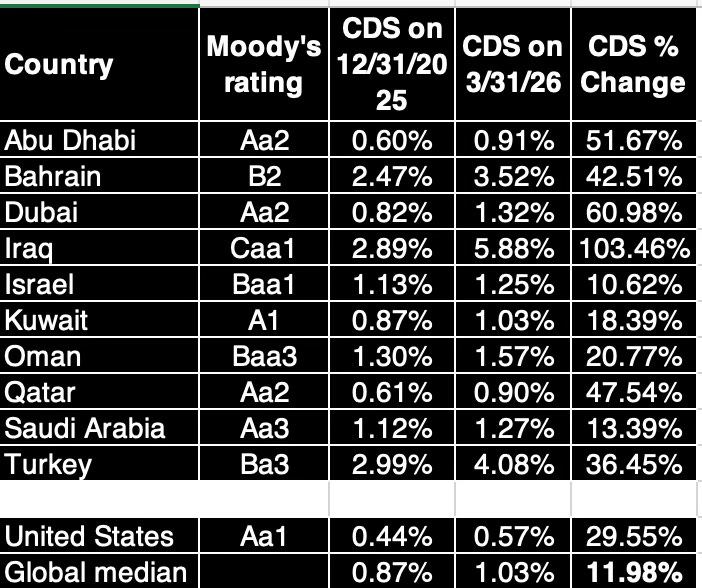
Not surprisingly, market measures of default risk are more sensitive to war effects, and have risen for much of the Middle East, as worries have mounted, with bigger increases in Qatar, the UAE and Turkey than in Saudi Arabia and Kuwait. The United States has also seen a surge in its sovereign CDS spread, and the global sovereign CDS spreads have risen about 12% in the first quarter of 2026. Using these sovereign CDS spreads as measures of default spreads for this part of the world may yield more realistic equity risk premiums.
What now?
I noted at the start of this post that the uncertainties that manifested during March 2026 about the direction, duration and effects of war are still unresolved and perhaps even grown as we start April. As investors try to navigate their way through this period, here are the questions that you will need to answer to decide where you fall in the continuum between complacency to full-blown panic:
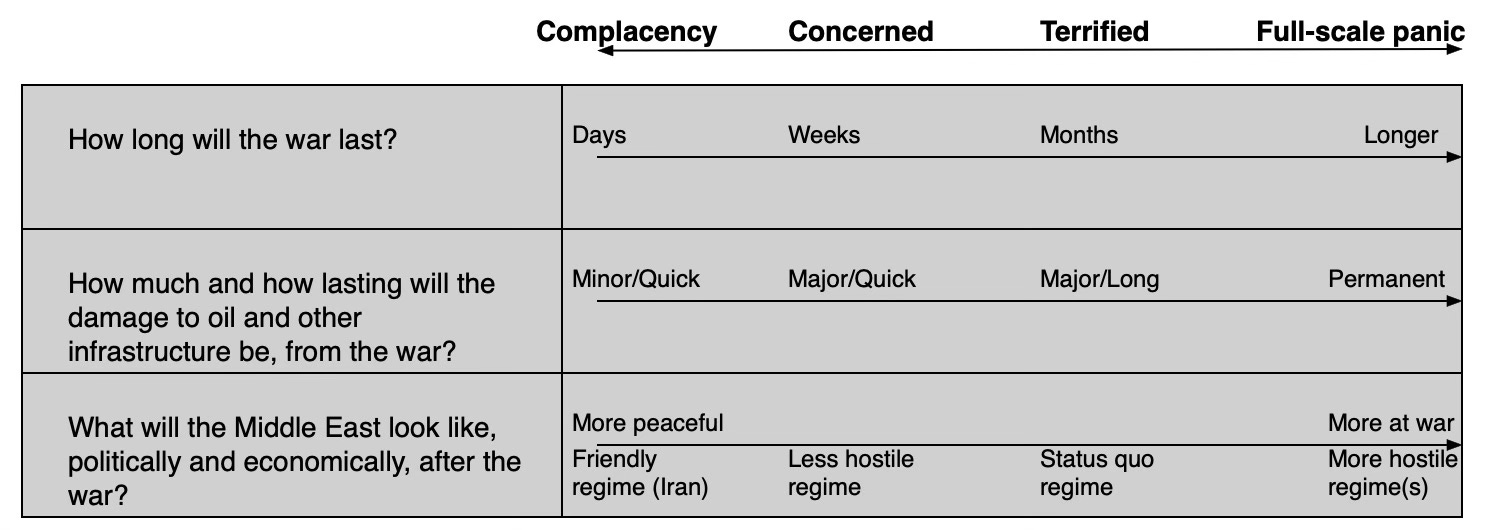
In the complacency scenario, the war ends quickly (in days or weeks, rather than months), the damaged infrastructure is repaired quickly and the new regime in Iran is viewed favorably by the rest of the world, allowing the sanctions on the country to be removed, it is likely that oil prices will drop, perhaps even to below pre-war levels, as Russian and Iranian oil is freely bought and sold. In the full-scale panic scenario, the war continues for months, with lasting damage to infrastructure and supply chains and Iran’s new government stays sanctioned, oil prices are likely to stay high and perhaps even go higher, the global economy will be kneecapped and parts of the Middle East (Dubai and Abu Dhabi) that had created a business and tourist friendly setting will struggle to find their balance.
In either case, the war has shaken up the status quo, and I see lasting consequences that go well beyond oil. The capital flows from the oil rich countries which has flowed generously to everything from AI start ups to Premier League clubs will shrink, creating down-market effects. That money, and the funds that were set aside to build vanity projects, from ski resorts in the deserts to state-of-the-art cities will be redirected to building pipelines and securing the flow of oil. Global politics has also been roiled, and even if the war ends quickly, there is damage that has been done to partnerships and security agreements that cannot be undone.
YouTube Video
Datasets
There’s something almost unsettling about how contained the reaction has been. Oil surges, rates climb, uncertainty everywhere, and yet the price of risk only inches higher, as if the market is acknowledging the disturbance without fully believing in it .
That kind of restraint tends to show up in the early chapters, when participants are still treating the shock as temporary, something that will pass rather than persist. The real shift usually comes later, when what was assumed to be a detour starts to look like a new road.
The question hanging in the background is whether this is just an inflation tremor or the beginning of something that forces a deeper repricing. Markets don’t panic when they’re surprised, they panic when they’re forced to admit they were wrong.
The market's muted risk premium response is the real tell — a 40bp ERP increase during active Middle East war suggests the selloff is being priced as an inflation shock, not a structural break. The sharper lens is the divergence between short rates (unmoved) and intermediate maturities (up 41bp) — the market isn't waiting on the Fed, it's pricing inflation persistence independently of whatever the Fed does next. The question that doesn't have an answer yet: if the complacency scenario plays out and oil retraces, do those intermediate rates come back down, or has something else been permanently repriced?