
Over the last few weeks, attention has (rightly) been focused on three potentially trillion dollar companies all lined up to go public, and much of the discussion has been about what SpaceX, Anthropic and OpenAI are worth (and will be priced at). In parallel, there has been a debate about indices and index inclusion criteria, a usually bland topic, but one that has become heated on the questions of whether these new mega-cap additions to the market should be included in the S&P 500. While I remain open to arguments from both sides of this debate, much of it seems to come down on the side that the index should not include these companies, with different reasons offered.
I am skeptical, since I see a combination of hidden agendas and misguided views about investing behind each of the three groups that are most vehemently against inclusions. First, you have a cadre of active investors, many of whom have been left bruised by a losing battle that they have waged over the last two decades against passive investments (index funds and ETFs), who view inclusion in the index as a fait accompli, and present this as an added risk to passive investing that can be avoided by paying these professional money managers to avoid that risk. Second, you have investing experts and academics who claim to be looking out for for retail investors and retirees, and view including these big, money-losing companies in indices as dangerous for these small investors, partly because they may not be aware of their exposure and partly because they should not be investing in these types of companies. Third, you have politicians, normally not founts of investment wisdom, speaking out about how including these large companies in government pension funds will reward billionaires, who are the villains in their storylines. In this post, I will try to step back from the heat and try to cast some light on the question of index inclusion, starting with an understanding of how indices are constructed before moving on to the roles they perform in markets and ending with a discussion of whether and how inclusion of these companies will affect the passive versus active investing debate.
Index Construction - Inclusion, Weights and Returns
Indices have been around almost as long as assets have been bought and sold in markets, but it is undeniable that the extraordinary growth of financial markets in the last few decades, across geographies and asset classes, has added rocket fuel both to the number of indices in existence as well as their visibility. But what is it that sets one index apart from another, and why do indices that purport to measure the same market sometimes move in different ways? To understand the answer to these questions, we need to deconstruct indices and see how they are put together:
Constituents: The first and perhaps most critical determinant of an index are its constituents, and what determines their inclusion. Take, for instance, the S&P 500, which Standard & Poor’s (its creator) describes as the “gauge of large-cap US equities”, and is without doubt the most widely tracked and followed index in global markets. As its name indicates, this index has five hundred of the largest market-cap companies listed and traded in the United States, with caveats on inclusion relating to listing age (listed at least a year), liquidity (measured by looking at shares that are available for investors to trade in the market, i.e., free float) and profitability (positive profits in the four quarters leading into the listing). There are local indices that exchanges (NYSE, NASDAQ), equity markets in other geographies (the Bovespa for Brazilian stocks and the Sensex for Indian stocks) and individual sectors or industries. Across asset classes, there are indices for fixed income, as well as for real estate, fine art and crypto currencies.
Weights: You can have two indices that contain the same companies that register very different results over time, depending on how these companies are weighted, with three common choices. The first is to weight every company in an index equally, with the benefit being simplicity, but the cost being that to the extent that companies in an index have very different sizes, the performance on an equally weighted index will not capture aggregate market performance, because it will be skewed towards smaller companies. The second, and one used by some older indices like the Dow 30, is price-weighting, where the companies with the highest price per share are weighted more than companies that have lower priced shares. I cannot think of a single redeeming quality to price weighting, since it measures very little of consequence, and suffers from breakdowns, right after stock splits. The third and most widely used mechanism for construction indices is market capitalization, with tweaks sometimes added on for float (traded shares). The S&P 500, as I noted earlier, uses market capitalization, based on free float, to weight companies and as a consequence, Meta punches in below its true weight, since the bulk of class B shares (which are voting shares held by Zuckerberg) are not counted, as does Walmart, where some family-controlled holdings are treated as non-traded.
Index level mechanics: Once constructed, an index has to be measured, and to the extent that these indices are designed to capture market prices, the first step is creating a mechanism for converting market prices on the constituents to an index level. Consider, for instance, the S&P 500 which ended trading on June 15, 2026, at 7554.29, and relating that number to the market capitalization of the companies that make up the index. At close of trading on June 15, 2026, the cumulative float-adjusted market capitalization of the 500 companies in the index was $63,498.44 billion and the index units for the conversion can be computed as follows:
Index units = Index level / Float-adjusted market capitalization = 7554.29/ 63498.44 = 0.1190
Note that there is no intuitive significance to the index units standing alone, but its movements over time can be an indicator of changes happening at companies, because of issuances and stock buybacks, as well as changes in index constituents. If asked to compute earnings or dividends on the S&P 500, these index units come into play again, when converting the aggregated dividends and earnings across all of the S&P 500 companies into index dividends and earnings. In 2025, for instance, the aggregated dollar dividends on the S&P 500 was $664.90 billion, and multiplying that value by the index units (0.1190) yields an index dividend of 79.12 for the year.
Price updating: While index levels are starting points, most investors track indices for changes in the index, with increasing stock prices translating into higher index values. Indices that track publicly traded stocks, like the S&P 500 and the Dow 30, should adjust instantaneously as the prices of their constituent companies change during the course of a trading day, making the index a real-time measure of market movements. Indices that capture only price changes miss the other component of returns on a stock, which is dividends, and constructing an index that incorporates dividends paid on a continuous basis does take work and requires assumptions about whether the dividends are reinvested in the index or extracted by investors. Though not as widely disseminated as the pure-price version, there is a variant of the S&P 500 that computes the total return on the index, with dividends included. Indices of assets that are not continuously traded, most notably real estate (like the S&P Case-Shiller home price index), try to overcome the absence of price data on the assets by extrapolating from the pricing of the subset of assets that get traded, leading to noisier estimates for index value and lags in price adjustment.
Index changes (inclusions and exclusions): Even the best constructed indices have to confront change and have mechanisms to deal with that change that are transparent and quick to put into practice. Some of that change will come from companies being removed from public markets, either because they are acquired, taken private or because of bankruptcy. Some change will be caused by new companies being listed on the market or some will be created by changes in market cap in companies that bring them into contention for inclusion in the index, either because the market cap has risen (making them large enough to qualify for a large cap index) or has dropped, removing them from large cap status. Since you do not want abrupt changes in the index level coming just from replacing a company with a low market cap with one with a much higher market cap, the adjustment has to come from changing the index units. Thus, assume that a company goes public with a trillion dollar market cap and that it will be replacing a company with a one-billion market cap, the adjusted index units for the S&P 500 will be as follows:
Index units = Index level / Float-adjusted market capitalization + Market cap of added firm - Market cap of eliminated firm = 7554.29/ (63498.44+ 1000 -1) = 0.1171
This will then percolate through into the index earnings and dividends estimates, for the index. Note that while the index level will be unchanged by the addition of the trillion dollar company, the other components that it brings with it, including higher growth and perhaps negative earnings, will alter the fundamentals of the index going forward.
With these index mechanics in mind, it is quite clear that if S&P does include SpaceX, OpenAi and Anthropic in the S&P 500 index, the index will not change at the time of the replacement, but it will change the index fundamentally going forward, bringing in more risk, a near term hit to earnings and perhaps a long term increase in growth.
The Index End Game
When indices were first created for markets, their primary purpose was to create composite measures of market performance, with a single number (the index value) capturing the performance of a much larger group of assets. Over time, though, the use of indices has expanded, first as proxies to assess the performance of active investors, to see whether they over or underperformed, and then as investment vehicles, with the advent and growth of index funds and ETFs.
Measurement
I started in equity markets in 1981, and at that time, indices were primarily measures of market performance. At the time, for most investors without intraday access to markets and without financial news channels, news of market performance, on most days, was a snippet on the evening news, where the anchor would mention the market’s change during the day, usually using the Dow 30 as a stand in for the market. Indices continue to perform the measurement role, though our access to data has changed dramatically, with real time updates on our devices occurring all through the day. From the measurement perspective, it is worth looking back at index construction and looking for indices that best capture what you are trying to measure. The reason that the S&P 500 has acquired primacy is that while it includes only 500 companies in a US equity market that has almost 6000 publicly traded companies, the fact that these are the companies with the largest market capitalization means that the index represents more than 80% of the market capitalization of all US equities, and as a result, it is the single best proxy for aggregate equity market performance in the index. That said, a different framing of the measurement question can lead you to a different index choice. Thus, if you are trying to measure how the average US equity did during a period, you may be better served using an equal-weighted equity index for that measurement.
Performance Evaluation
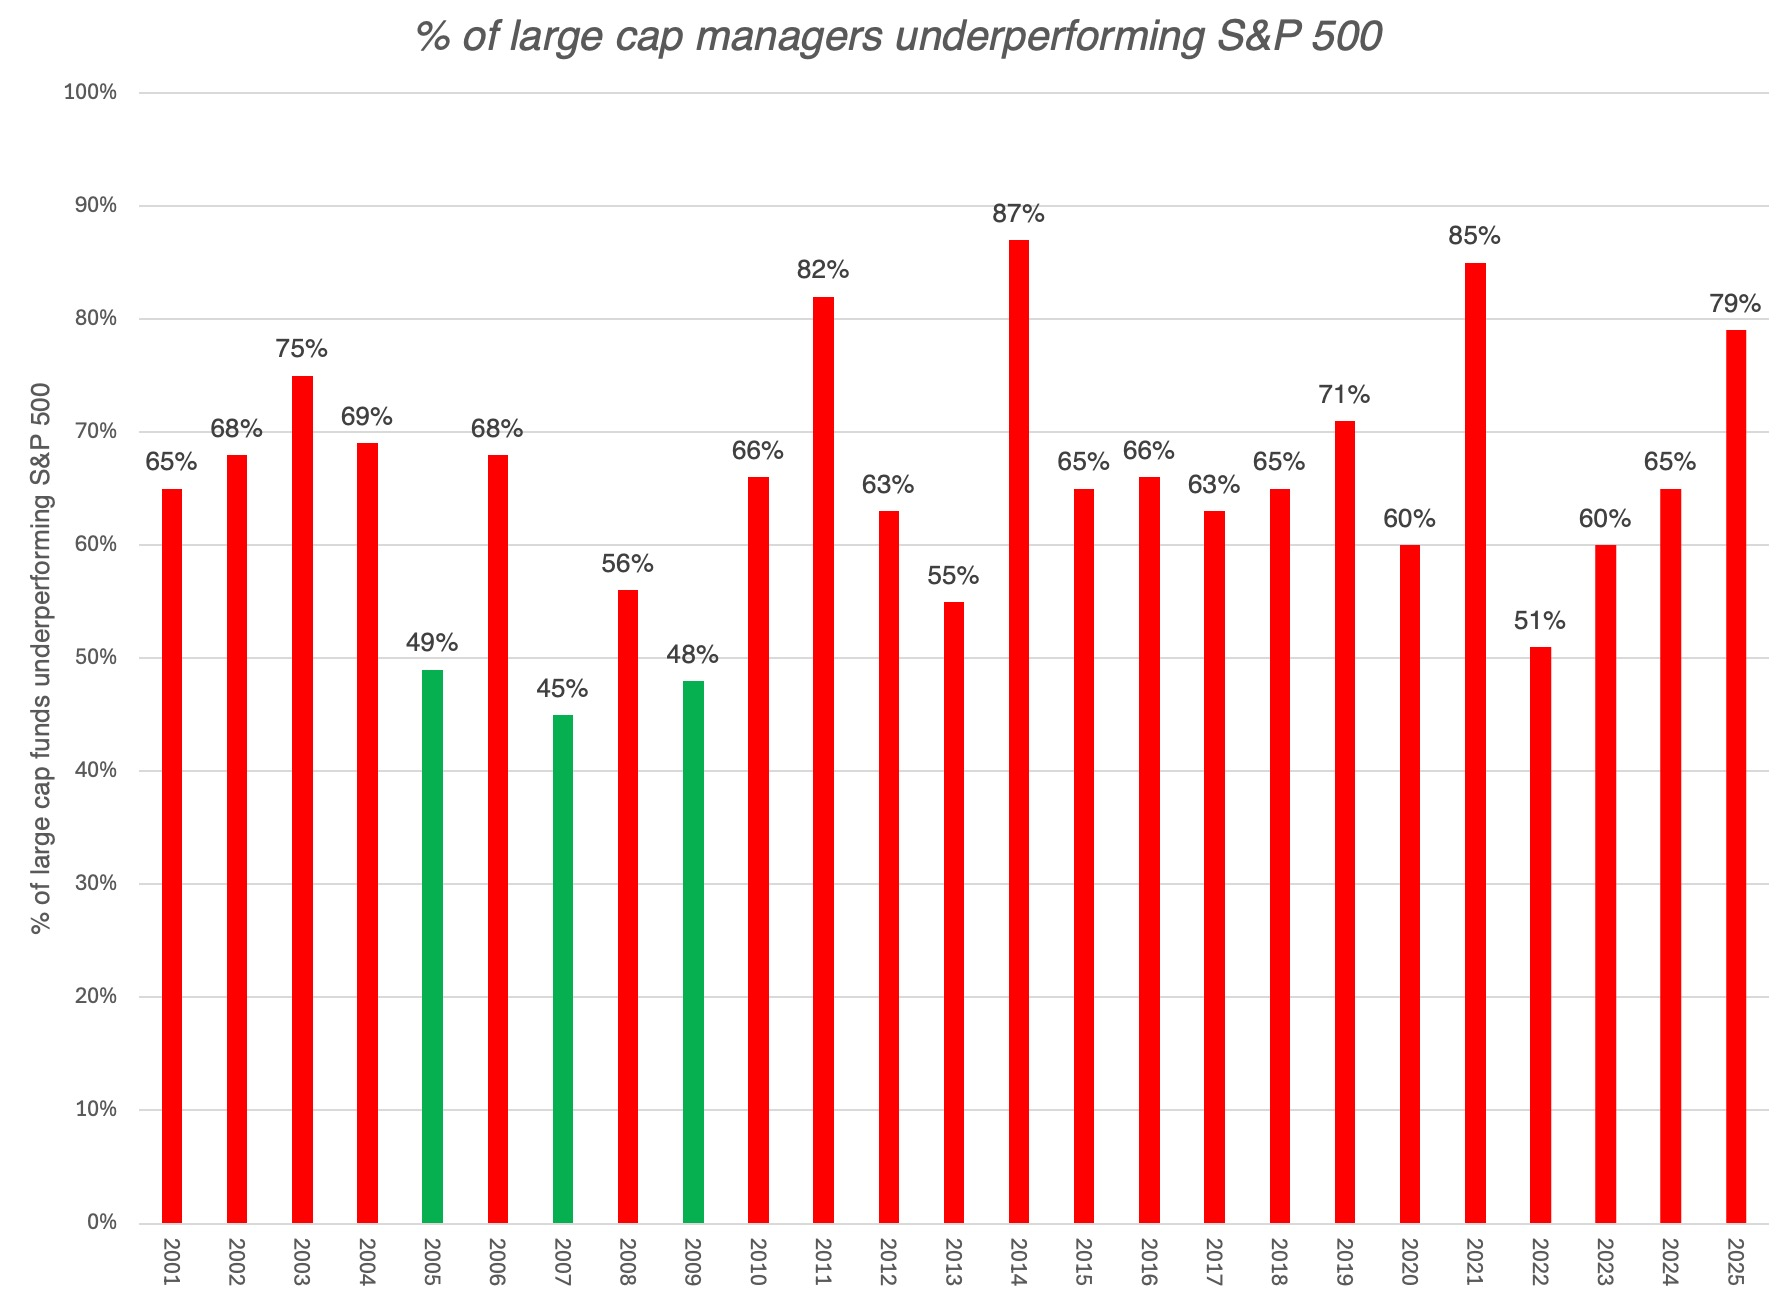
Investors who trust professionals to manage their money, and pay them for their services, either as up-front entry fees or in annual management expenses, are entitled to wonder whether they are receiving a compensatory benefit, in the form of higher returns. It should not be surprising that comparing a mutual fund’s returns to the returns on an index becomes a proxy for fund performance, and in the early years of performance evaluation, the S&P 500 became the default comparison index. Used in that context, one of the most jarring numbers in active investing is the percentage of active large cap funds that earn returns that are lower than the S&P 500, each year for the last two decades:
S&P Global
Over the last twenty five years, there have been three years where more than 50% of active funds have beaten the S&P 500 index, and barely so, and the extent of underperformance in the remaining years i staggering. The pushback from some active fund managers is that, given their investment styles, the S&P 500 is not the right index to use to judge them. Value fund managers, who invests in low-risk and high-dividend paying stock will argue that the portfolios they create are less risky than the S&P 500, making their lower returns more of a risk effect than underperformance. Academic studies that used risk and return models to tweak the index returns were quickly dismissed as being wrong, because the models that were used (the CAPM, the APM, Multi-factor models) were flawed. This deadlock was broken by S&P, when it created SPIVA, where the returns earned by fund managers in any class (small cap vs large cap, growth vs value, domestic vs foreign) are compared to returns that investors could have earned by investing in index funds in the same class, and by Morningstar, using a variant of the same approach. Thus, a fund manager who invested in small-cap, high dividend paying stocks would see his or her returns compares to the returns you would have earned on a small-cap, value index fund, making it much more difficult to explain away underperformance. There are many reasons for the slippage in active investing’s share of overall investing in the last two decades, but the SPIVA results are devastating and damning for any claim of active investing superiority. Here, for instance, are the results, by investment class, on the percentage of active fund managers who beat index funds in their investment style, over the last decade, at the end of 2025:
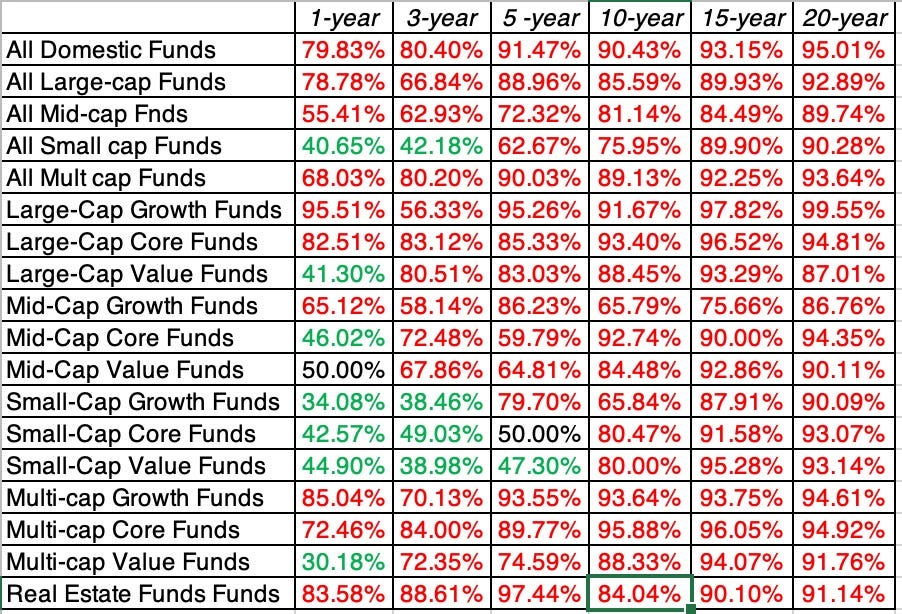
There is very little hope in these numbers, as fund managers underperform their respective indices in every single category, and by more, over longer periods. In fact, there is not a single fund group in any style that outperforms its respective index past ten years. For those of you who are reading this other geographies, and believing that it is different in your local markets, either because insiders have privileged access to information or market inefficiencies, SPIVA also tracks fund manager performance outside the United States, and reports similar results:
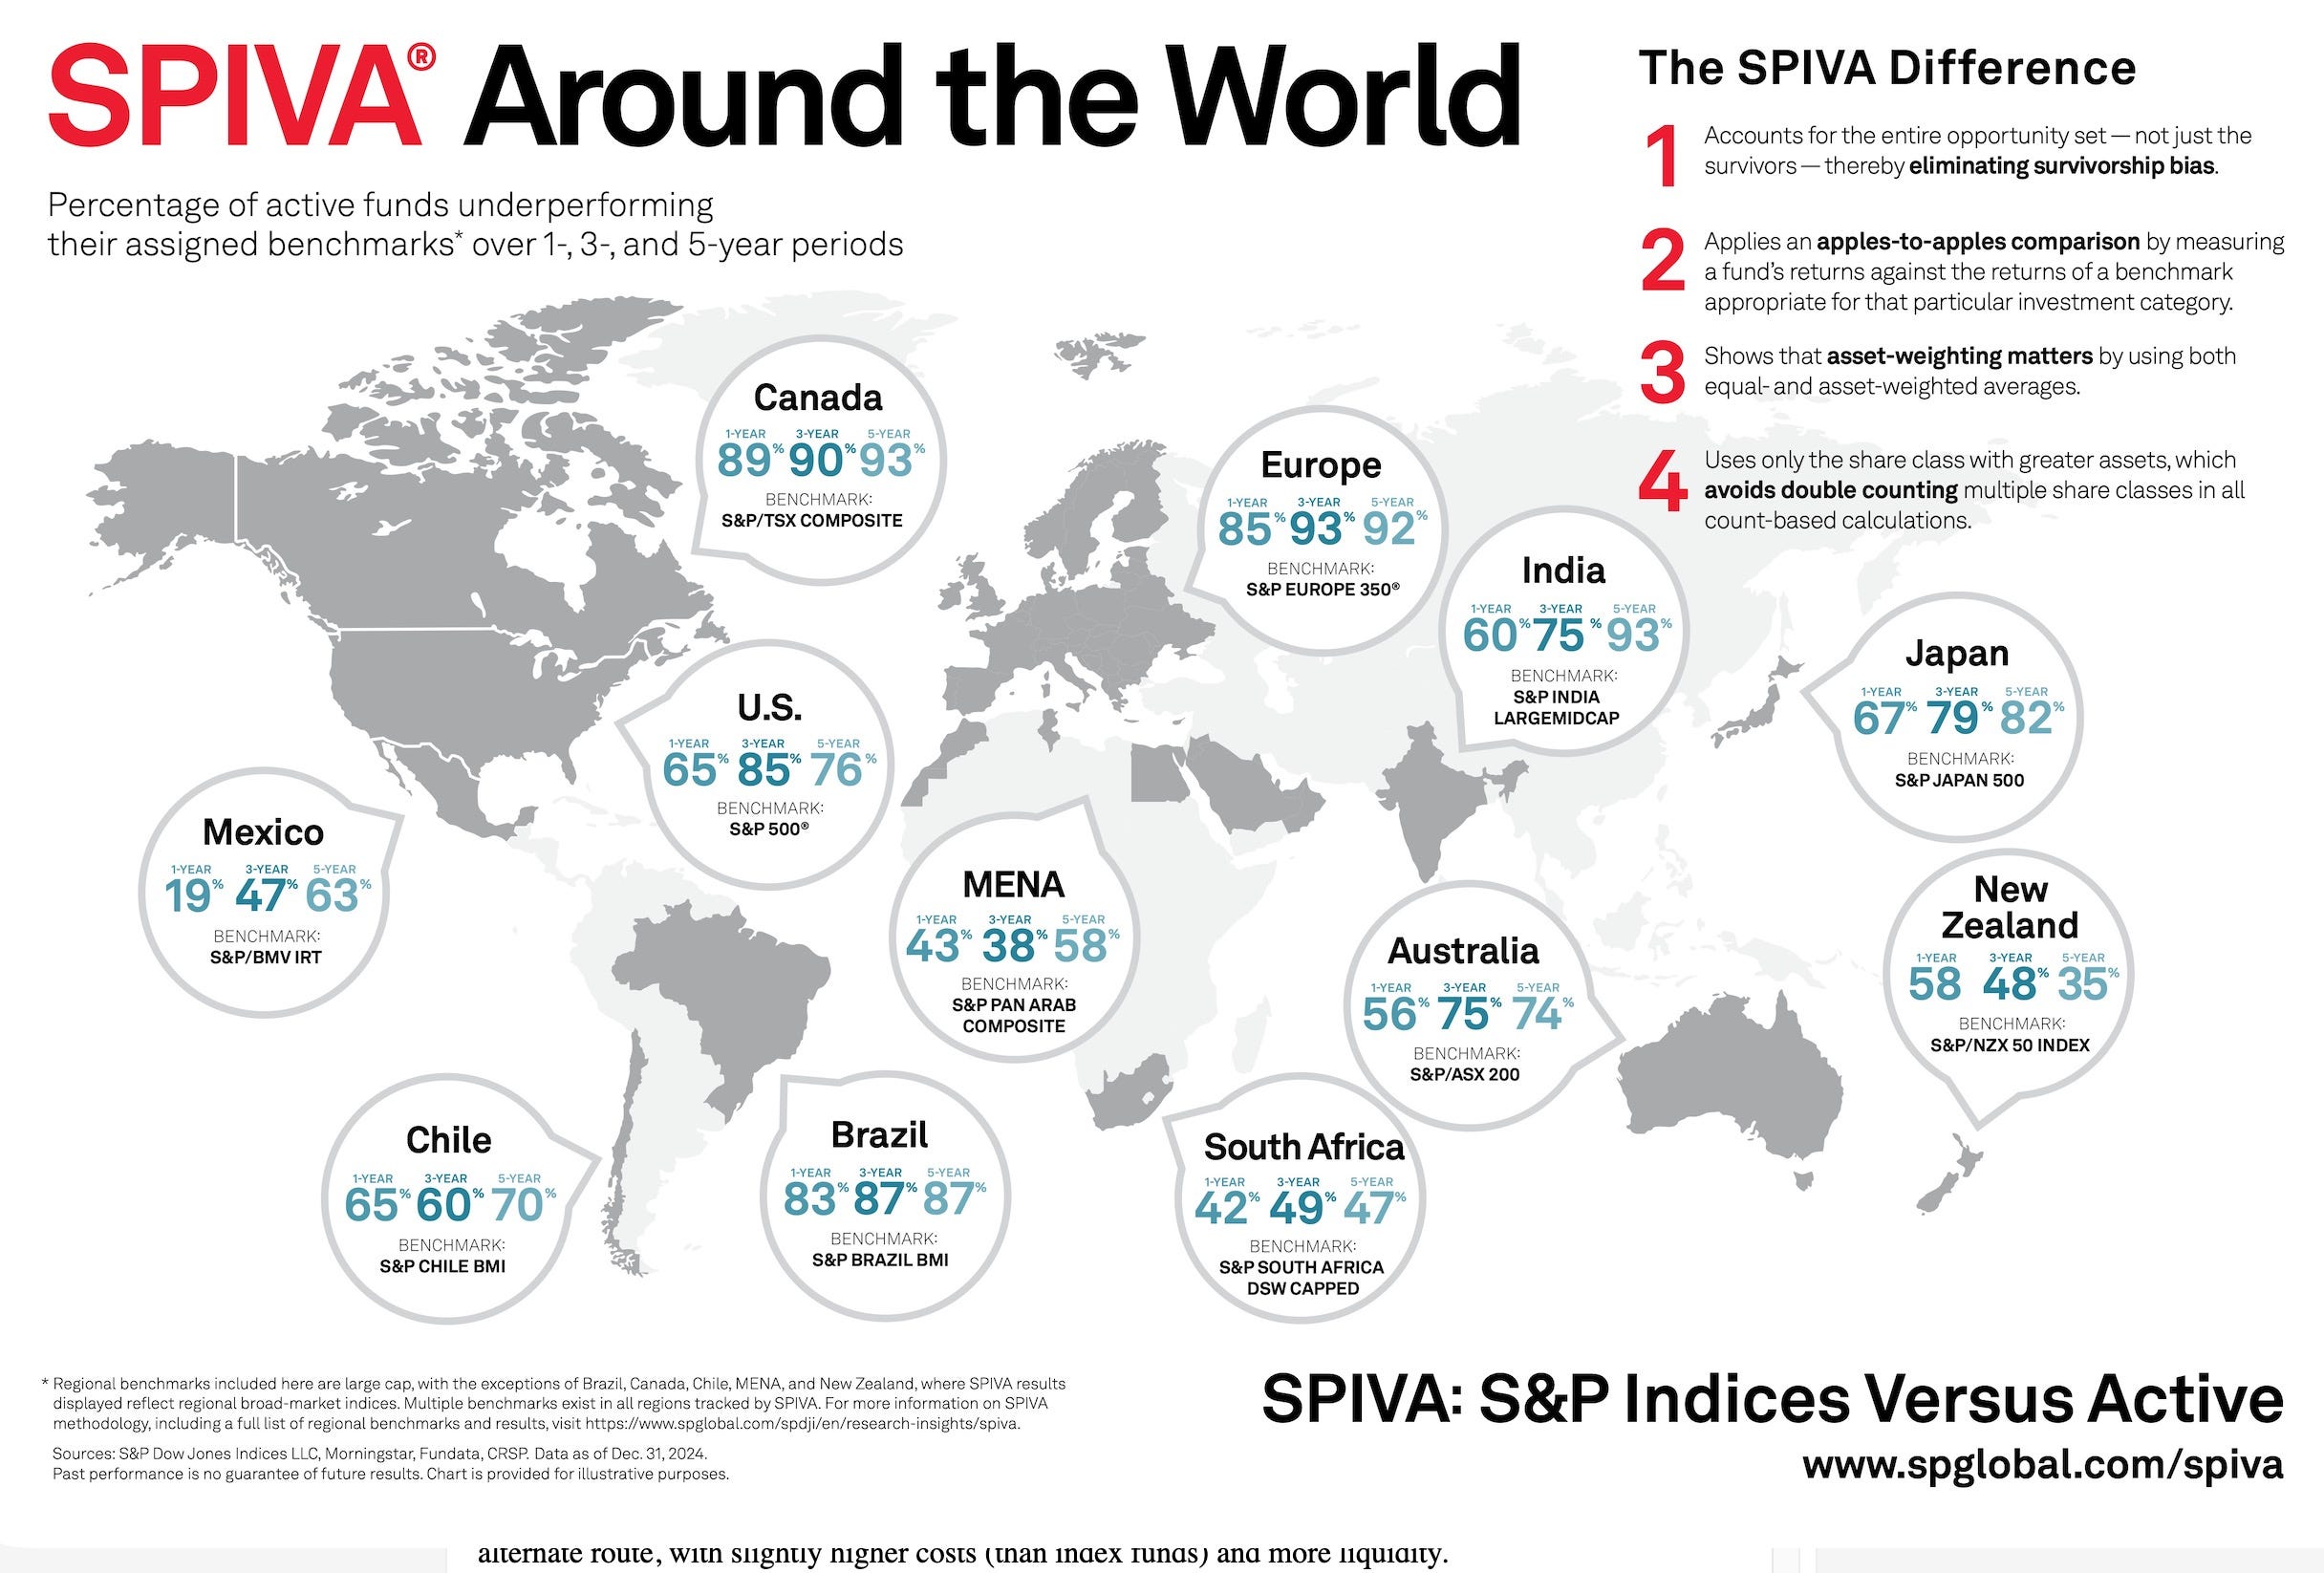
At this point, there is almost no counter to the argument that active investing collectively creates a drag on portfolio performance, and active investors seeking to defend the profession are left looking through the data entrails, hoping for niches where “alphas” exist. Thus, two decades ago, the notion that private equity investors and hedge funds were smarter than the market and could beat the market fueled a push of retirement and endowment money into these vehicles, but as they have become larger, they have come to resemble mutual funds, in terms of performance.
Investing Vehicles
There is a third use of indices that, in my view, has overwhelmed the measurement and performance evaluation roles that they play, and it is that they have become vehicles for investing in the form of index funds and exchange-traded funds (ETFs). That possibility was already existent in 1981, but at that time, the only index with an index fund available to most investors was the S&P 500. Today, you can not only invest in index funds across geographies, sectors or sub-groups based on fundamentals (including volatility, size and earnings), but the exchange traded fund explosion has given you an alternate route, with slightly higher costs (than index funds) and more liquidity.
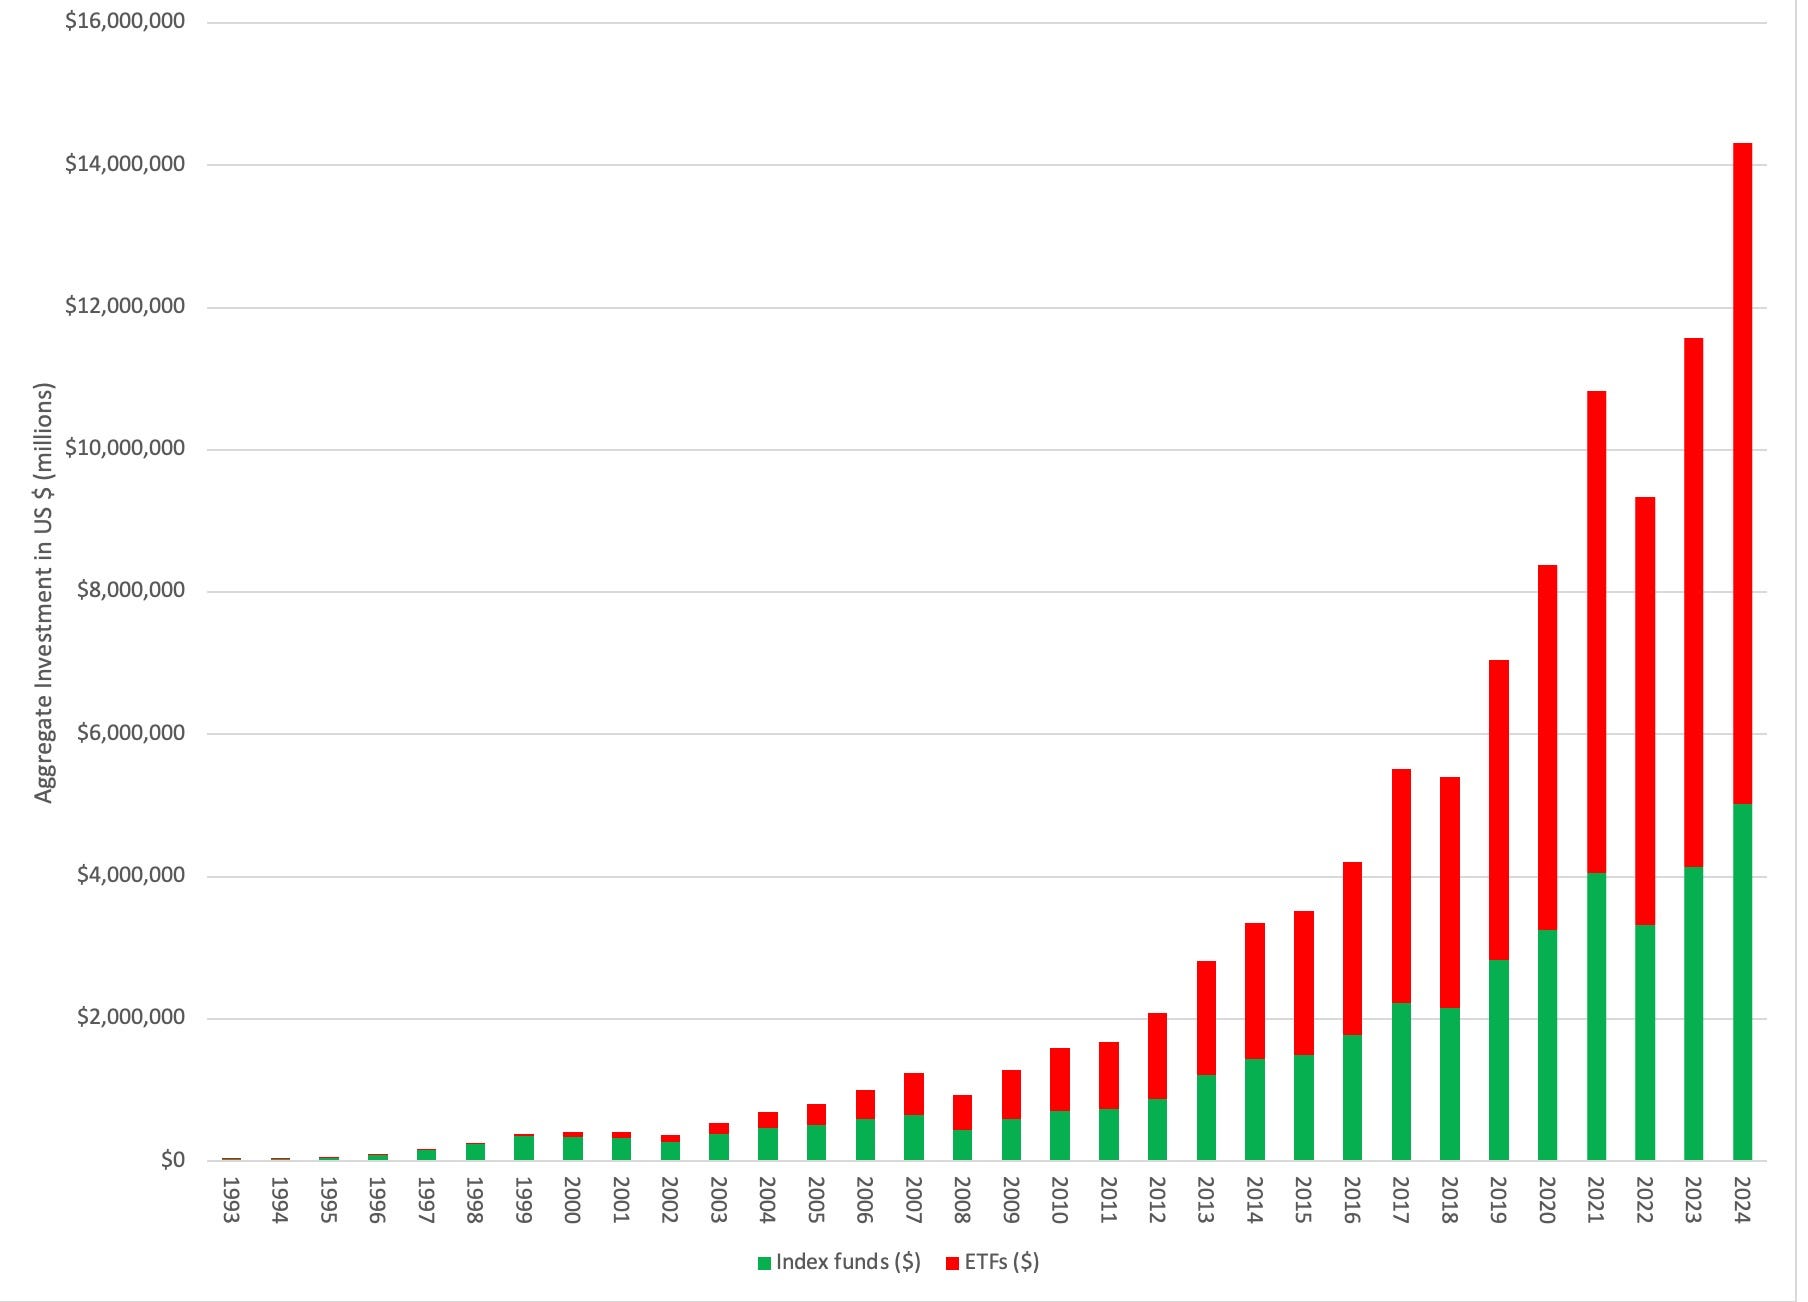
Vanguard, a pioneer when it listed the S&P 500 index fund in 1976, now lists more than a hundred ETFs and more than two hundred index funds, allowing investors to not only invest in almost any market, but also in the subsets (sectors, small companies etc.) that they chose to. The size of the index fund business and the fees its creates for the index creators has created some tensions in the process, and faced with a choice between a poorly constructed index that index fund investors would love to trade on and a better constructed one that investors find less attractive, it is possible and perhaps even likely that the fund creators will pick the former.
Indexing and Passive Investing - Unintended Consequences
There are two forces that the last section highlight that have played out in altering financial markets structurally and dramatically in the last two decades. The first is that the underperformance of active investing has become easier to document and more visible for everyone to see. The second is that investors who see this underperformance have more passive investing vehicles in the form of index funds and ETFs accessible to them, and can move their money into them. As a consequence, in the battle between active and passive investing for investor dollars, the fight is getting so one-sided that, if you were a referee, you would invoke the mercy rule and try to stop it:
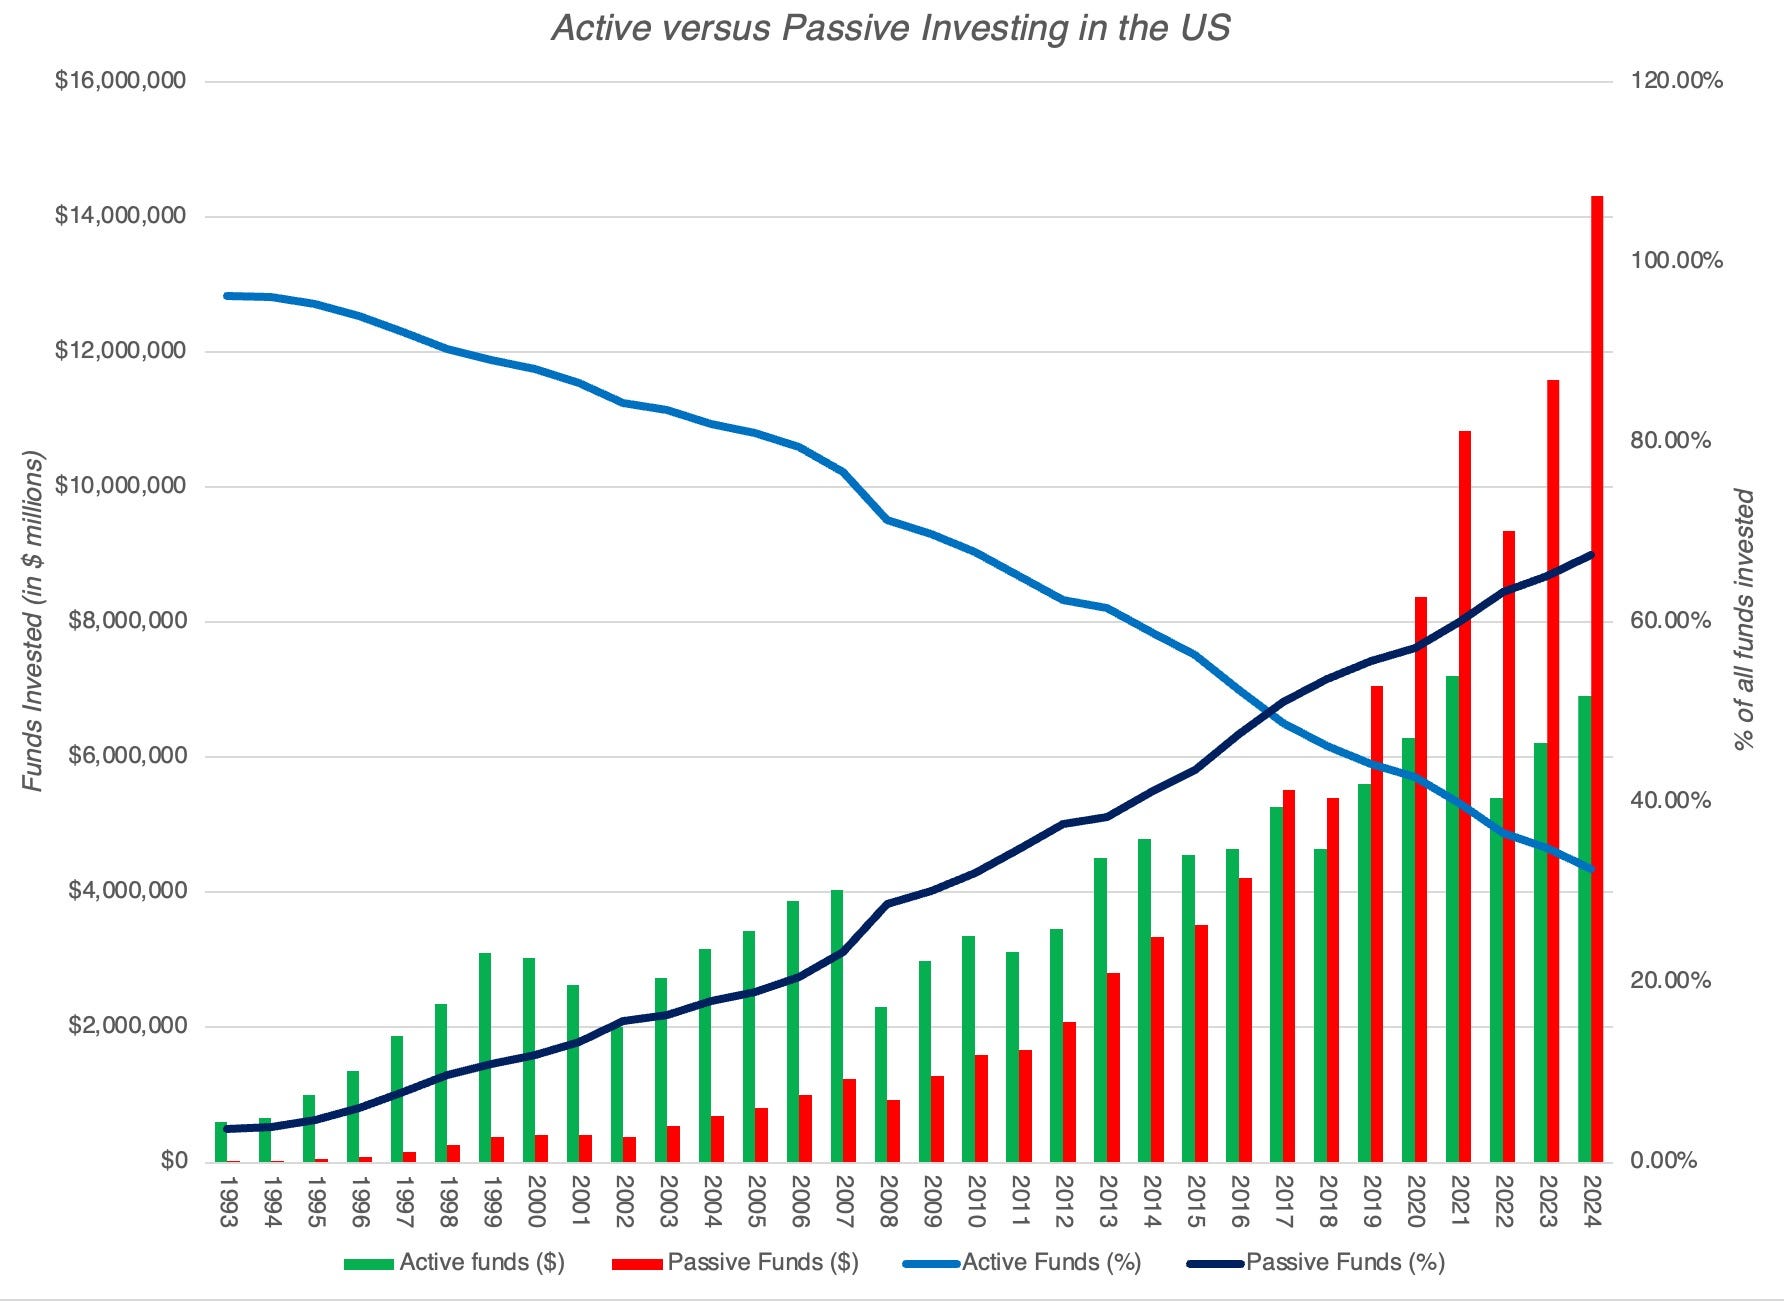
It is undeniable that the rise of passive investing vehicles has empowered investors, who have gained in terms of choice and costs, but it has also created an existential crisis for active investors, and especially so for those who make a living out of managing other people’s money. While some active investors hold on to hope - that they are better than the rest, that this is a cycle that will reverse, that some new technology (big data, AI) will save them- there are others who have taken a different tack. Mostly conceding that index funds and ETFs have outperformed fund managers, they have taken to arguing that the rise of passive investing is creating costs and effects that outweigh its benefits, and that action is needed urgently, though it is unclear from whom. In this section, I will highlight three of those effects.
1. The Index Inclusion Boost
The addition of a company to a well known or widely followed index (the S&P 500, Dow 30, MSCI Global) yields pluses, increasing its visibility to investors and potentially making it more investable, as well as increasing trading volume on the stock and making it more liquid. The question of how those benefits get priced in when a stock gets added to an index (and the costs of being removed from an index) have been studied over time, with a focus on additions to (and removals from) the S&P 500. As passive investing has grown, with more choices in index funds, it remains true that a significant percentage of passive investors hold S&P 500 index funds, and that, in the eyes of some, this should make inclusion in the S&P 500 index an even greater positive today than in decades past.
Looking across these studies, there seems to be a consensus that there is a bump up in the stock price from a company being added to the S&P 500, and bump down, when a company is deleted from the index, but disagreements both about the magnitude of the bump and whether it is permanent and transitory. The general sense that you get from studies is that bump in stock prices from being included in the index has become smaller and more transitory over time, and in the last decade or two decades, it has largely disappeared. To back this up, I look at one of the most complete studies that I have seen of the index inclusion question, where S&P took a look at the 715 companies added and 711 company deletions made to the S&P 500 between January 1995 and June 2021, and examine the excess returns in the days around the change:
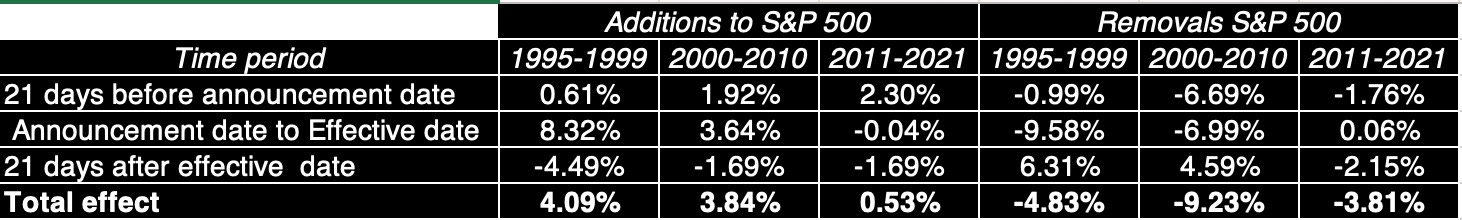
As you can see, the positiv eprice effects of being added to the S&P 500 index have depleted over time, as have the negative price effects of being removed from the index. Note that this finding cuts against the argument that as passive investing has increased in the last two decades, the allure of being in the S&P 500 should also have gone up. Instead, as the value of funds indexed to the S&P 500 has surged over the last two decades, the effect of being added to or taken out of the index has become smaller, not larger, and there is evidence accumulating that companies that get added to the S&P 500 are more likely to underperform than outperform in the twelve months after the addition.
As the debate about whether SpaceX, OpenAI and Anthropic should be included in the S&P 500 index heats up, I would suggest that the evidence of a small and dissipating price effect of inclusion has to become part of the discussion. I am sure that there will be some who will disagree with me, but I don’t think the price trajectories of any of these firms will be altered by whether they are included in or excluded from the S&P 500. For those who disagree with me, and believe that being added to index is bullish for investors in these companies, I would recommend that you look at the chart from this study which took a look at Tesla’s stock price behavior before, during and after its replacement of Apartment Investment and Management (AIV) in the S&P 500 on December 18, 2020.
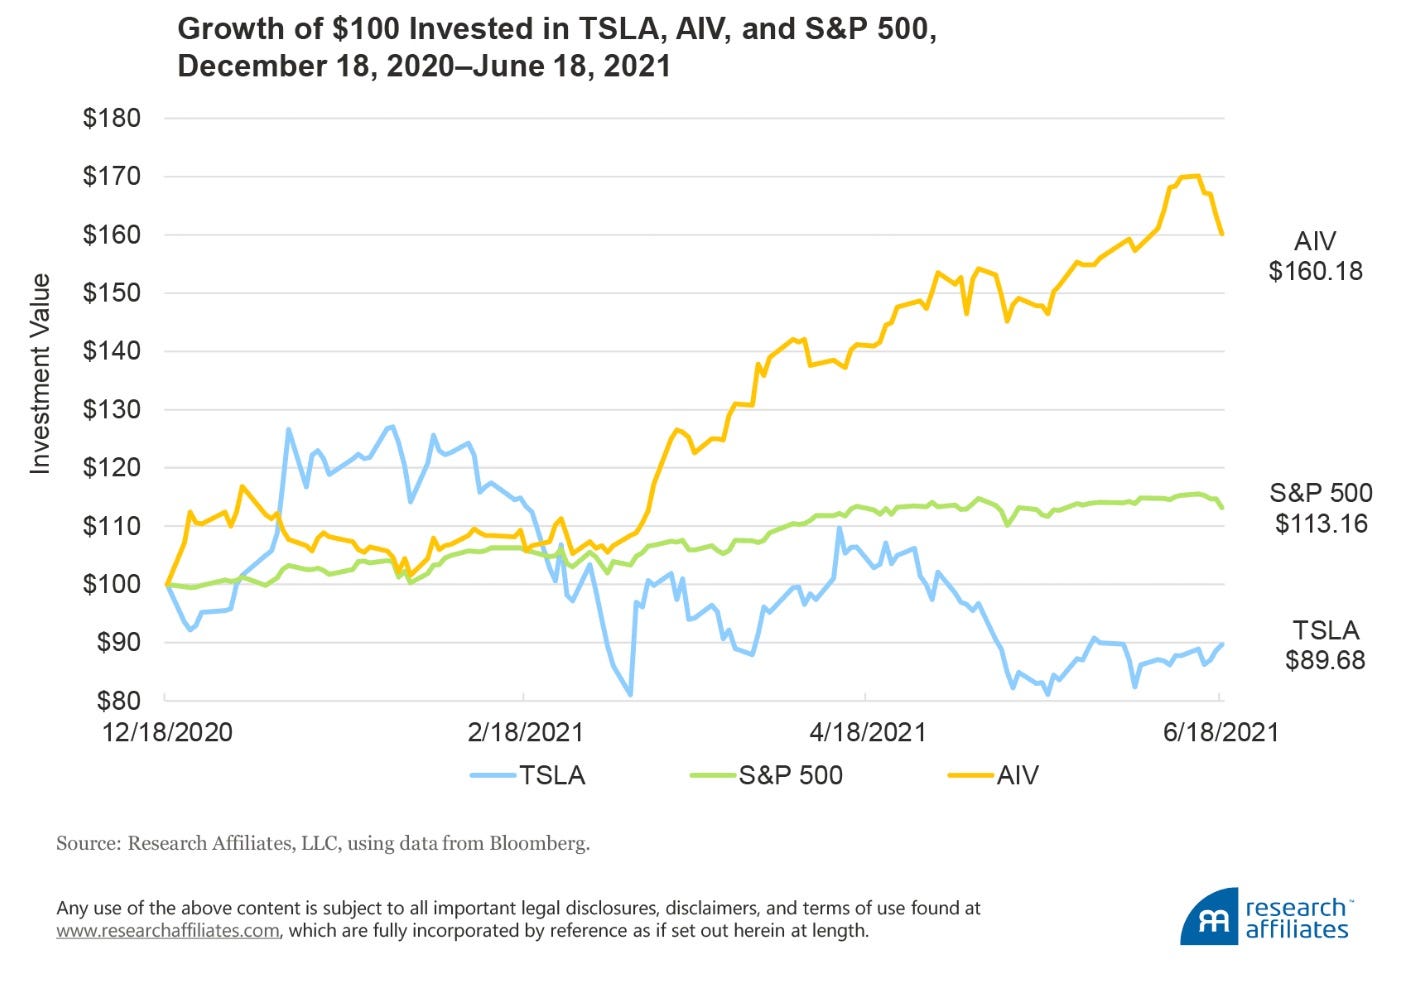
Tesla not only under performed the S&P 500 in the months after its inclusion in the index, but massively underperformed the company (AIV) that it replaced in the index.
2. Momentum versus Fundamentals
As the funds invested in index funds and ETFs has surged, the argument that some are making is that being added to an index gives you a boost, largely because of index fund flows to companies in that index, and more of a boost if you are a large cap company. Since the money flows from other stocks, this line of thought also suggests that fundamentals will receive less attention and disconnect more from prices, especially because there are fewer active investors doing research and looking for market inefficiencies. In addition, they note that since indices are mostly market cap weighted, this momentum benefits larger market cap companies, in effect allowing them to become larger. As evidence in favor of this argument, they point to the fact that markets have become top heavy, where a few winners are carrying the entire market, that the small cap premium, an enduring feature of equity markets in the twentieth century, has largely disappeared in this one and the dominance of momentum in investing success in the last decade. I concede that these phenomena are consistent with the “passive investing feeds momentum” story, but I am skeptical that passive investing is the cause for the following reasons:
Momentum can cut in both directions: It is true that funds flowing into index funds flow into the companies in that index, with more flowing into large cap companies, but it is also true that funds can flow out of index funds, and when that happens, the momentum can cut in the other direction. In fact, the conclusion is that inclusion in a widely-tracked index (like the S&P 500) will increase intraday and short term volatility, but not price levels. In fact, the fading price bump from being added to the S&P 500 that we noted in the last section is an indication that the market does not buy into the momentum story.
Winner-take-all economics: If momentum is the reason for the big companies winning, there should be divergence between small and big companies on how fundamentals get priced. Put simply, you should see the pricing metrics (PE ratios, EV to EBITDA) for large cap companies increasing relative to small cap companies, as passive investing surges. Looking back at the fading small cap effect and top-heavy markets of the last decade or two, I would note that not all large cap companies have been winners, and the winning large cap companies have delivered a disproportionate portion of increased earnings. In the context of the Mag Seven, I have talked about how technology and disruption has changed more industries into winner-take-all businesses, with a few companies dominating these businesses, and why that phenomenon will play out in markets as well.
Active investing and equity research: In my view, the notion that most analysts and active investors are looking for market inefficiencies and seeking out information strikes me as misplaced. Much of active investing is built around publicly available information and a belief in the power of mean reversion, not original research and seeking information. It is true that there is a subset of active investors and equity research analysts who contribute to making prices more informative, but that subset is a small one, and one that is better equipped to survive the passive investing shift.
Doomsday stories about how passive investing is making markets less efficient and less inclined to reflect fundamentals strike me as overwrought, and while active investing will continue to lose market share, and deservedly so, it will not disappear. Since these stories are often being told by fund managers who not so long ago spoke contemptuously about efficient markets as an academic fever dream, they also strike me as both hypocritical and self-serving.
Even if you accept the argument that passive investing is making markets less efficient and more momentum-driven is true, I am unsure about the implications for investing. Asking individual investors, retirees and endowment funds to pay fees to professionals to manage their money while underperforming indices, in service to the larger cause of market efficiency is tone deaf and a non-starter. In fact, any endowment or pension fund manager who uses this argument to steer endowment funds to active money managers would be in violation of his or her fiduciary responsibility. Perhaps, the argument is being made to regulators to restrict index funds (on which indices they can index, how much money they can manage), I can see why active money managers may be in favor, because I understand that they are trying to protect their livelihood, but they should dispense with any talk about protecting individual investors or making markets more efficient.
3. Hidden risks
An undercurrent in some of the opinion pieces that I have read about why SpaceX should not be included in the S&P 500, written by investment experts and academics, is that it will expose retail investors and retirees to risks that they are unaware they are taking, or even if made aware of the fact, should not be taking in the first place. In particular, these opinion-writers seem to be arguing that the risks associated with investing in a big, money-losing companies (like SpaceX, and presumably OpenAI and Anthropic, when they go public) are so large that individual investors and retirees would not invest in these companies, and even they would, they should not be allowed to do so. I find this chain of reasoning to be both misguided and condescending, and reflective of misconceptions that are deeply and widely held in the investment expert class:
Risk and Diversification: Is it true that individual investors, if made aware of the companies that they owned in index funds, would blanch at the risks that they have exposed to in individual holdings? Investing just in a portfolio of a few companies like SpaceX would be imprudent, but an investor in a S&P 500 index fund is far less exposed to underperforming the market than the typical active money manager who either over invests in SpaceX (if it goes down) or chooses not to invest in it (if it goes up).
Smart and Stupid Money: While the investment experts and academics who push to protect retail investors and retirees from their own mistakes will never put into words this belief, implicit in this push is the view that these small investors are uninformed and naive, and will be exploited by smart money (institutional investors and hedge funds). The notion that the smart money will know whether SpaceX (and companies like it) is overvalued or under valued, and is positioned to time investments better is fanciful, since institutional investors are more traders than investors, making them market followers, not leader.
Good businesses and good investments: The weakest link in the argument against putting your money in money-losing companies is the implicit belief that money-making companies are good (safe) investments and that money-losing companies are bad (risky) ones. I will wager than an investor who was constrained to invest only in money-making businesses in the last two decades would have under performed an investor operating without those constraints, even after adjusting for risk. At the right price, a money-losing company can be a good investment and at the wrong price, a company with solid and stable profits can be a bad investment.
I am generally skeptical of attempts to protect individual or retail investors from their own mistakes and decisions, since more damage has been done to this group by those claiming try to help and protect them over time than by those who are out to exploit them.
Conclusion
In the week prior to the SpaceX IPO, S&P removed some of the suspense in the question of whether the company would be included in the index by announcing that they would stick with their requirement that a company be listed and traded at least a year before becoming eligible for index inclusion. That decision also means that OpenAI and Anthropic, if they do go public this year, will also have to wait a year for consideration. I am glad that S&P is not changing the rules to allow these companies to jump the queue to get into the index, but I hope that it is not framed as a decision that was taken to protect investors or in the hope that these companies would become magically money making, better governed and with working business models. The truth is that a year after they list and start trading, these three companies will still be money losing businesses, with business models that are still works in progress and will remain corporate governance horror stories. S&P needs the time to manage the transition of three trillion-dollar companies into the index, even as it confronts the challenge of claiming to be a large cap index that does not include three of the largest market cap stocks in the market. As for the companies (SpaceX, OpenAI and Anthropic), I will wager that they will lose little in market momentum from not being included in the index, and that their price paths will be determined by how the AI story continues to play out in terms of both substance (growth, unit economics, reinvestment) and perception (hype and momentum). The bottom line is that S&P needs these companies in its index more than they need to be in the index, with the consequence that the companies will not go out of their way to meet index requirements that they feel are costly to them, and that if there is any bending, it will be S&P that does it.
YouTube Video
Bloomberg and the FT report today (19th June) that SpaceX is looking to issue $20bn of bonds, “expected to be priced at roughly 1.35–1.5 percentage points above US Treasuries”, supported by a Baa1 investment-grade rating (remarkable!)
I wonder how many companies in recent history have been loss-making, expected to remain loss-making for the next few years, yet still commanded an investment-grade rating.
It would be great to hear your perspective, and what synthetic rating you would assign to SpaceX!
Sir, thanks for the detailed and informative article.
Your conclusions in the "index inclusion boost" section based on Tesla's example seem to omit an important aspect: Tesla's meteoric price increase during the months leading up to the actual announcement of its inclusion.
You have rightly pointed out that the boost from index inclusion has diminished in recent years - but that's largely a result of increasing market efficiency. And this same market efficiency means that the market gets ahead of the news and, with increasing accuracy, anticipates future changes to the index.
Tesla is actually a good counter-example to what you say here: it actually benefit greatly from the index inclusion, though the benefits largely came before the actual inclusion. (But of course correlation is not the same as causation, and I admit my statement here cannot be definitely proven!)
I believe that the same dynamic is playing out here with SpaceX now, and will probably play out with Anthropic and OpenAI when they list. Their stock prices, both during the IPO process and afterwards, will benefit from the anticipation of future index inclusion, in much the way Tesla benefited in 2020. This of course doesn't mean that investors who keep holding the shares after the actual index inclusion would be happy with the returns in the long term - but those who buy before it happens are likely to benefit, if they manage to sell out at the higher prices to suckers who just happen to follow the index.
Lastly, one more point which I would like to make that you did not mention in your article: as someone with a significant part of my portfolio in index funds, my main grouse is not the index inclusion itself, but the seemingly arbitrary way in which indices are changing their own rules for the specific benefit of these companies. I would have been fine if SpaceX, etc. just happened to be added to the indices my funds track based on their long-existing and transparent rules. But the way the index providers are arbitrarily making significant changes to their methodologies is disappointing to say the least. (S&P Dow Jones seems to be holding their ground at least so far - it would have been great if others too had the same conviction in their own processes and systems!)